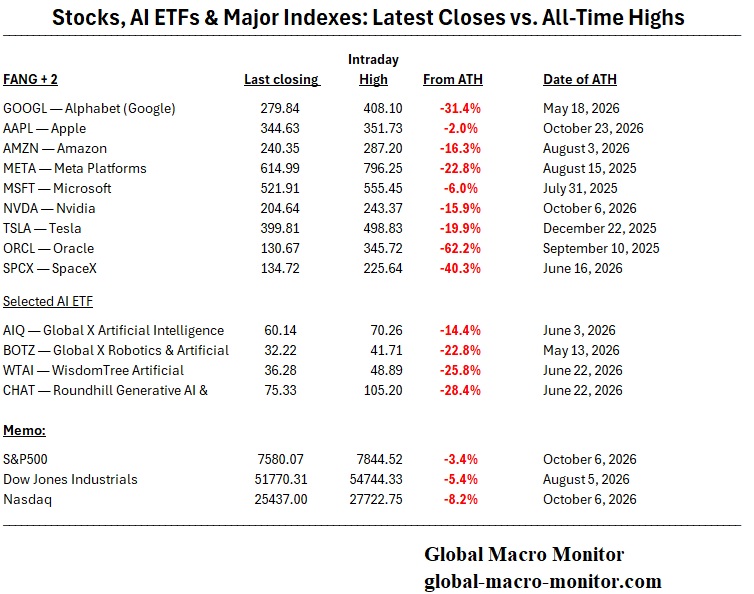
Below is a table of the casualty list of the market’s generals, the stocks that have lead the bull market to recond highs and are now nursing wounds of their own. Some have suffered more than a routine flesh wound. Yet a glance at the major indexes barely hints at the damage. Stunning.
The S&P 500 sits just 3.4% below its intraday all-time high. There is plenty of blood beneath the surface, but the headline index has scarcely needed a bandage.
That divergence deserves attention. An index can remain resilient while individual leaders suffer substantial declines, provided other constituents take up the slack. The question is whether this represents a healthy rotation into a broader group of stocks or a gradual erosion of leadership that the averages have yet to fully reflect. The casualty list alone cannot settle that debate.
For now, investors appear reluctant to abandon equities altogether. They may be changing horses rather than leaving the racetrack.
One possibility: the crowd is already positioning for another round of bigly inflation. If investors expect cash and fixed nominal payments to lose purchasing power, shares in businesses with pricing power may offer an appealing place to hide. That does not make every stock an inflation hedge. Higher input costs, rising bond yields, and falling valuation multiples can still inflict plenty of damage.
Still, the market’s resilience raises an intriguing question: Are investors holding on because they like the earnings outlook or because they like the alternatives even less?
Credits spreads are blowing out and that makes us nervous.
Stay frosty, folks.