53 years ago today, one of the most iconic photos in sport: Ali vs Liston II, captured by the brilliant Neil Leifer – @MeredithFrost
The ending of the second Ali-Liston fight remains one of the most controversial in boxing history. Midway through the first round, Liston threw a left jab and Ali went over it with a fast right, knocking the former champion down. Liston went down on his back. He rolled over, got to his right knee and then fell on his back again. Many in attendance did not see Ali deliver the punch. The fight quickly descended into chaos. Referee Jersey Joe Walcott, a former World Heavyweight Champion himself, had a hard time getting Ali to go to a neutral corner. Ali initially stood over his fallen opponent, gesturing and yelling at him, “Get up and fight, sucker!” – BoxRec
One of the most pervasive myths about the United States is that the federal government has never defaulted on its debts. There’s just one problem: it’s not true, and while few people remember the “gold clause cases” of the 1930s, that episode holds valuable lessons for leaders today. – Sebastian Edwards, Project Syndicate, May 21, 2018
Sebastian has also published an excellent synopsis of the the book, Learning from America’s Forgotten Default, on the Project Syndicate (PS) website. It is an excellent introduction to the subject material but only scratches the surface and should not be a substitute or excuse for not purchasing the book.
Money quotes from the Project Syndicate piece:
There was a time, decades ago, when the US behaved more like a “banana republic” than an advanced economy, restructuring debts unilaterally and retroactively
In April 1933, in an effort to help the US escape the Great Depression, President Franklin Roosevelt announced plans to take the US off the gold standard and devalue the dollar.
…this would not be as easy as FDR calculated. Most debt contracts at the time included a “gold clause,” which stated that the debtor must pay in “gold coin” or “gold equivalent.”
These clauses were introduced during the Civil War as a way to protect investors against a possible inflationary surge.
…the gold clause was an obstacle to devaluation. If the currency were devalued without addressing the contractual issue, the dollar value of debts would automatically increase to offset the weaker exchange rate, resulting in massive bankruptcies and huge increases in public debt.
Congress passed a joint resolution on June 5, 1933, annulling all gold clauses in past and future contracts.
Republicans were dismayed that the country’s reputation was being put at risk, while the Roosevelt administration argued that the resolution didn’t amount to “a repudiation of contracts.”
On January 30, 1934, the dollar was officially devalued. The price of gold went from $20.67 an ounce – a price in effect since 1834 – to $35 an ounce.
…those holding securities protected by the gold clause claimed that the abrogation was unconstitutional.
Lawsuits were filed, and four of them eventually reached the Supreme Court; in January 1935, justices heard two cases that referred to private debts, and two concerning government obligations.
On February 18, 1935, the Supreme Court announced its decisions. In each case, justices ruled 5-4 in favor of the government – and against investors seeking compensation.
Justice James Clark McReynolds… wrote the dissenting opinion – one for all four cases… He ended his presentation with strong words: “Shame and humiliation are upon us now. Moral and financial chaos may be confidently expected.”
…the 1935 ruling is invoked [today] when attorneys are defending countries in default (like Venezuela). And, as more governments face down new debt-related dangers – such as unfunded liabilities associated with pension and health-care obligations – we may see the argument surface even more frequently.
…the US government’s unfunded liabilities are a staggering 260% of GDP – and that does not include conventional federal debt and unfunded state and local government liabilities.
A key question, then, is whether governments seeking to adjust contracts retroactively may once again invoke the legal argument of “necessity.”
The US Supreme Court agreed with the “necessity” argument once before. It is not far-fetched to think that it may happen again. – Sebastian Edwards
A Roadmap?
There you have it, folks.
The good professor lays it all out, which may or may not be the roadmap for how the U.S. and other highly indebted governments resolve their ,massive and almost impossible to fulfill contractual obligations to both creditors and its citizens. The Supremes have already ruled in favor of the government under the “necessity” argument.
Modern Monetary Theory (MMT)
Sebastian’s material gives us much ammunition in arguing with the Modern Monetary Theory crowd, who believe a sovereign government cannot and will never default on its local currency obligations if it has an independent central bank. Of course, they will argue that FDR and the U.S. didn’t have an independent monetary policy because of its link to the gold standard.
It seems to us the MMT crowd believe that because a government has an independent central bank and can always print money to payoff debt, they will never, ever experience rollover risk. Complete nonsense.
Can you say Venezuela?
When a government experiences financing problems through a sudden stop in funding, the leaders must make a political decision on whom to inflict the pain.
Either default, which hurts their creditors, and who be predominantly consists of foreigners, as was the case in Russia in 1998; and is the case with the U.S. federal government marketable debt in 2018; or monetizing the rollover, resulting in hyperinflation and wiping out domestic residents.
We have the first-hand experience of the latter and have written about it in many posts over the years,
We’ll also never forget being in the Bulgarian central bank in 1996 just before some very large maturities of treasury bills were coming due. The market had lost confidence in the government and a high ranking central bank official looked us straight in the eye and said “we will not let the government default.”
We knew instantly a massive amount of liquidity was about to hit the local markets, the demand for the currency was going to collapse, and the country was headed for hyperinflation. Rioting broke out, the government fell, and the country eventually implemented a currency board, not too dissimilar from that of the Euro, in order to enforce fiscal discipline upon the government. – GMM, November 2011
We suspect when the day of reckoning comes for the United States to pay for its debt profligacy, it won’t be such a simple binary choice. There will be many and various types of public sector obligations in the queue to be paid, which may require differential treatment.
Sebastian’s example of the U.S. government default in the 1930’s is a combination of both. The default on the contractual gold clause and the inflating away of much of the debt through devaluation.
This is tantamount to an emerging market government unilaterally and retroactively converting its foreign currency debt into local currency and then monetizing it, and supported by the legal system.
How would that work out for, say, Venezuela dollar denominated bond holders?
Let’s hope our political leaders and policy makers come to their senses before that dreadful day is upon us.
Now take the few minutes to read the full article and go buy the book for some excellent beach reading. .
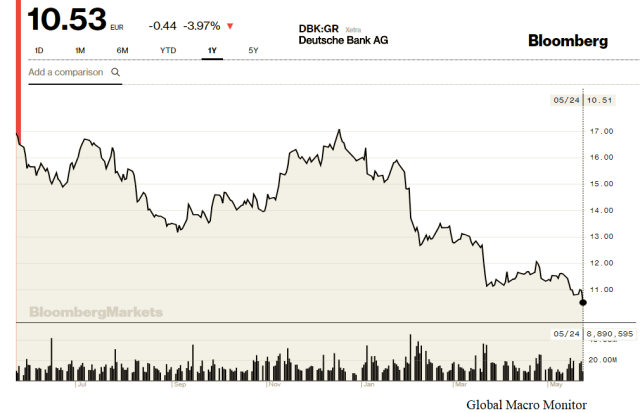
The markets are about €0.53 away from having a Jackie Moon moment when Deutsche Bank’s stock becomes a single digit midget (non-p.c., my bad). As per September 2016, when it traded single digits for a few nanoseconds, we are not so sure the financial authorities will allow it to get or stay there.
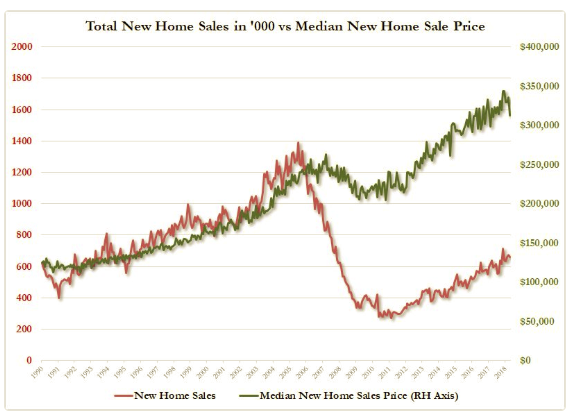
Clearly, a shift in the supply curve for new homes to the left.
OK – and some buying at irrational prices fueled by artificially low-interest rates and excess money. The irrational panic buying will take care of itself as interest rates rise and the Fed reduces its balance sheet making money tighter.
This is not the highly leveraged housing market of 2006-07, where even our range boy at the local golf club owned mortgaged three homes, quit his job, and bought an Escalade financed by a home equity loan (true story). This market is driven primarily by restricted supply and will be more difficult to pop. The price adjustment will also take place over a much longer period.
The New Supply-Side Economics Is Not Good
We have written how private equity has taken a yuuuge supply of existing homes off the market through their mega 2012-14 bankruptcy purchases, and now rent out the homes to the same people they foreclosed on. Existing housing is a perfect substitute for new homes.
Rising Costs
The rising costs of building, primarily labor shortages in the construction sector, and restrictive zoning laws are constraining building and the supply of new homes.
The lack of enough skilled workers and a narrow talent pipeline has added extra hurdles, time, and costs to many current projects, according to builders, hindering the current boom time in the industry.
“The number one issue is the cost and availability of labor,” says Randy Strauss, owner of Strauss Construction in Amherst, Ohio, roughly 40 miles east of Cleveland.
The issue is a nationwide one. Contractors in areas such as Houston, which were battered by Hurricane Harvey last year, have struggled to staff up, and the National Association of Home Builders recently found that 82 percent of its members believe the cost and availability of labor are their biggest issues. In 2011, only 13 percent named labor costs as their biggest worry. — Curbed
The immigration crackdown has played a significant role in the labor shortage in the construction sector.
One study from the National Bureau of Economic Research found that over 1.1 million undocumented immigrants, many of them skilled in essential trades such as framing, work in the construction industry. – CITYLAB
Lumber Prices
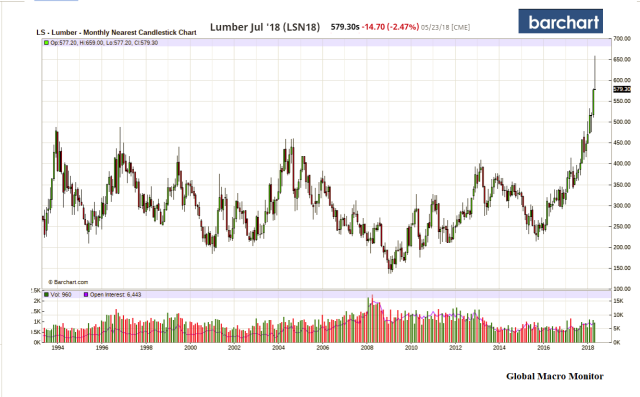
The parabolic rise in lumber prices isn’t helping either. Lumber prices are down over 12 percent from last week’s high, however, with several days of limit down in the futures markets. Look no further than the long-term lumber price chart to understand what tariffs do to prices and input costs, which ultimately hurt the majority.
Last April, the Trump administration placed a 20.83 percent tariff on Canadian lumber, to the benefit of politically valuable voters in Maine. Within the construction industry, these imports commonly turn into framing lumber, which is used to build single-family homes and small multifamily buildings. – CITILAB
Bad timing by the administration unless you belong to the small minority of those who make their living in the framing lumber business.
Policy Relief Needed
Shortages are breaking out and are now ubiquitous throughout the economy.
The housing market is one of the hardest hit sectors. Shortages of new and existing homes; shortages of buildable land, shortages of skilled construction workers. Inflation is running rampant in the sector. Yet it hardly registers in the inflation indices because of the way the government measures housing costs.
The new supply-side of housing (shifting the curve left) is not working for most Americans. Taking existing homes off the market for rentals or the restriction of new supply through rising input costs, labor shortages, and zoning restrictions are severely reducing affordability and turning the country into a Landlord Nation.
Since most of the problems are policy-induced, they can be fixed by better and a more comprehensive housing policy. That is getting back to the old supply-side economics of the Reagan era where the supply curve shifts to the right, illustrated in the simple graph below. Lower prices with more supply of homes (P 2, Q 2).
Higher prices and lower supply may work for some, but it is certainly not good economics and only adds to an already toxic political environment.
Intelligent, indestructible and with no humans on board, these sailboats are plotting their own course through the waters of San Francisco Bay. If Richard Jenkins gets his way, soon there’ll be hundreds of them – trawling the oceans for data.
Video by Victoria Blackburne-Daniell, David Nicholson – Bloomberg
…what Kim’s move reveals is a broader strategy at work. In the lead-up to the Singapore summit, should it still take place, Trump may be preparing for the wrong game: a two-player round of checkers when Kim is steeling for a multiplayer two-board chess match. On one board will be the future of North Korea’s nuclear weapons programs, what Trump came to negotiate. On the other will be what Kim and the other participants know is also crucially at stake: the future of geopolitics in northeast Asia. – Foreign Affairs
Xi and Kim’s Second Meeting
Did President Trump Just Have An Epiphany?
President Trump may have finally had an epiphany that China’s President Xi and Kim Jong Un are engaged in three-dimensional diplomacy and may be playing him. After today’s press conference it sure sounds like it.
We have been pounding the table about this in several posts over the past few months. See here, here, here, and here.
Today’s Presser
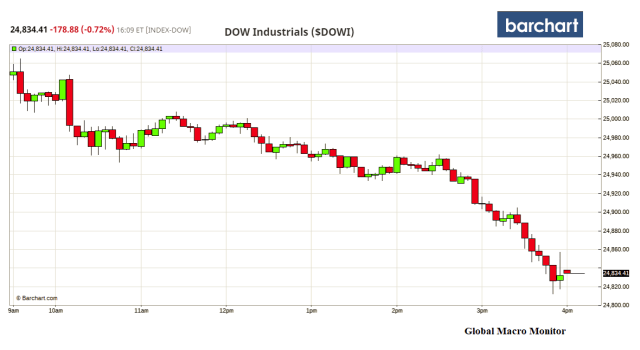
Here is what President Trump said during today’s impromptu presser in the Oval Office with South Korean President Moon Jae-in. His comments, by the way, caused stocks to sell off into the close. We warned about these risks yesterday.
I will say I’m a little disappointed because when Kim Jong Un had the meeting with President Xi in China, the second meeting — the first meeting we knew about, the second meeting I think there was a little change in attitude from Kim Jong Un.
..there was a difference when Kim Jong Un left China the second time. And I think they were dedicating an aircraft carrier that the United States paid for, OK?
QUESTION: … China maybe discouraged Kim?
..I think that President Xi is a world class poker player…I will say this, there was a somewhat different attitude [from North Korea] after that meeting, and I’m a little surprised.
…maybe nothing happened.., But there was a different attitude by the North Korean folks when — after that meeting. So I don’t think it was a great meeting.
Nobody knew about the meeting and all of a sudden it was reported that he was in China a second time. The first time everybody knew about, the second time was like a surprise. And I think things changed after that meeting. So I can’t say that I’m happy about it, OK? – President Trump, May 22
President Xi, a world-class poker player, indeed. Even your so-called friends covet your poker chips.
President Trump is learning by doing, Lord Palmerston’s dictum, “in international relations, there are no permanent friends or permanent enemies, only permanent interests.”
History Of Korea And China
We believe there is no way in hell President Xi will allow a unified Korea under western influence. Losing Korea on his watch? NFW!
Let’s go back just to 1950 to understand China’s strong national interest in Korea, which probably hasn’t changed much from a strategic perspective, even though the world is entirely different. Also, keep in perspective, Xi is the new Mao.
If we allow the United States to occupy all of Korea, Korean revolutionary power will suffer a fundamental defeat, and the Americans will run more rampant and have negative effects for the entire Far East. Threat of U.S. Bombing – Mao Zedong, Secret Cable to Stalin, Oct. 2, 1950
Two weeks after the Stalin cable, China invaded North Korea, surprising American troops, who were heading the United Nations military effort to protect the South Korean Government of Syngman Rhee. Thankfully, for us, Stalin reneged on his offer to supply air cover for the Chinese invasion force.
General Douglas MacArthur, the commander of the U.N. forces, openly doubted China’s resolve to move into Korea. The entry of 260,000 Chinese troops into the war, shocked the American commanders and forced them into “the greatest retreat in United States military history.”
Different Time, Same Chinese “Permanent Interest”
Of course, the times are different.
China is now a nuclear and rising world superpower and beginning to challenge U.S. hegemony. They now control the South China Sea.
China, will, no doubt, have a seat at the table at the Singapore summit, if there is one, maybe not literally, but in the form of the deal already cut with the North Koreans.
Who knows what kind of deal Xi and Kim have cut, but there is no doubt they have an agreement of some sort, which is also playing into the U.S.- China trade talks, and that realization is now in Trump’s head. Go no further than today’s presser for proof of the latter.
Deutsche Bank (DB) stock is approaching single digits again. Watch this space.
In 2016, DB traded with a single digit handle for a few seconds before, we suspect, the monetary authorities stepped in.
When a “too big to fail” (TBTF) bank stock falls to into single digits, the risk of panic increases, the bank may begin to experience funding pressure, short selling proliferates, and systemic risk skyrockets.
Unlike Lehman, however, DB has a deep deposit base and is less dependent on wholesale market financing.
We are not certain why the stock is plummeting, but we do suspect markets are getting a bit concerned about Deutsche’s humungo derivatives book, and the global size of the derivatives markets, in general.
Derivatives, especially credit default swaps (CDS), are a legacy of the financial crisis which was ignored and never really dealt with.
Derivatives have never really gone away in the ensuing decade. The total value of the books at five of the biggest US banks has dropped about one-quarter since tougher capital rules kicked in, from 2013. Even so, there were $157tn of derivatives out there at the end of last year, according to data prepared for the FT by Aite Group, a Boston-based research firm. That’s about 12 per cent more than the amount these banks had, entering the crisis.
…The banks say these huge numbers — $157tn is more than twice global GDP — do not tell the whole story. And they are right: headline figures say nothing about the counterparties, the collateral, the offsetting positions, or whether the trades are centrally cleared. (Bear’s actual credit exposure — or its “net replacement cost of derivatives contracts in a gain position”, in the jargon — was much smaller, at $12.5bn.) – FT, March 16
Though, we believe it is a small probability, if the markets do run on DB’s derivatives book, even God won’t be able to save it.
Low probability, high impact event. A major macro swan. Keep it on your radar.