

Summary
Commentary: Big events this week, though we expect quiet trading with the July 4th holiday and tomorrow’s World Cup match between Brazil and Mexico.
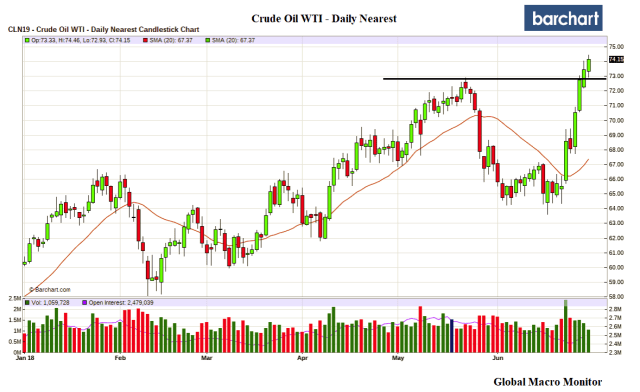
Our focus: 1) let’s see how crude responds to the Trump tweet; 2) how EM reacts to the election of the lefty president, AMLO in Mexico; 3) U.S. tariffs and retaliatory tariffs take effect on July 6th, and 4) most important, the Fed steps up it Quantitative Tightening cap to $40 billion per month,
We estimate the Fed will reduce its SOMA Treasury portfolio by $24 billion and the MBS book by $11.2 billion in July. It is more challenging to estimate MBS redemptions due to the uncertainty of prepayments. We also expect the SOMA portfolio will have only $6.3 billion available to rollover into Treasury auctions in July, which are increasing in size by 13 percent per month on average y/y in 2018. Thus Fed participation in July’s Treasury auctions will be reduced to 2 percent of total new issuance, compared to 7 percent in June and 15.6 percent in May. On the margin, and all other things being equal (they never are), this should put upward pressure on interest rates, especially if traders realize and internalize the data.
Since QT began in October 2017, we estimate the Fed has reduced its holding of T-notes and bonds by $98.3 billion and the MBS book by $46.9 billion, for a total of $141 billion. The balance sheet reduction is not insignificant and equivalent to around 3.7 percent of the U.S. adjusted monetary base. We maintain this is what really matters and should be the focus of investors and not the obsession over interest rates.




Punta del Este, templo de celebridades
Messi’s offshore tax mess
Barcelona star Messi, was already under investigation in Spain on charges that he and his father, Jorge Horacio Messi, used offshore companies in Belize and Uruguay to avoid paying millions of dollars in taxes when the Panama Papers revealed he owned yet another offshore company: Mega Star Enterprises, based in Panama. – The Irish Times


Stunning. Beware of linear extrapolation.
North American geopolitics are about to get very interesting on Sunday. President Trump is about to meet his match.
As far as the United States is concerned, if the Trump era has strained relations with Mexico, Amlo’s election could change the dynamic even more drastically. In the best of circumstances, both countries would continue to ignore each other. In the worst, Trump would continue alienating Mexico in a way that will take generations to repair. – The Atlantic
Stay tuned.
Andres Manuel Lopez Obrador lost the Mexican presidential election by less than one percentage point six years ago. He’s trying again and this time he’s leading the polls. So here are five things you need to know about “Amlo”. Please subscribe HERE http://bit.ly/1rbfUog
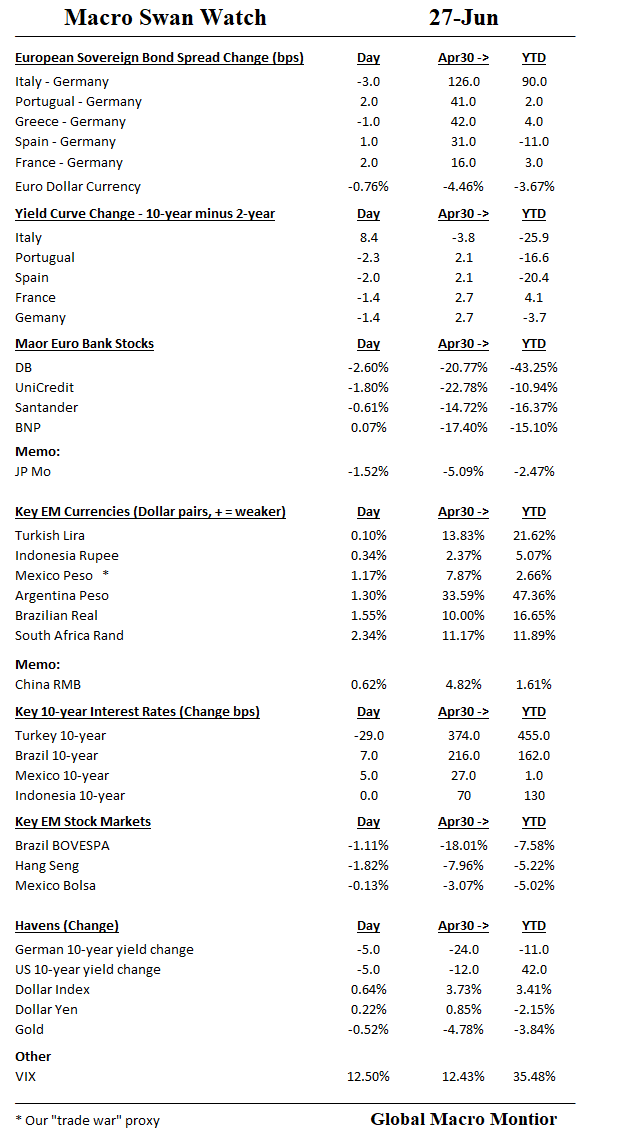
Dullsiville on Swan Lake today. Argentine peso weaker.
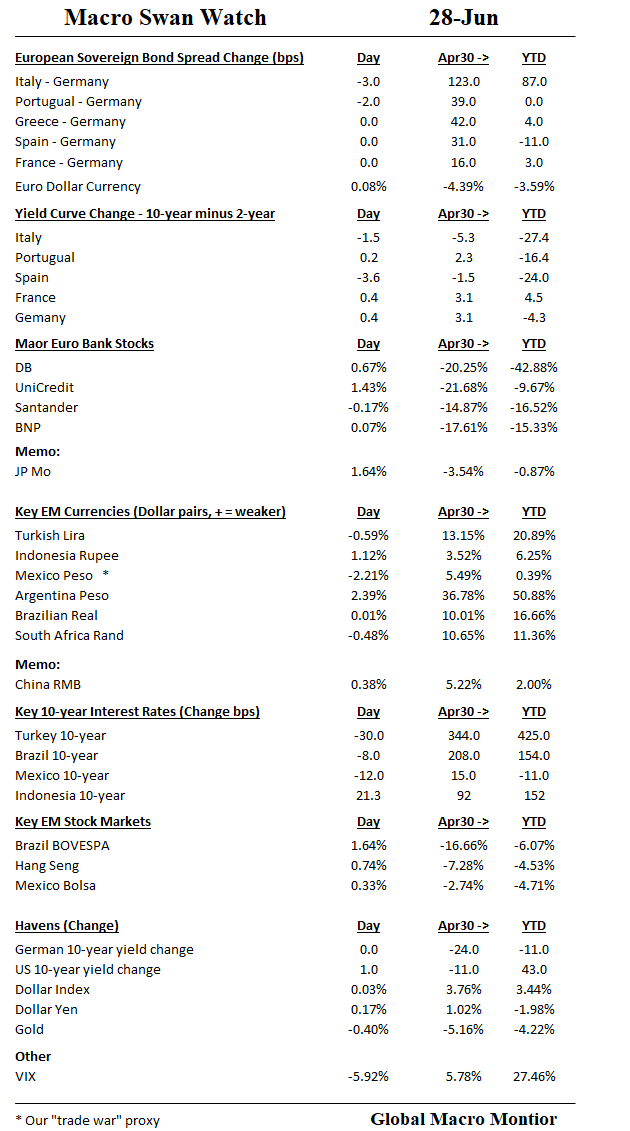
The Global Macro Monitor defines “macro swan” as any global macroeconomic or financial event with the capacity to spill over into world markets causing risk aversion and lower asset prices. – GMM
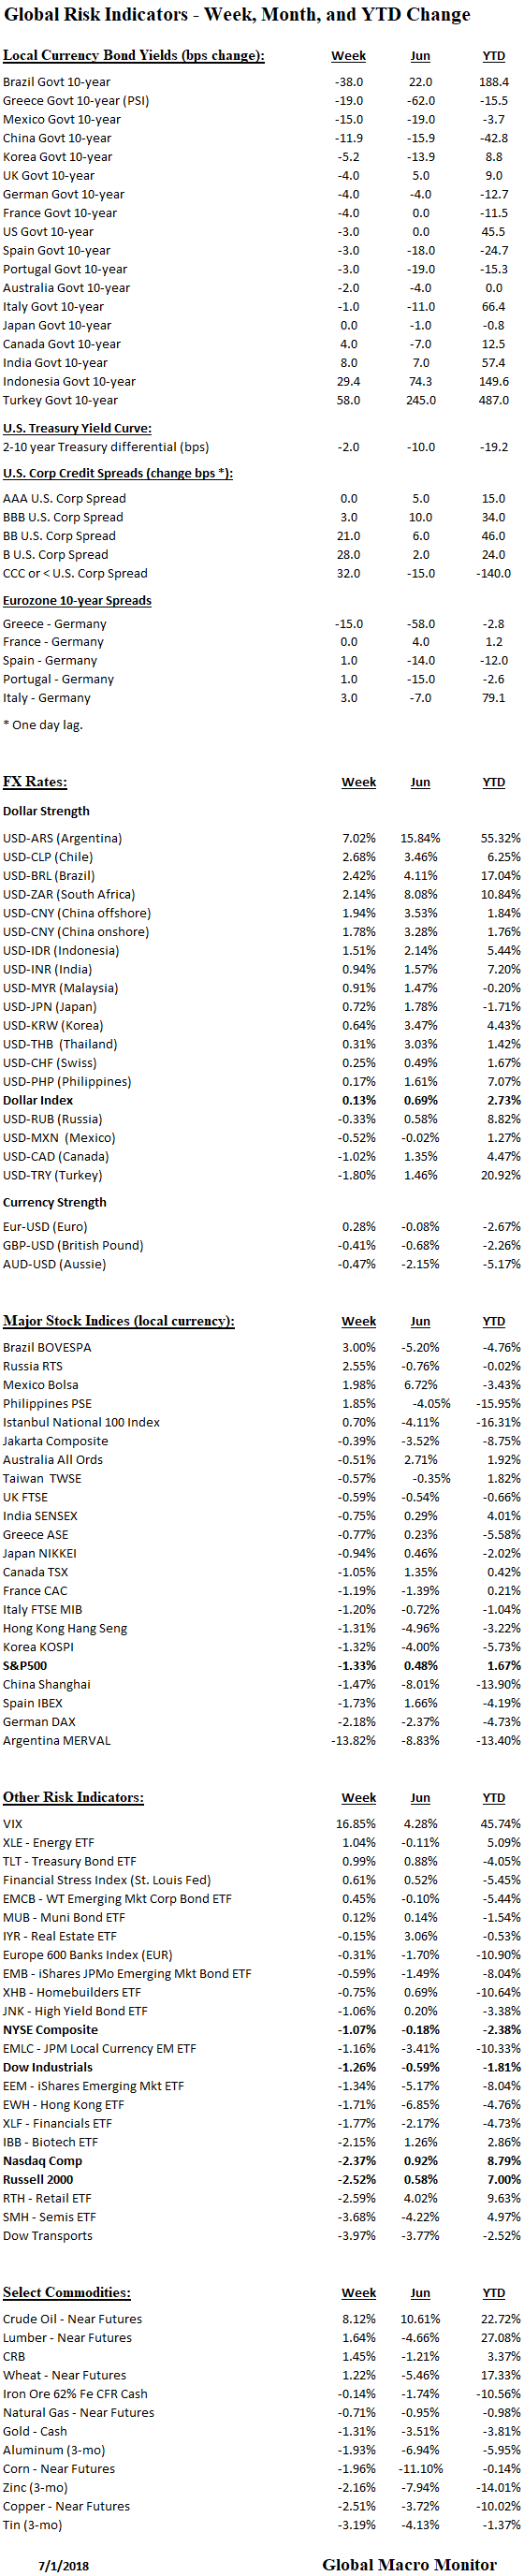
Risk markets finally starting to take the trade wars serious as S&P breaks through key support levels.
European periphery relatively quiet though banks continue to wilt. Deutsche Bank traded with an eight handle today. WATCH THIS SPACE!
LatAm EM weaker. China’s RMB continues to weaken and now down almost 5 percent since May.
Big reversal in U.S. stocks today.
The S&P broke key support trading through the 50 and 100-day moving average and the .50 Fibonacci retracement level to close slightly below 2700. Next stop is the 200-day moving average at 2689.19 and the swing low at 2689.19. If these levels don’t hold, look out below, and they are only a chip shot away.
As we noted yesterday,
Flash: Peter Navarro is out on CNBC as we write trying to calm the markets. Don’t you think our trading partners see this, that the administration fears a market downturn, and can play hardball until the U.S. caves? Let the game(s) theory begin! – GMM
As futures weakened overnight, like clockwork, Secretary Mnuchin emerges from exile softening the administration’s tough stance on trade. That will be taken as a signal of weakness by our trading partners, in our opinion, who can now toughen up their negotiating position as they perceive the U.S. can’t even take the pain of a 5 percent stock market correction.
Larry Kudlow later threw cold water all over Mnuchin’s statement. Keystone Cops policy making.
Asset Driven Economy
In an asset driven economy, a falling stock market has an outsize impact on the economy and puts the Trump Made America Great meme at risk.
In fact, today’s U.S. concession makes the administration look weak and the negotiations more intractable. President Trump will likely swing back to a harder line as he realizes this.
President Xi, Justin, Enrique, Angela, and eMac can sit back and let every tick down in the S&P extract concessions from the Trump administration.
As we have stated in earlier posts,
..we don’t believe President Trump is a free trader at heart but more of a protectionist and neo-mercantilist. There is no “Art of the Deal” – see his waffling on immigration – and no method to the administration ’s madness to negotiating anything, for that matter, but only driven by impulse and myopia. We hope the markets awaken to this reality before it’s too late. – GMM, June 24
The markets are finally getting it.
Stay tuned.




