The FT’s Daniel Garrahan previews the big stories in the week ahead, including Theresa May preparing to give a foreign policy speech after another difficult week for the UK prime minister; Walmart earnings; the fifth round of Nafta talks and GDP data from Japan ► Subscribe to FT.com here: http://bit.ly/2r8RJzM
Context: China’s Americanologists trying to understand President Trump’s North Korea policy :
“There is a major debate in the US right now about whether the US president is really a risk taker or just playing a risk taker,” said Mr Harold. “They are having the same debate in China too.” – Scott Harold, Georgetown University, via FT
(QOTD: Quote of the Day)
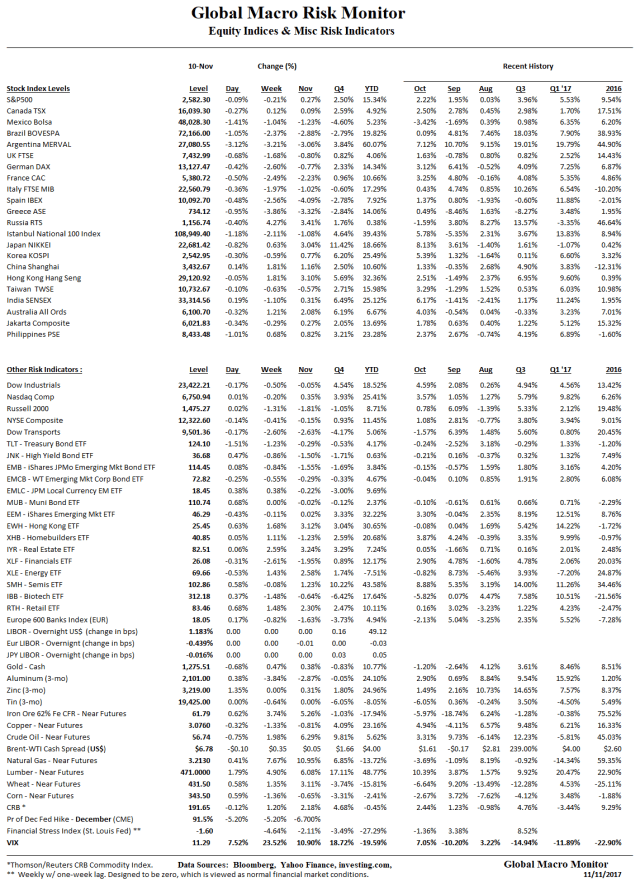
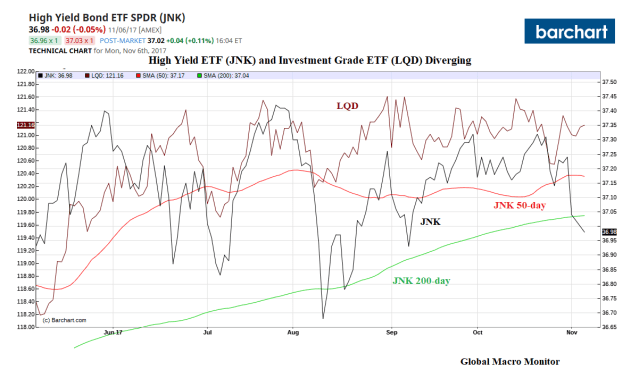
Take a look at the divergence between the high-yield ETF (JNK) and the investment grade ETF (LQD). This makes us a bit nervous – though no panic as JNK in only 1.28 percent off its high vs. the LQD, which is only 0.53 percent off its 52-week high. The LQD trades more closely with the risk-free bond.
Last week we saw a break in the momentum of spread tightening across the board even as the VIX closed at a record low. It seems very difficult to imagine that spreads can come in much further and we think we are very close to the floor.
Makes sense to take some risk off into this year-end rally.
The Dow Transports are selling off as the Industrials are making new highs. That’s a no no in Dow Theory. We pointed out a similar divergence on August 1st.
Not as relevant as it used to be, but something to keep on your radar. Transports approaching 200-day moving average at 9,117.59 (corrected on Aug. 19) and diverging from Industrials. — GMM, August 1
The divergence signaled the 2 percent correction in the Dow Jones Industrials, which began on August 7th. Note also the Transports 50-day moving average is just 0.25 percent lower.
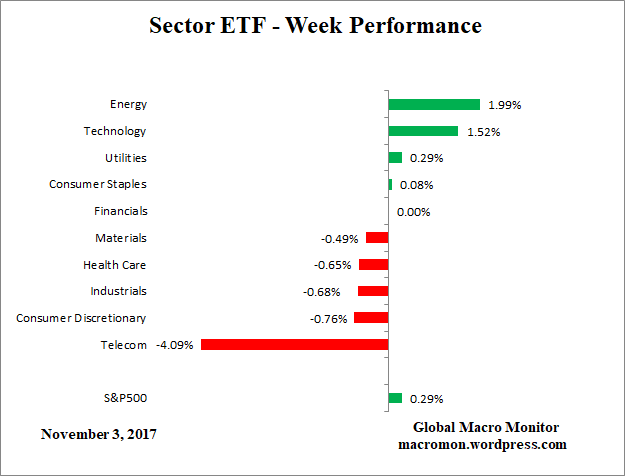
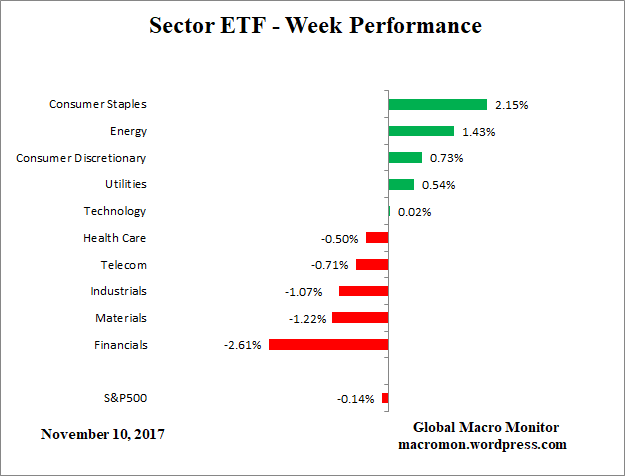
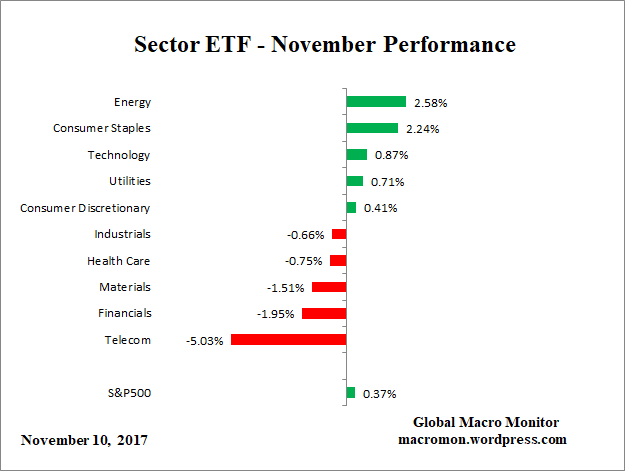
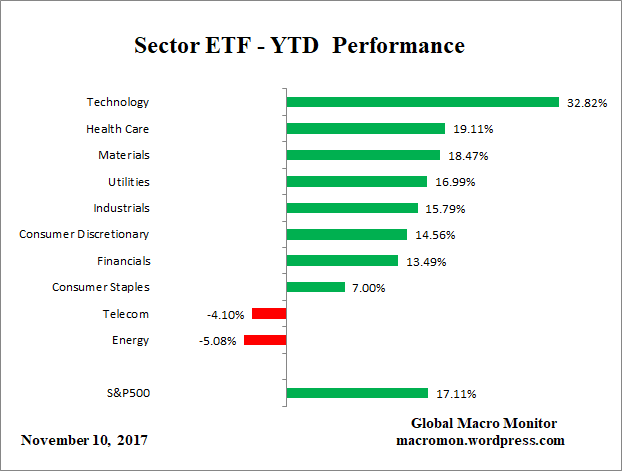
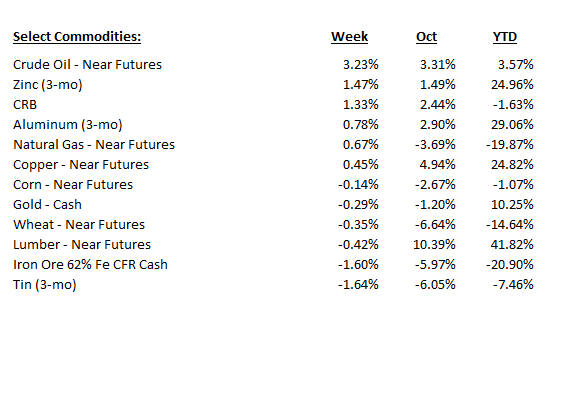
Looks like the market going to hand it off to energy sector into year-end. In a normal market, Transports sell with rising energy. Crude oil closed over $57 p/bbl today.

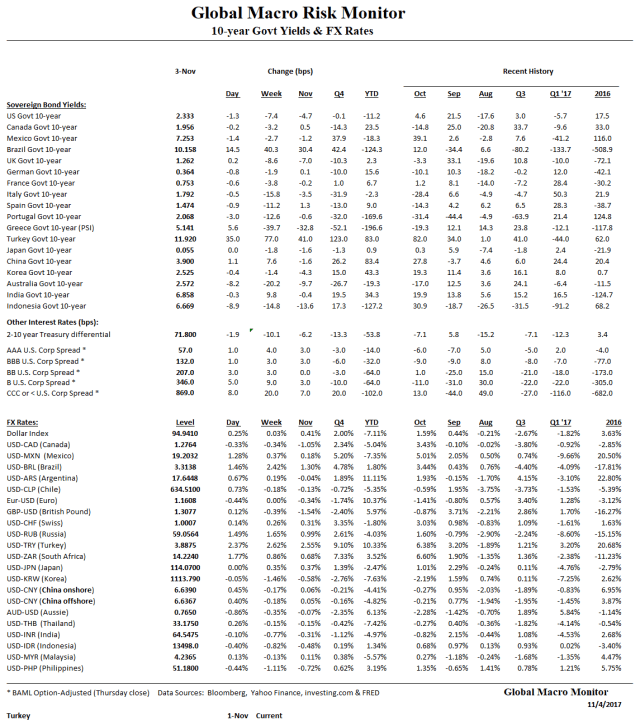
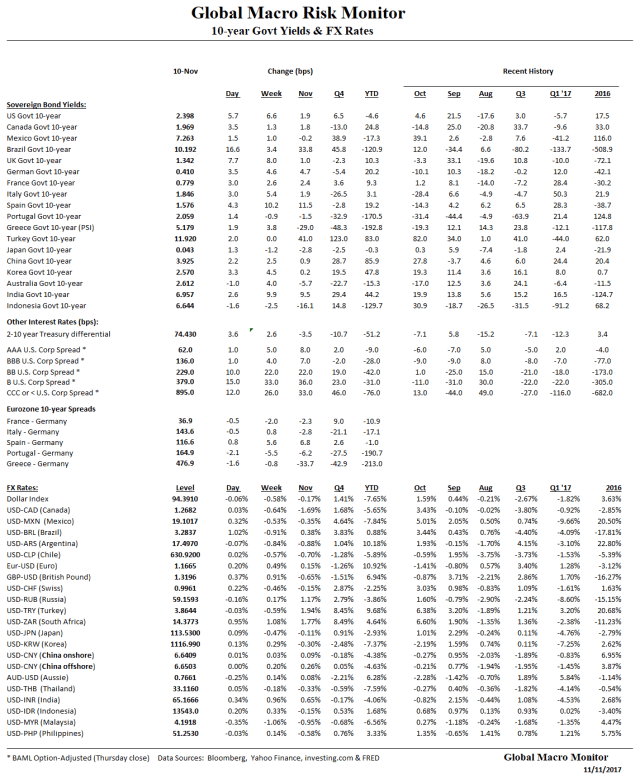
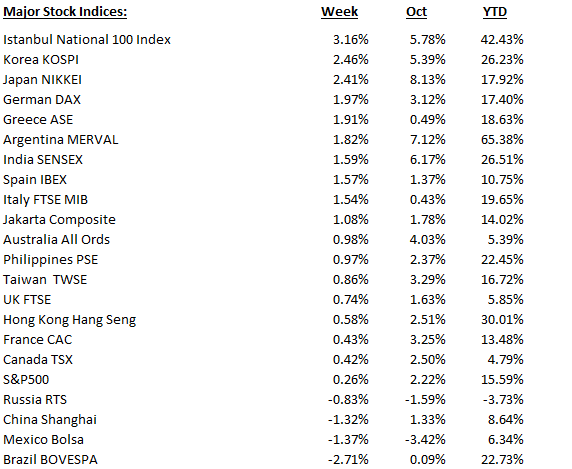
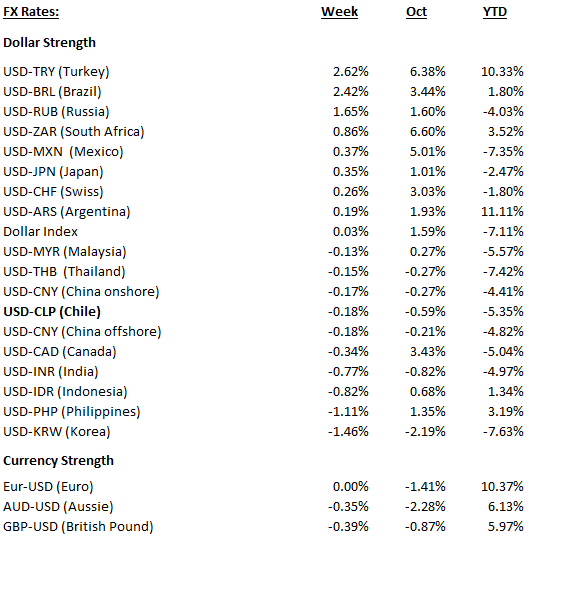
Turkey up Monday through Thursday but gave some back on bad inflation print Friday morning, which took the country’s 10-year rate up and currency down, bigly. Turkey is one of the largest emerging markts. Watch this country.
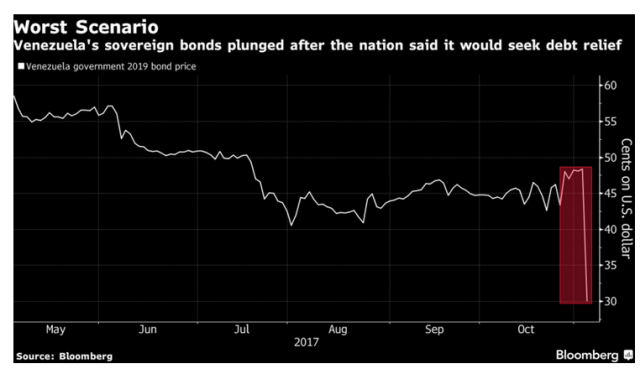
Neverthless, most equity markets enjoying what they percieve as the Goldilocks global economy with synchronized economic expansion and low inflation. Latins hit on currencies and probably Venuzuela’s announcement of a global debt moratorium on Thursday night, though somewhat ambigous, probably caused some risk aversion in the region.
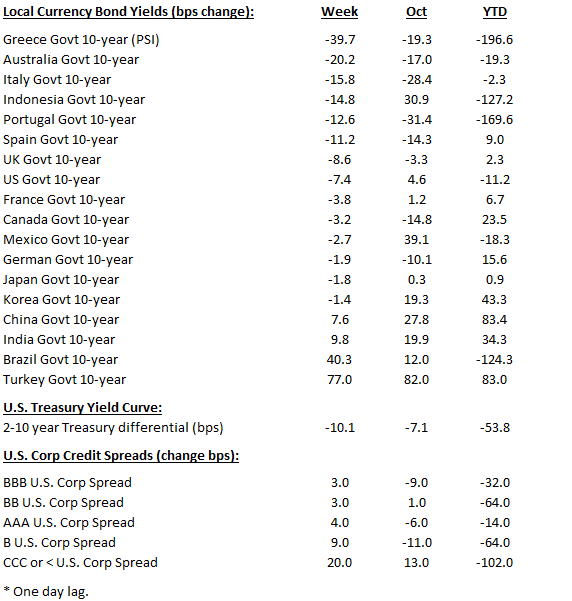
Euro periphery coming in as markets continue to digest Mario Draghi’s dovish taper from October 26th. Turkey yields up big on bad inflation print. Brazil one of the high yielders also up big on the week. Watch these bonds.
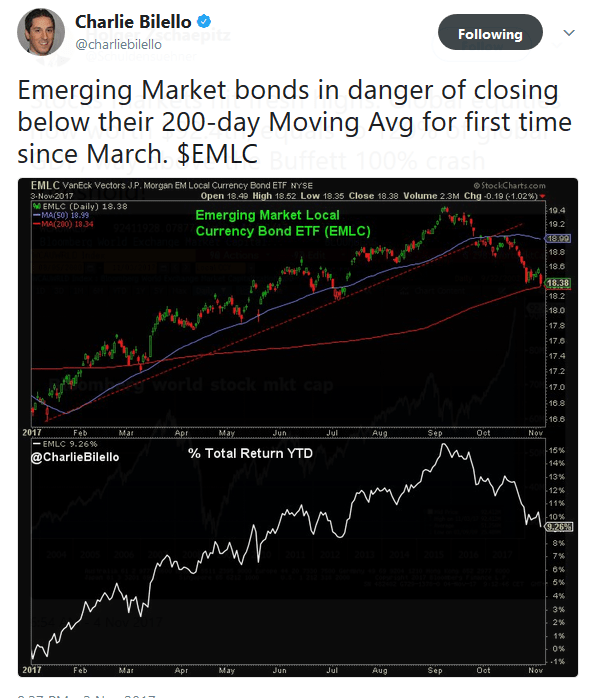
Turkish lira down big against dollar on the week on bad inflation print Friday morning. Most EM currencies hit on Friday with combo of Turkey sell off and Venezuela default. We had thought lira was a short-term buy after the sell-off in October. EM currencies totally unlinked from EM credit. (see chart below)
Crude continues rally and got some legs after rig count decline on Friday morning. The political purge in Saudi over the weekend may provide some further support and upside. Lumber gave a little back after the big upside in October.
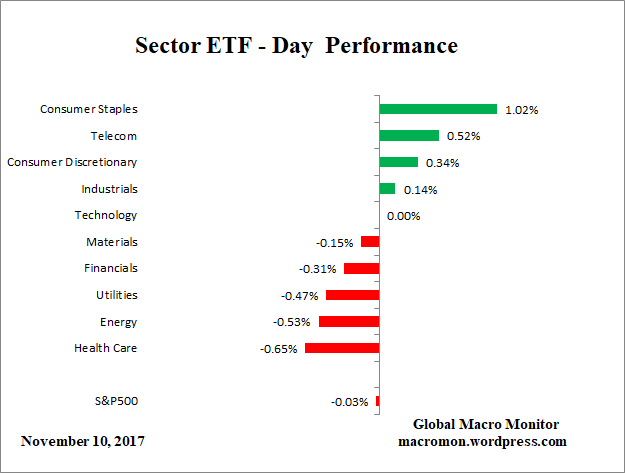
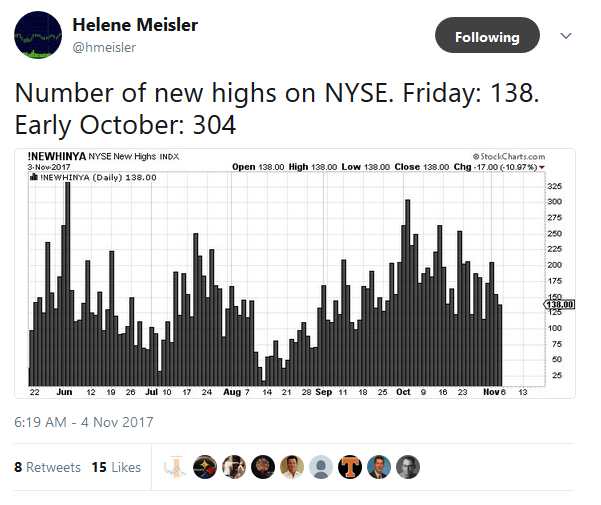
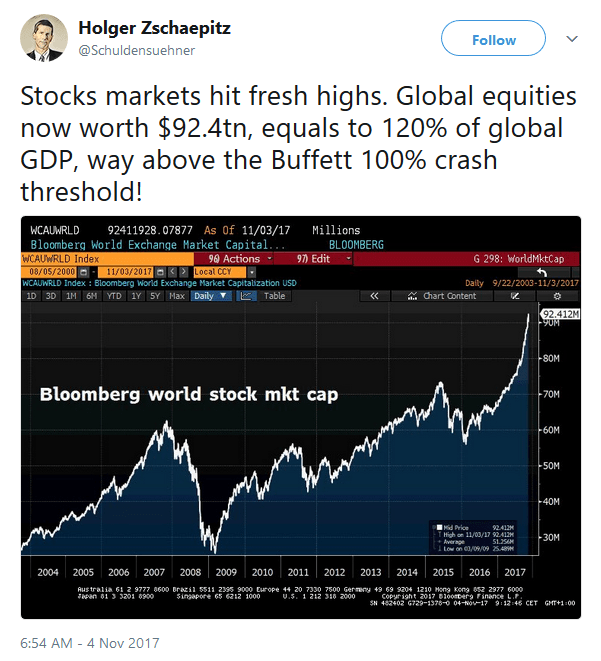
Semis still in beast mode and seem overbought to us. U.S. stock market advance becoming more narrow and showing signs of exhausation. Note NYSE composite index lagging and high-yield selling off. VIX closed at record low on Friday.
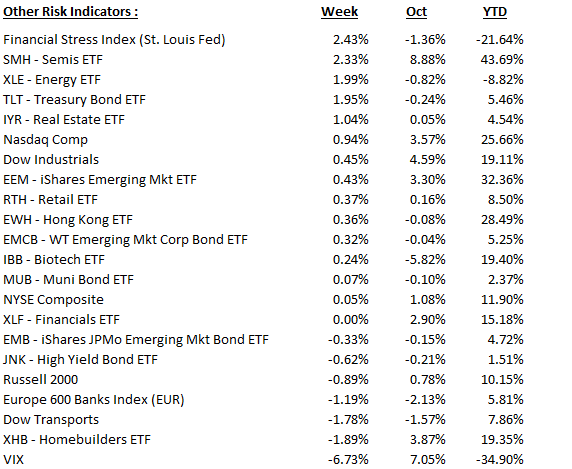
We are quite surprised at EM currency continues to sell and makes us begin to reaccess our view that the most global markets will remain bid or move sideways until risk-free and policy rates begin to move 100-200 bps higher. The weakness in EM and credit seems to be idiosyncratic to those particular markets and may be signaling something bigger on the horizon, or maybe not. Keep these markets are your radar.
We have been looking for a correction this fall and expected one on the back of European bond market taper tantrum in October. Never materialized.
This week will be big for emerging markets and high-yield as they have started to wobble. Watch this space.


“..liquidity is OK. But it may be more fragile, and more prone to disappearing in stress situations…There hasn’t been a liquidity-related incident that has had a significant effect on the real economy. That doesn’t mean it won’t happen.”
– Jay Powell, Fed Chair designate