Getting Back Pre-COVID GDP Levels

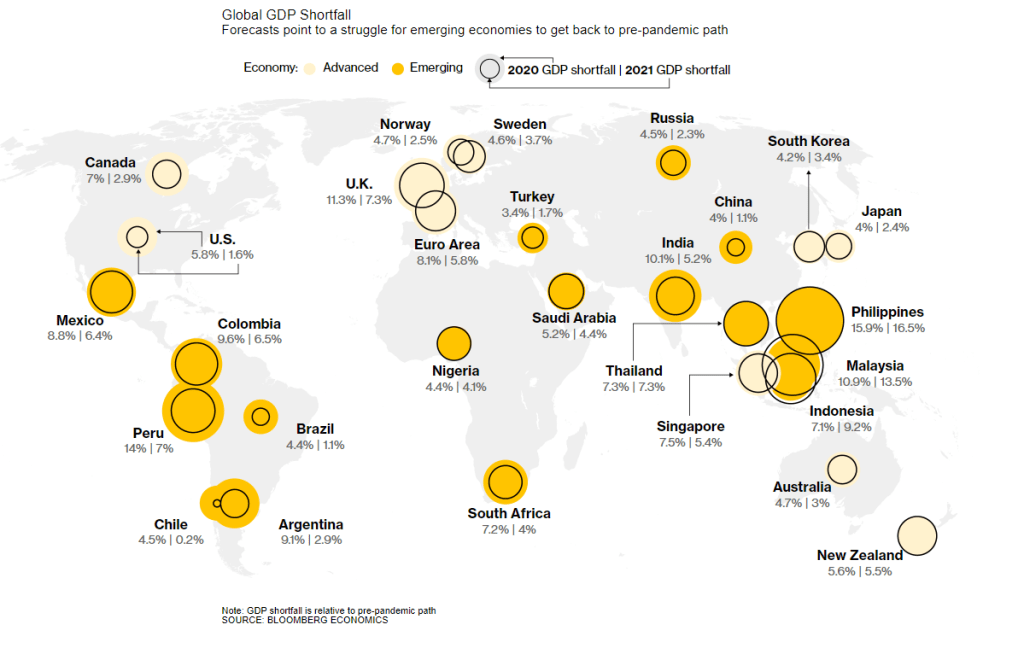
Nice chart from Bloomberg. Chile’s almost there, baby! h/t CK

The U.S. may be.

If Q1 GDP grew at an annualized compounded rate of 10.2 percent (2.45 percent q/q), the U.S. economy will back to its pre-COVID end of quarter high of $19.254 tillion set in Q4 2019. The U.S. economy probally peaked in mid-February.

The Atlanta Fed’s GDPNow forecast has Q1 GDP growing at 6.2 percent (CAAG). Stay tuned.

Posted in Economics, Emerging Markets | 1 Comment

A Day In The Life Of Tim Cook

Posted in Uncategorized | 2 Comments

You Sure, Georgia?

“Poor Mexico [Georgia Republicans.]  So far from God and so close to the United States [MAGA.]”  ― Porfirio Diaz (paraphrased)

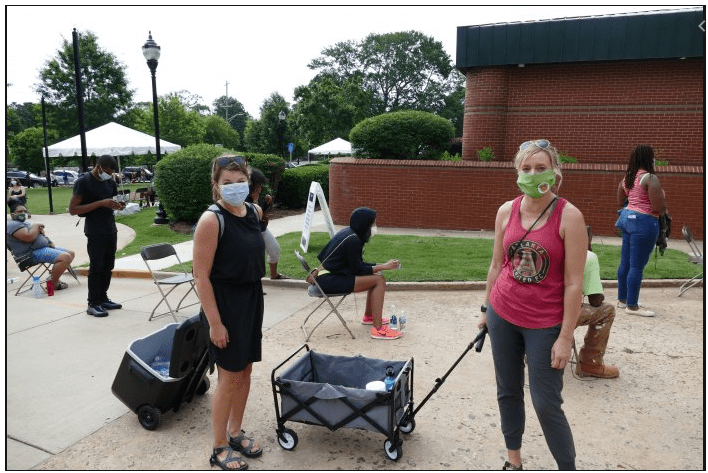
This image has an empty alt attribute; its file name is handing-out-water-in-ga.png

The Georgia law will make it a misdemeanor crime to give food or drinks to voters waiting in long lines. – Reuters

Gonna get hot, hot, hot for y’all.   

“Then he will say to those on his left, ‘Depart from me, you who are cursed, into the eternal fire prepared for the devil and his angels.  For I was hungry and you gave me nothing to eat, I was thirsty and you gave me nothing to drink,  I was a stranger and you did not invite me in, I needed clothes and you did not clothe me, I was sick and in prison and you did not look after me.’

“They also will answer, ‘Lord, when did we see you hungry or thirsty or a stranger or needing clothes or sick or in prison, and did not help you?’

“He will reply, ‘Truly I tell you, whatever you did not do for one of the least of these, you did not do for me.’

“Then they will go away to eternal punishment, but the righteous to eternal life.” – Gospel of Matthew

No judgement, just logic.  

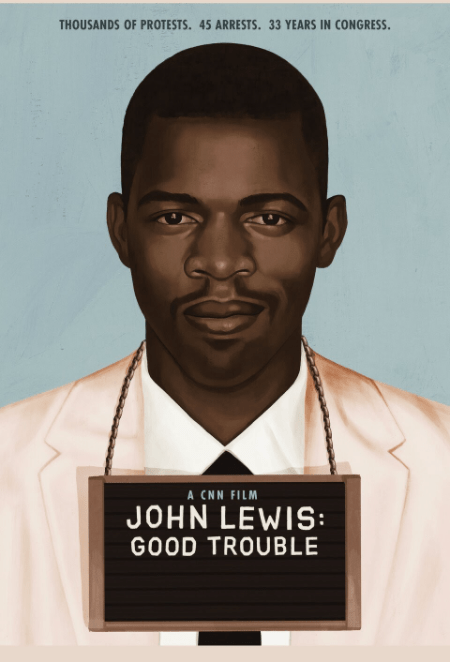
Good Trouble

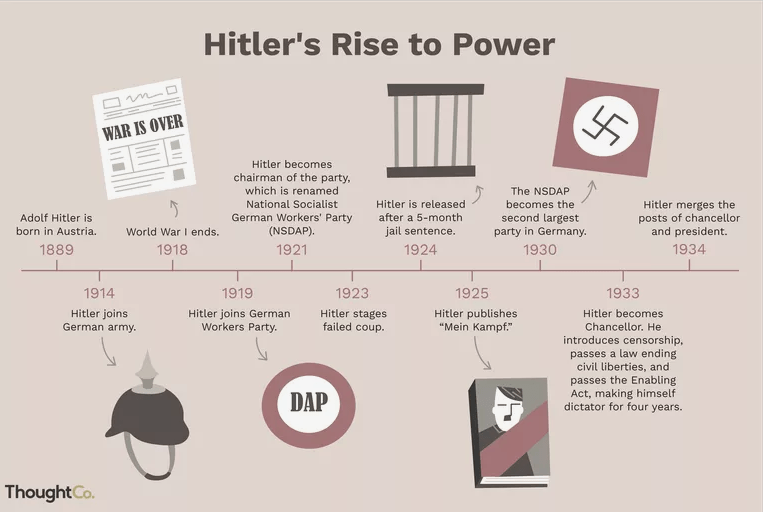
Time for vigilance and to stir up some “Good Trouble,” not only to honor Saint Lewis but to stop a repeat of a timeline similar to the one below.  Because that, folks, is where America is slouching.    


Unjust laws exist: shall we be content to obey them, or shall we endeavor to amend them, and obey them until we have succeeded, or shall we transgress them at once? Men, generally, under such a government as this, think that they ought to wait until they have persuaded the majority to alter them. They think that, if they should resist, the remedy would be worse than the evil. But it is the fault of the government itself that the remedy is worse than the evil. It makes it worse. Why is it not more apt to anticipate and provide for reform? Why does it not cherish its wise minority? Why does it cry and resist before it is hurt? Why does it not encourage its citizens to put out its faults, and do better than it would have them? Why does it always crucify Christ and excommunicate Copernicus and Luther, and pronounce Washington and Franklin rebels?  – Henry David Thoreau, Civil Disobedience

h/t  CK

Eternal Vigilance

Mr. Jefferson, the great apostle of human rights, has told us, that ‘the price of Liberty is eternal vigilance.’  – Communicated,” Richmond Enquirer, December 30, 1834

Posted in Politics, Uncategorized | Tagged , | 1 Comment

What’s The Probability Of This Event?

Incredible video. The Big Unit snares a seagull 20 years ago today.

Take a guess on the empirical probabliity? Let’s do a calcuation based on these assumptions:

  1. Very few other occurances of a picther nailing a bird. Let’s assume three in post-War era;
  2. Average pitches per game equal 200 per team;
  3. 158 games per year for each team. MLB season expanded to 162 games from 154 games in 1962;
  4. Average number of teams equal 25. Major league baseball currently has 30 teams, compared to 16 in 1960,
  5. Seventy years of data

And the probability is…..


0.00017168%

Passive Investment

I would invest — yes, investment given today’s market madness and new definitions as most trades are now prop bets — $2430 each year ($1 per game) to takedown the $582k payoff. Robinhooders may pay much, much more.

The trade is even tastier if it could be done with options to get the leverage.

Gotta be carefull of your counter-party has the capital to make good on the trade, however.

Get on it Vegas or Draft Kings (DKNG, up 481 percent over last year, btw). You think Steve Cohen, the new owner of the Mets, will begin making a market?

The theoretical probabilty of such an event? Call a physicist, that’s way beyond my pay grade.

Posted in Uncategorized | Leave a comment

The Largest U.S. Cities by Population from 1790 to 2020

Interesting graphic.  Watch Detroit and L.A.’s sharp ascent starting in the 1920s, which illustrates the auto industry’s outsize impact on the urban demographics.   Also, San Francisco’s ascent during/after the Gold Rush in the 1850s.

Posted in Demographics | Tagged | Leave a comment

How AI Will Entertain Us

Must view videos, folks.  Stunningly entertaining.

Posted in AI, Uncategorized | Leave a comment

Happy St. Patrick’s (Maweyn Succat) Day!

Blast From The Past (BFTP).

Originally Posted On 

Happy St. Patrick’s (Maweyn Succat) Day!

St. Patrick, Ireland, St. Patrick’s Day. Simple, right? The man wasn’t even Irish! He was actually born in Britain around the turn of the 4th century. At 16 years old, Irish raiders captured him in the midst of an attack on his family’s estate. The raiders then took him to Ireland and held him captive for six years. After escaping, he went back to England for religious training and was sent back to Ireland many years later as a missionary. St. Patrick was actually born Maewyn Succat, according to legend; he changed his name to Patricius, or Patrick, which derives from the Latin term for “father figure,” when he became a priest.  – Time

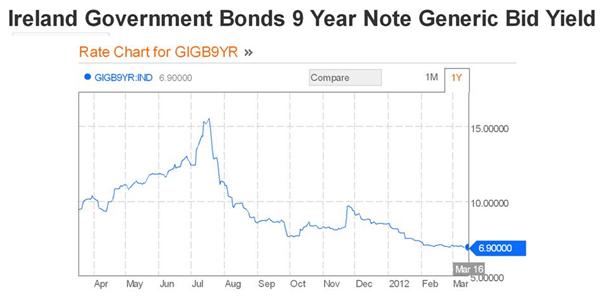
The Irish Comeback

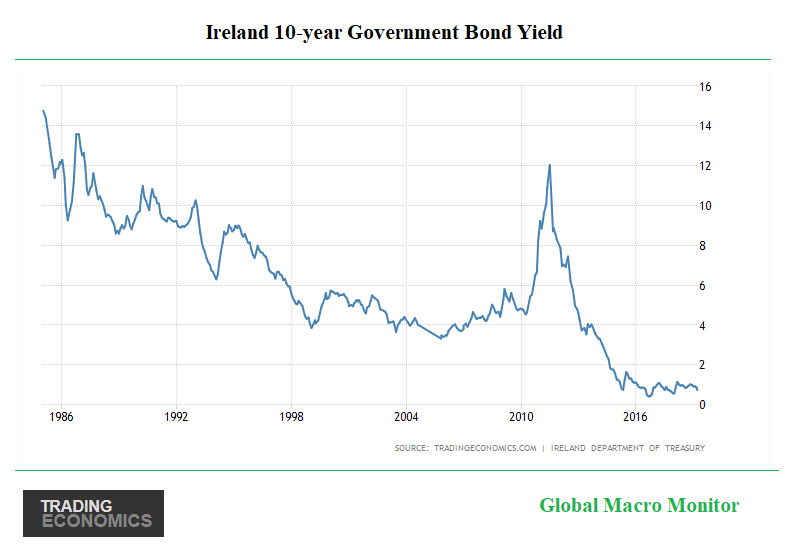
Ireland has come a long way since this post, which was just after the European debt crisis.  The government just placed €1.03 billion of 10-year bonds in mid-February at a stunning yield of 0.85 percent.  The auction had a bid-to-cover of 2.24.

Yeah, got it, distorted due to ECB asset-buying program.  But still well below the Euro periphery bond yields.

Irealand

Though the Irish economy is slowing and there is much uncertainty around Brexit, still it’s been one helluva comeback,  and the Irish are a resilient bunch, now positioning themselves with U.S. and Canadian companies as the “only English-speaking common-law country in the whole of the European Union.”

Me “finks [sic]” part of the success was thumbing their nose and ignoring the advice and dictates of the Eurocrats in Brussels.

Plus, Ireland still has Bono and U2, Andrea and the rest of the Corrs, and the many, if not all the great people of Ireland, we love so much,  including my late grandmother and her side of the family.   That is the upside of being an American.  We are all mutts and can claim to be citizens of many cultures.  Don’t think POUTS has got the memo quite yet.

Rory

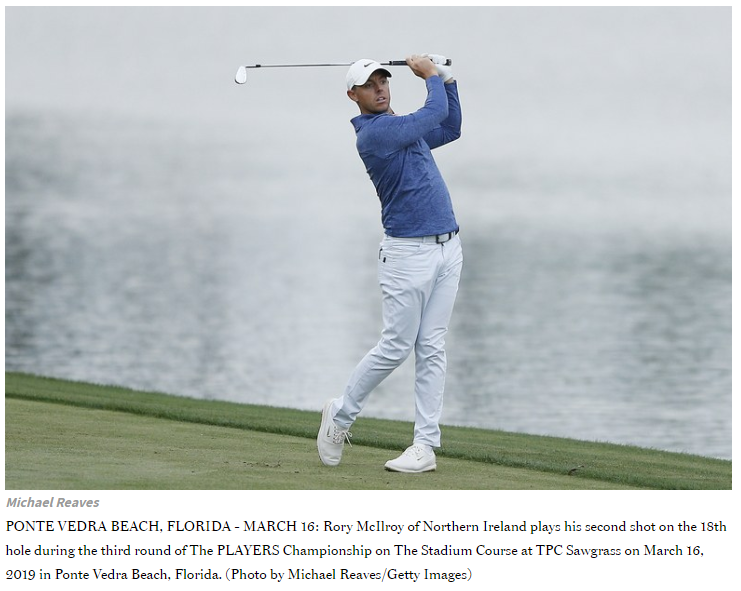
How great would be to see an Irishman win the PGA’s coveted Players Championship on St. Paddy’s Day?   Rory tees it up in today’s final round one back.

Getting long Rory as I write.  Pour me one in Dublin and Hollywood, CD in the wee hours tomorrow to celebrate!   You heard it here first.  Unleash the Leprechauns!

Rory

Source:  Golf Digest

Happy St. Patrick’s (Maweyn Succat) Day!

Originally Posted on 

In case you’re wondering,  Maweyn Succat was St. Patrick’s real name and he wasn’t even Irish!.   Click here for some great background and history of St. Patrick’s Day.

Go Paddy, Rory, Graeme, and Darren!

Happy St. Patrick’s Day!  Not too many green beers, folks!

By the way, there has been one huge bond rally in Ireland over the past year.

Posted in Bonds, General Interest, Picture of the Day, PIIGS | Tagged , , , , , , | 1 Comment

The Macro Factors Driving The Covid Economy In Two Charts

Here’s a couple of interesting and surprising charts, which explain what has been driving the COVID economy and why the U.S. economy is set up for monster growth over the next few quarters.

When the economy fully reopens, we suspect a consumer feeding frenzy in many of the services that have been closed or operating at a limited capacity.   We also expect these firms and businesses that have survived will have mucho pricing power given the massive stimulus that has been put into the economy and the forced savings thrust on those whose incomes have not been affected.

Moreover,  capacity in the service sector has been significantly reduced with many businesses forced to close (see chart below).

Personal Income (PI)

Personal income,  which consists mainly of wages and salaries, rental and investment income, and government transfer payments, such as the latest COVID stimulus payments, is growing at its fastest pace in nearly 40 years.   Some context, however, the 12 plus percent PI growth in the early 1980s took place with CPI inflation running at 10-15 percent year-on-year.

Wages and salaries have not been the driver of PI over the past year but the massive increase in transfer payments.  And “transfer payments” is really a misnomer as much of it has been monetized by the Fed’s digital printing press.

Clearly, this situation is not sustainable and it is uncertain what the economy will look like in the second half of 2022.

Shift In Personal Expenditures 

The following chart illustrates the unexpected shift in consumer expenditures from services, which made up around 70 percent of personal expenditures before the pandemic.  The reallocation of spending to durable goods is contributing to the supply chain difficulties and shortages in industries, such as semiconductors and global shipping.

Many firms, such as the auto industry, settled in for a typical recession after the economic lights were turned off last February, reduced inventories of materials and supplies , and were caught with their pants down when the demand came storming back a few months later.

Inflation:  Temporary or Permanent Acceleration?

Nobody really knows but if the market determines the monetization of transfer payments becomes a more permanent reality,  inflationary expectations will likely take off and the economy will experience a major regime shift from lowflation/disinflation to…..?

Posted in Disinflaton, Inflation/Deflation | Tagged , , | 18 Comments

Why This QE Is Different In One Chart

Robin Hood traders don’t bother reading.

The latest round of central bank balance sheet expansion, which will reaccelerate soon as Biden’s COVID bill is passed, needs some context.

By the way, we did some rough approximations late last night and found the Fed has taken down about 35 percent of the new issuance of Treasury notes and bonds since the end of 1Q20.  As the US Gs deficit exploded again, the Fed had to effectively monetize a big part to keep the Treasury adequately funded without a huge spike in interest rates.

Today’s ugly 7-year Treasury note auction may be a signal that percentage may rise unless rates are allowed to move much higher to entice buyers.

QEs of Christmas Past

Many believed that the last QEs should have led to inflation because the “money supply” would explode.  Too much money in the system leads to dishording the excess money balances and eventually finds itself in the market for goods and services.

First, the problem is defining money. Economists can’t even agree on what constitutes money.  We are hearing echoes of the debate over Bitcoin as a viable alternative currency.

Endogenous Money

There is also “endogenous money”  created by the financial system through the expansion of credit.   During QEs past, endogenous money was either shrinking or barely growing due to an impaired financial system and a banking sector in the process of healing from the Great Financial Crisis (GFC).

Endogenous money is an economy’s supply of money that is determined endogenously—that is, as a result of the interactions of other economic variables, rather than exogenously (autonomously) by an external authority such as a central bank. – Wikipedia

The Fed’s digital printing press was essentially offsetting the collapse in endogenous money as sort of a zero-sum game.  Much of Fed’s money often referred to as “high powered” money as it can be converted into a multiple of endogenous money was locked up at the FED as banks earned interest on the excess reserves.

The interest rate on excess reserves held at the Fed is now 10 bps.

Lot’s of high-powered money now in the system earning 10 bps.

Current Environment

The Fed deserves some kudos for not letting the financial system collapse during the early days of COVID but the risk of much higher inflation is now at hand.   There is just too much money created by the Fed and the credit markets chasing too few assets, goods, services, and, yes,  semiconductors.

Can the Fed continue to rescue the stock market in this environment?  Have they cornered themselves in?

We don’t know, nor does anyone else but a lot of people have put on mucho risk betting they will.

Stay tuned.

Posted in Monetary Policy | Tagged | 3 Comments

Global Fixed-Income Market

US Fixed Income Markets vs. Rest of World
The U.S. fixed income markets are the largest in the world, comprising 40.0% of the $114 trillion securities outstanding across the globe, or $46 trillion (as of 2Q20). This is 2.0x the next largest market, the EU. U.S. market share has averaged 38.6% over the last 10 years, troughing at 36.3% in 2011 and peaking at 40.9% in 2015. – sifma

Posted in Bonds | Tagged | Leave a comment