QOTD = Quote of the Day
A currency is only as good as the government that backs it. – Economist
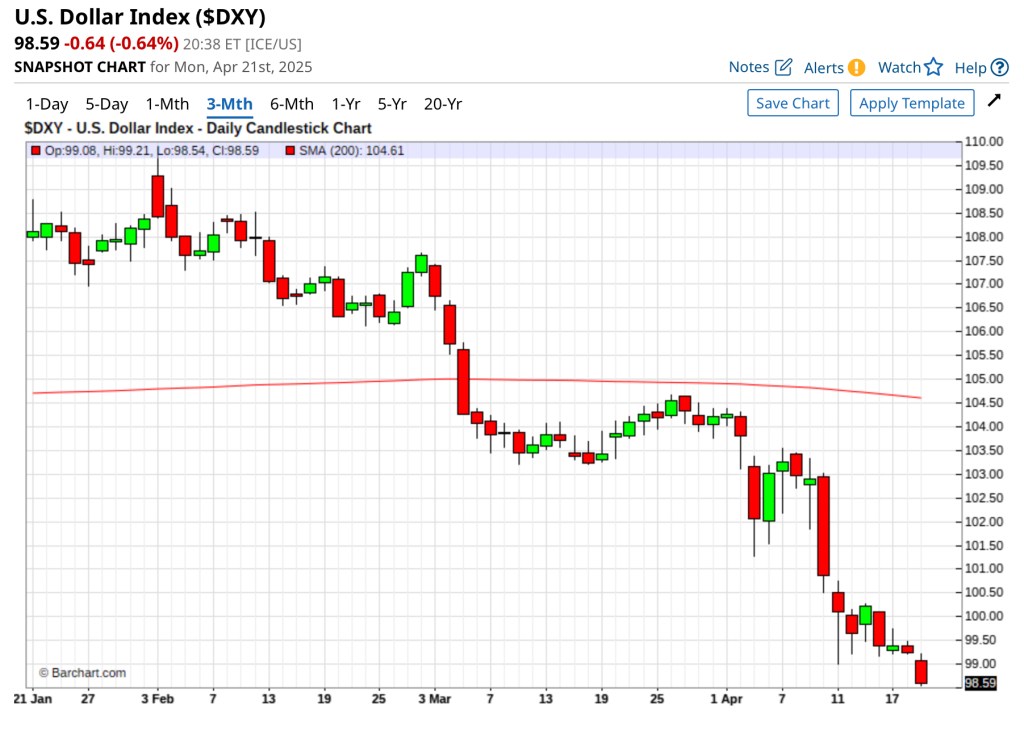
Chart Source: Barchart.com
QOTD = Quote of the Day
A currency is only as good as the government that backs it. – Economist
Chart Source: Barchart.com
As the single largest player in the ecommerce industry, Amazon generates between 10% and 15% of global online sales. In its home market, the US ecommerce giant makes up to 40% of total ecommerce sales and generates the highest revenue in three out of four major product categories, outperforming competitors by a large margin. But ironically, while Amazon is seen as emblematic of American success in ecommerce, Chinese products are the backbone of its marketplace.
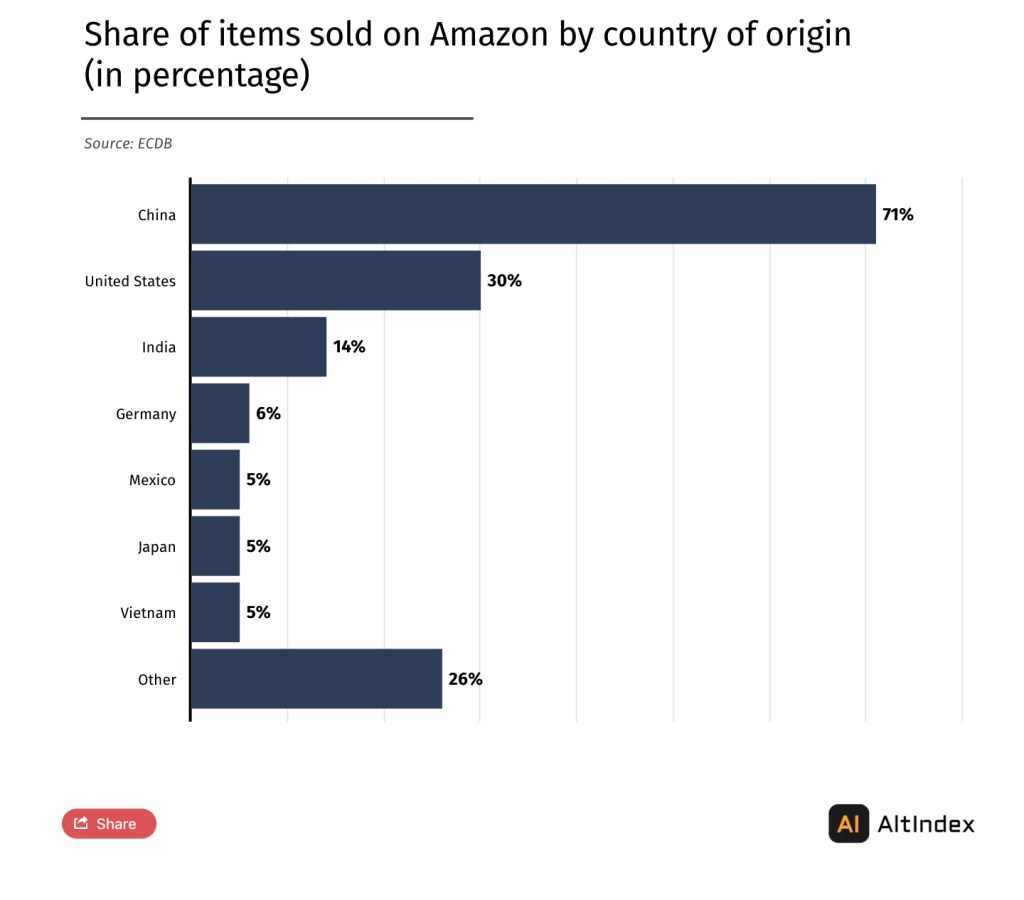
According to data presented by AltIndex.com, more than 70% of all products sold on Amazon are made in China…
Statistics show that 71% of the products that wholesalers and retailers sell on Amazon are produced in China, or 2.4 times more than in the United States, illustrating China’s importance for Amazon’s business. US products have a much smaller share and account for 30% of all total goods sold through the US e-commerce giant, while India stands in third place with a 14% share. – AltIndex
Happy Easter, folks!
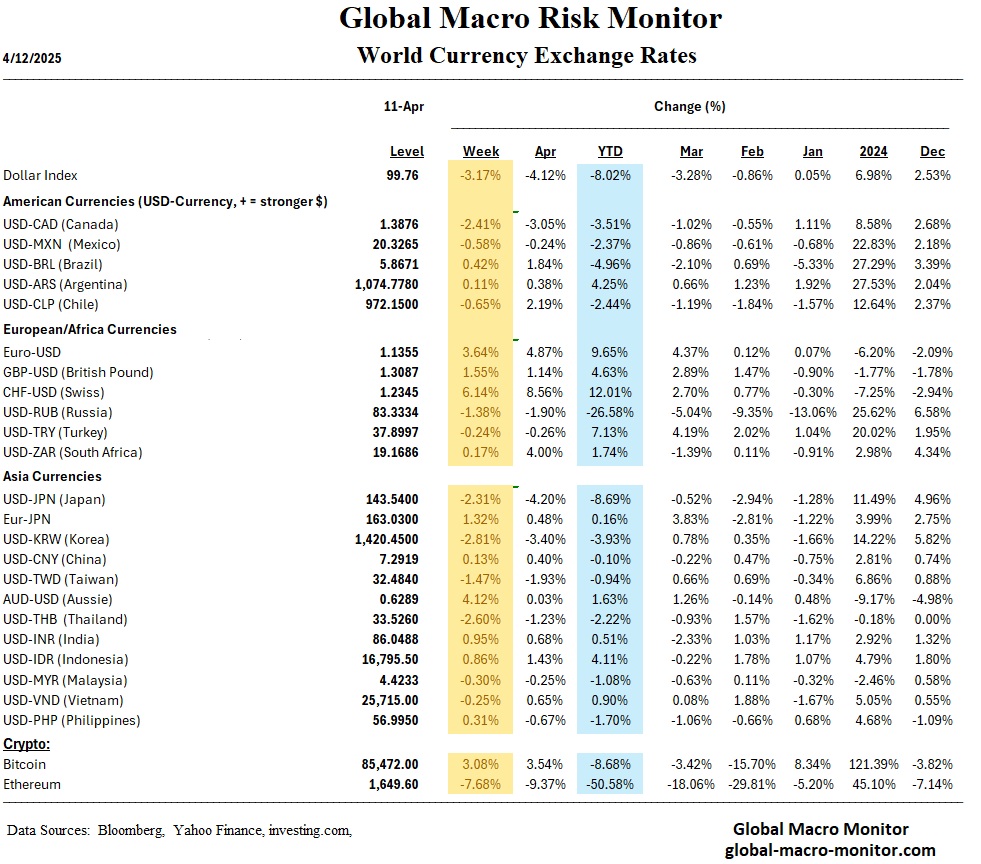
The Trump administration’s tariff strategy continues to function less as a deliberate trade policy and more as a volatile, reactionary experiment. Markets are grappling with a growing realization: there is no unified objective anchoring current U.S. trade actions. Is the administration trying to reshore manufacturing? Raise revenues? Or promote freer and fairer trade? All three goals conflict—and the markets know it. The result has been a weakening dollar, rising gold prices, and diverging capital flows.
This week’s 3% rally in gold, alongside the sixth decline in seven weeks for the U.S. dollar, underscores a broader erosion of investor confidence in the U.S. policy framework. While U.S. bond yields stabilized and credit spreads modestly contracted, the underlying message remains clear: investors are hedging against deeper policy missteps. Until the administration resolves its own internal contradictions, volatility is likely to persist, and global capital will remain in search of clarity elsewhere.
The administration’s approach has produced a confusing cycle: new tariffs imposed, then partially reversed under pressure; sector-specific exemptions offered one week, then threatened again the next. The pause on semiconductor and electronics tariffs has done little to reassure investors given the lack of a consistent framework. Meanwhile, tariff-driven inflation threatens to stall growth just as the Fed tries to preserve monetary flexibility.
Market pressures may eventually force a strategic retreat. But until then, the White House appears more responsive to market headlines than to long-term macroeconomic outcomes. The central lesson of this week: instability is becoming structural.
Markets
U.S. Market Analysis
Global Market Analysis
Economics
U.S. Economic Overview
Global Economic Overview
Week Ahead (April 21–25)
Key U.S. Events:
Key Global Events:

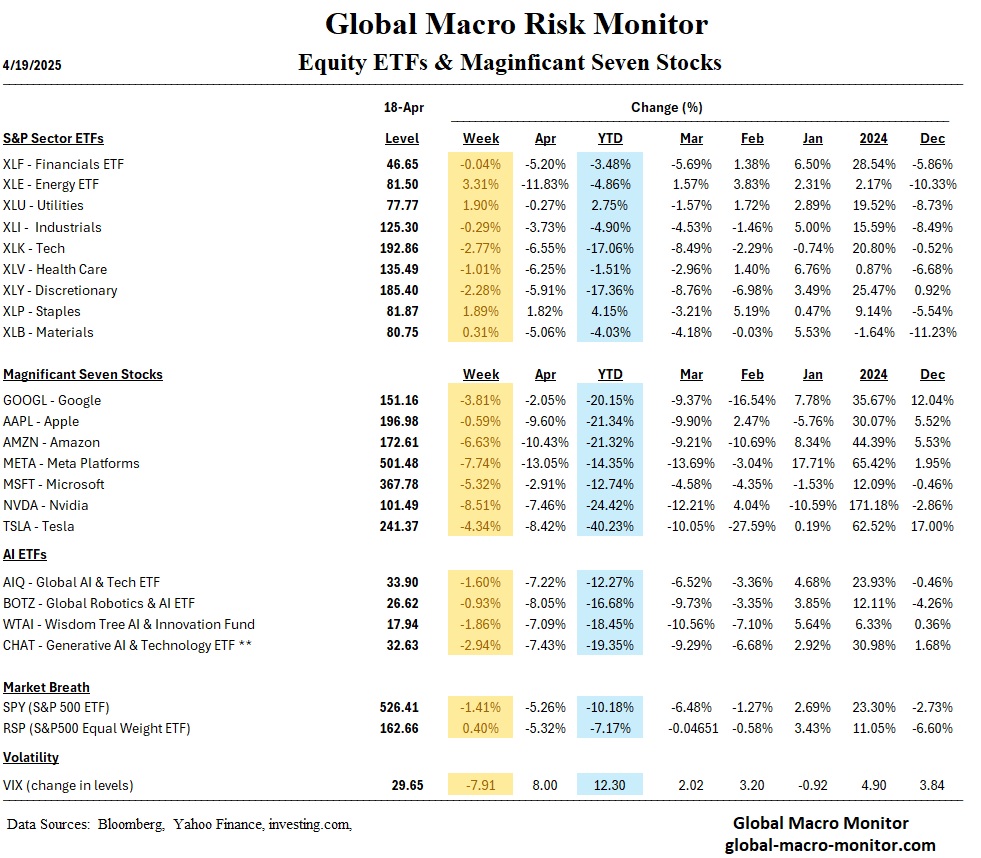


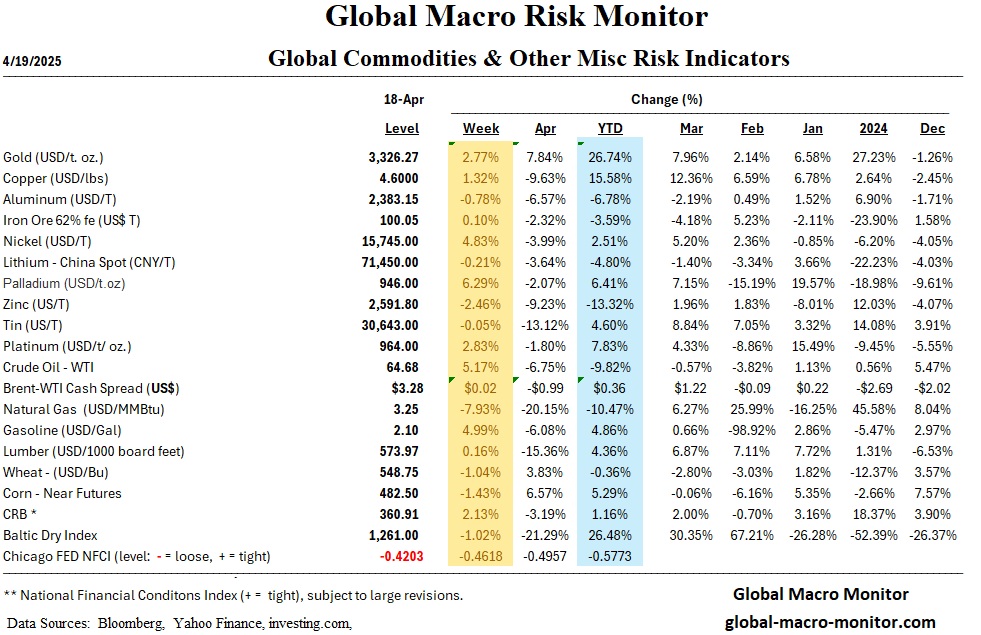
Happy Jackie Robinson Day! What a great American.
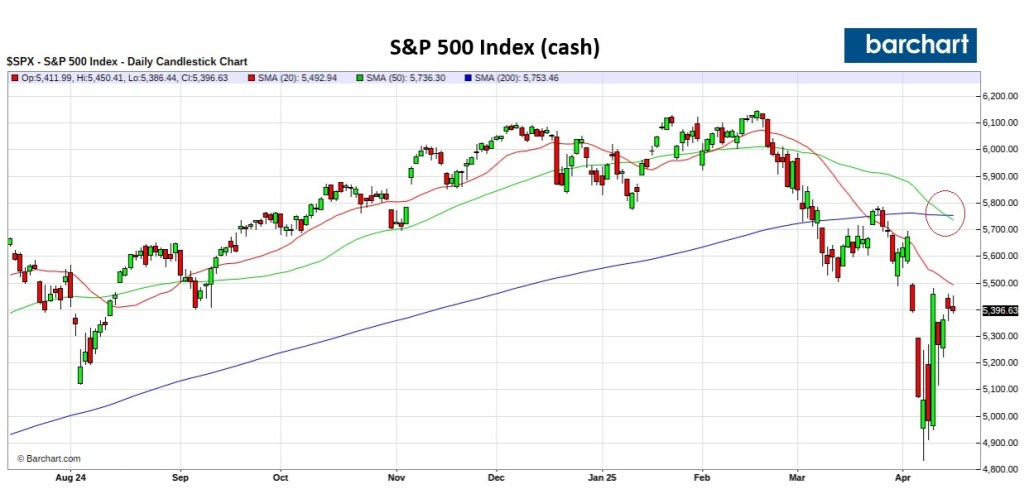
The rebound in the S&P 500 has thus far stalled at a key technical level—specifically the 50% Fibonacci retracement of the current correction from the recent highs, which stands at 5491.24. Today’s intraday high of 5450.41 failed to surpass the April 9th rebound peak of 5481.34, reinforcing the significance of the 5450–5500 zone as a formidable resistance range.
This area marks the midpoint of the decline and is closely watched by institutional players. A sustained break above this level would shift momentum in favor of the bulls; however, until then, it serves as a technical ceiling capping rallies.
From a trading perspective, market conditions have become increasingly erratic, bordering on untradable for directional players. Initiating short positions in this range carries elevated risk, as any unexpected de-escalation in U.S.-China tensions or a surprise tariff relief headline could ignite a sharp short-covering rally. Volatility remains headline-driven, and risk-reward is skewed to binary geopolitical outcomes.
The S&P 500 will likely remain range-bound between 5200 and 5500 in the near term as market participants await more definitive indications of the economic impact stemming from current policy decisions. In our view, as signs of strain begin to emerge—whether through softening macro data, downward earnings revisions, or tightening financial conditions—the index will face renewed selling pressure. This will send the index for a retest of the April 7th low, with an elevated risk it will not hold.
Stay frosty, folks.


BFTP: Blast From The Past

Answer to yesterday’s Masters quiz question:
Anthony Kim posted 11 birdies in the second round of the 2009 Masters.
German WWII POWs
Here’s some more 19th hole fodder to impress your buddies and something I bet you didn’t know about Augusta:
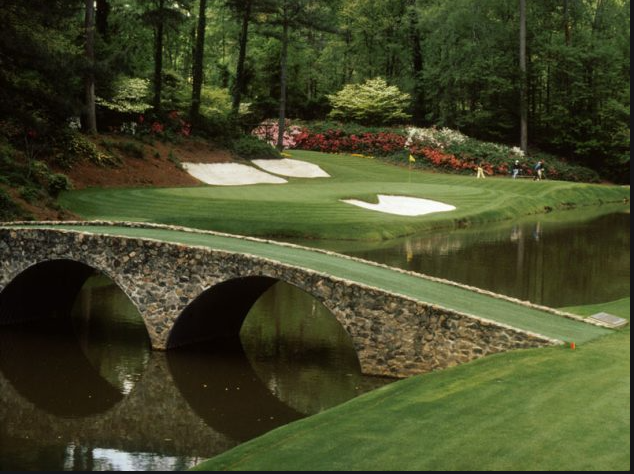
German POWs from nearby Camp Gordon built the bridge over Rae’s Creek next to the 13th tee box during WWII. They were part of Rommel’s Panzer division in North Africa responsible for building bridges to enable tanks to cross rivers.
While Augusta National is famed for its almost unnaturally beautiful flora, as it turns out some rather interesting fauna once called the course home as well: 200 heads of cattle and more than 1,400 turkeys. From 1943 until late 1944, Augusta National was closed for play and transformed into a farm of sorts to help support the war effort. Some of the turkeys were given to club members during Christmas (meat rations were in effect) while the rest were sold to local residents to help fund the club. And the cows? Well, they acted as natural lawnmowers but also inflicted quite a bit of damage to Augusta National, devouring many of the course’s famed plants and shrubs.
To help repair cattle-related damage and revive Augusta National for its reopening, 42 German prisoners of war from nearby Camp Gordon were shuttled back and forth to work on the course.
Writes John Strege in “When War Played Through: Golf During World War II:”
“The POWs had been with the engineering crew serving Rommel, the Desert Fox, in North Africa, part of the Panzer division responsible for building bridges that enabled German tanks to cross rivers. It was a useful skill for the renovation work to be done at Augusta National. The Germans were asked to erect a bridge over Rae’s Creek adjacent to the tee box at the thirteenth hole.”
The Masters resumed at Augusta National — now free of German prisoners and barnyard animals — in 1946. And interestingly enough, the Supreme Commander of the Allied Forces in Europe during World War II, Dwight D. Eisenhower, later became a member of Augusta National. Two Augusta National landmarks bearing Eisenhower’s name still stand today: the Eisenhower Tree (a loblolly pine at the 17th hole that the former president and avid golfer repeatedly struck with golf balls and requested be cut down; photo above) and the Eisenhower Cabin (built in the 1950s according to Secret Service security guidelines by the club for the former president’s visits).
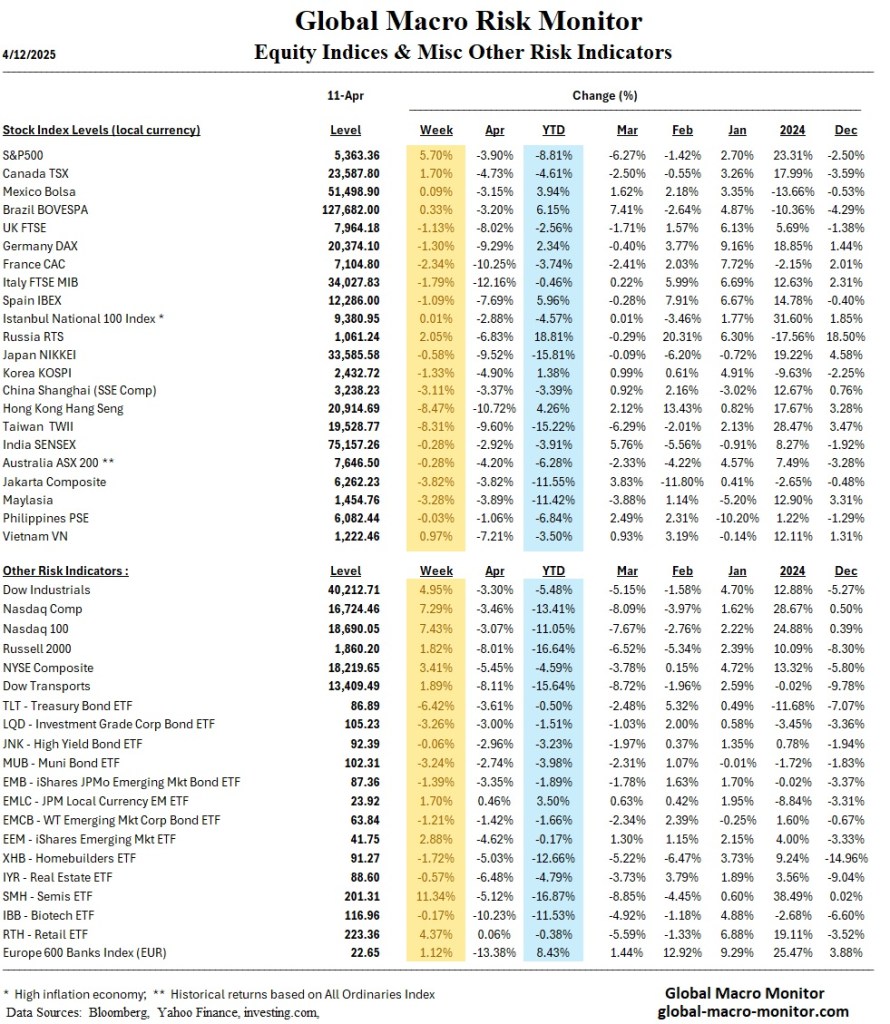
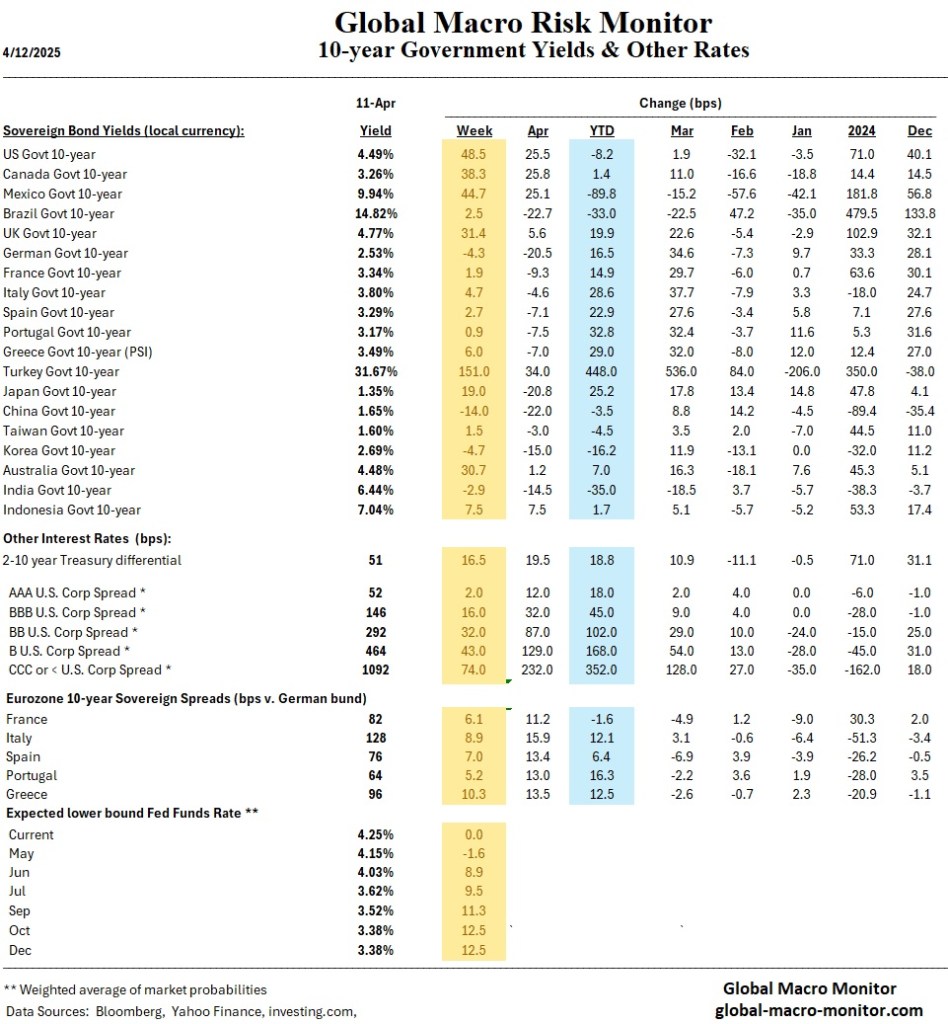
The United States’ current tariff regime reveals not a strategic plan but an erratic response to market volatility, suggesting a governing philosophy resembling reactive day trading more closely than structured economic policymaking. As the week’s developments show, the absence of a coherent framework has amplified financial instability and is now beginning to erode the traditional safe-haven status of U.S. assets. The dramatic 50 basis point surge in U.S. Treasury yields—contrasting with a 4 basis point decline in German bunds and a 6.1% appreciation of the Swiss Franc—signifies an unsettling reality: capital is fleeing the U.S. in patterns more commonly associated with emerging markets in crisis.
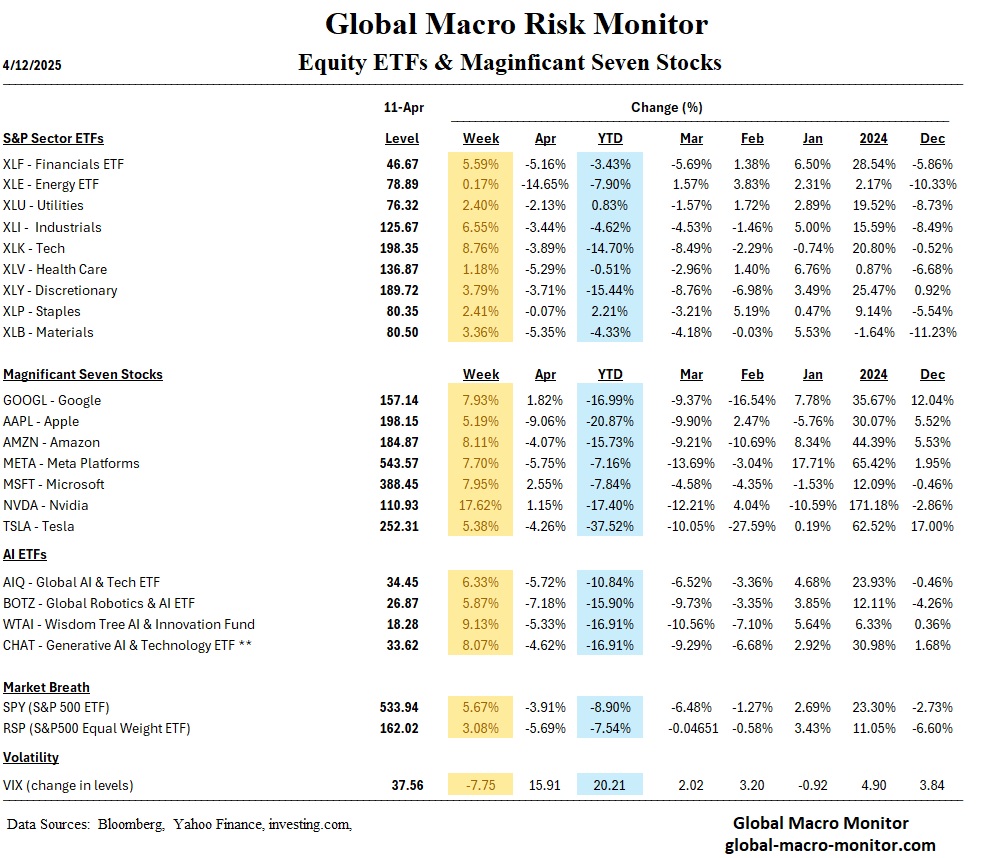
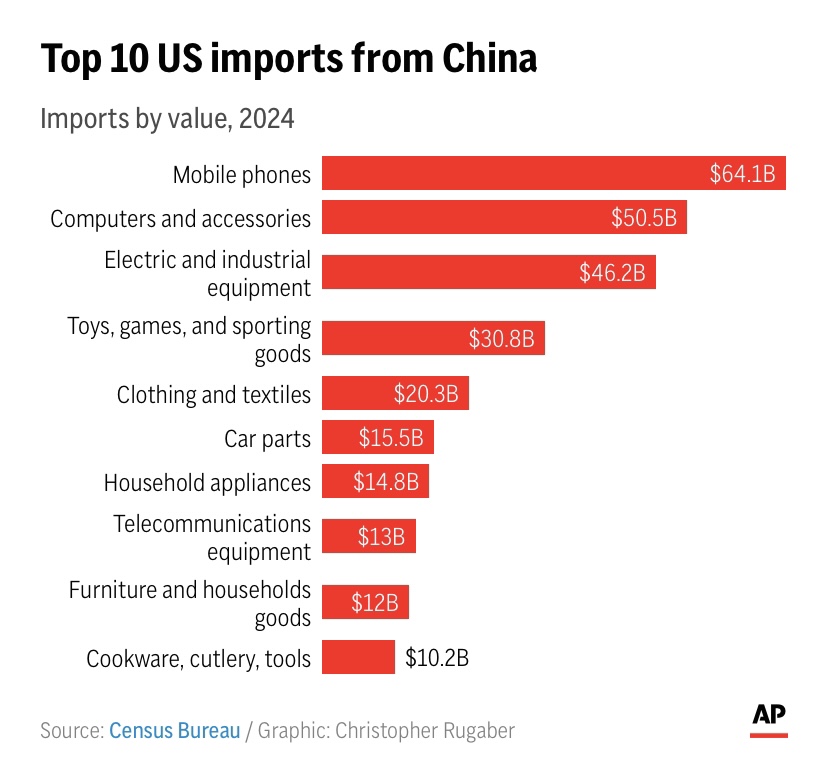
This capital flight reflects growing investor anxiety over both the economic impact and political incoherence of U.S. trade policy. In particular, the decision to impose sweeping and massive tariffs on China —then abruptly exempting $390 billion in consumer electronics, including smartphones and chips —undermines confidence in policy predictability. As revealed in the Friday night tariff exemption announcements, the White House walked back its own levies under intense market pressure, with Apple, Nvidia, and Microsoft among the major beneficiaries. While this move will spark another positive market response early next week, it also reinforces the perception that policy is being dictated by equity indices, not long-term economic goals.
Meanwhile, U.S. credit spreads widened significantly, Treasury market volatility surged, and equities remain fragile despite a mid-week bounce. The broader implication is troubling: without a principled policy reversal, not merely ad hoc relief, U.S. markets may remain hostage to political instability and stagflationary risk. If change comes, it will be driven not by strategy, but by necessity.
Markets
U.S. Market Analysis
Global Market Analysis
Economics
U.S. Economic Overview
Global Economic Overview
Week Ahead (April 14–18, 2025)
Key U.S. Events:
Key Global Events: