What Drives The Trade Deficit?

It’s the national savings-investment imbalance, Stupid!

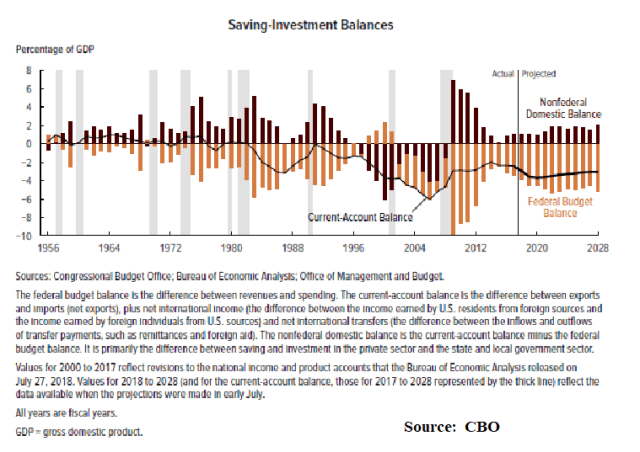
It is explained clearly by the following national income identity, which we have posted several times over the years.

(S-I) + (T-G) = Current Account Balance (Foreign Savings)

 (S-I) is the ‘private savings balance’ or the difference between private sector savings (S) and investment (I); (T-G) is the ‘government balance’ or the difference between tax receipts (T) and all government expenditure (G); (X-M) is the difference between exports (X) and imports (M) and is usually called the simple ‘current account balance’.  – George Irvin

Here is the latest data illustrated by the CBO,

CBO_Savings_Investment Imbalances

Posted in Trade War, Uncategorized | Tagged , | Leave a comment

Double Yikes!!!

I keep hearing the chorus from cheerleaders the market is, “cheap, cheap, cheap,”

https://twitter.com/anthonybsanders/status/1041793576529739776?s=21


Posted in Uncategorized | Leave a comment

QOTD: Complex Adaptive Financial System

….the financial system is complex and hard to understand. It was, in fact, at least partly the growing complexity of the system that got us into such a mess in the first place. – Catherine Rampell, Washington Post

Posted in Uncategorized | 3 Comments

Long-Term Treasury: 4 Percent Or Bust

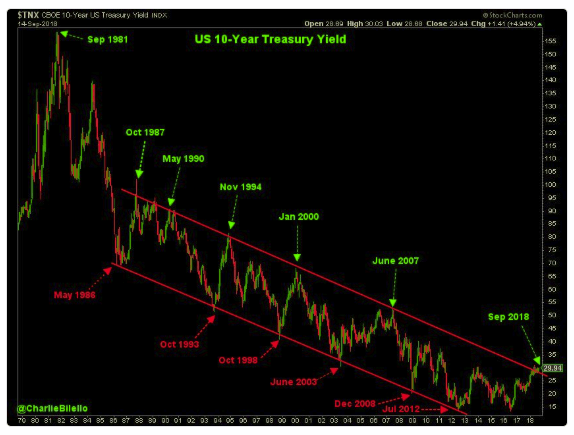
Great chart from Charlie B.   He asked 3.5 or 2.5 percent?

We say beeline to 4 percent, when the rate breaks 3.13 percent, and quicker than the market believes.

It’s been 10 years since Lehman,  nominal GDP is growing close to or over six percent (which, in normal times, the 10-year trades around nominal GDP growth), and inflation hovers at the 3 percent level, yet real long rates are zero to negative?  Come on, man.

Central banks own the yield curve and could give a rat’s ass if they are making money.  But that is starting to change.

Yes, record shorts in Treasury futures.  But that has been the case for almost the entire last year.  In early February, for example, the stock market experienced its biggest spike in volatility in history.

What did the 10-year rate do?  It rose several basis points.  That is important information, folks.

All bets off given a major financial or macro shock.

There are many structural forces working against keeping long-term rates low and the term premium suppressed.  We will be out this week with our work.  Promise.


TNote

Source:  

Posted in Black Swan Watch, Bonds, Interest Rates, Uncategorized | Tagged | 1 Comment

Asian markets versus other developing economies – FT

Posted in Emerging Markets, Uncategorized | Tagged , , | Leave a comment

Distorted Inflation Data & Dynamic Pricing

Just bought Bob Woodward’s new book for a birthday gift from Amazon yesterday for $18.00.  I tried to buy another one this morning and was quoted a price of  $19.32 per book.
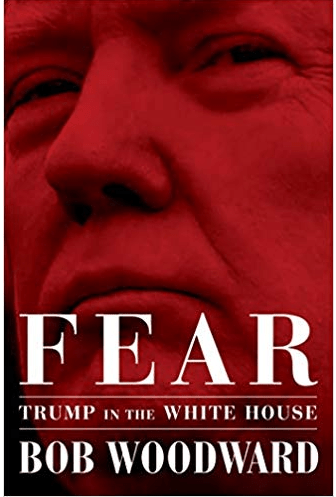
 

Fear

That’s Venezuela-esque inflation, folks.  Works out to 406,506% on an annualized basis.

Dynamic pricing based on predictive analytics is horseshit, in my book, and literally on Woodward’s book.

As the economy moves more and more to pricing in this framework,  how are we to trust the CPI data?  In fact, why do we trust CPI now?

I read sometime back that only about 40-50 percent of the CPI basket are actual, real, measurable prices.   Don’t quote us on this as I need to document it.  Will get back to you on it.

CPI & Cherry COLA

You know in your heart, and your pocketbook, real inflation is running hotter than 3.0 percent.

Here is the main reason why the government works so hard and has a vested interest in repressing the CPI inflation through excess massaging of the data and hedonic adjustments.  Higher COLAs = Bigger Deficits.

An automatic annual Social Security benefit increase is intended to reflect the rise in the cost of living over a one-year period. The Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W), updated monthly by the Bureau of Labor Statistics (BLS), is the measure that can trigger a benefit increase.  The Social Security cost-of-living adjustment (COLA) is based on the growth in the index from the highest third calendar quarter average CPI-W recorded (most often, from the previous year) to the average CPI-W for the third calendar quarter of the current year. If the CPI-W triggers a COLA, the COLA becomes effective in December of the current year and is payable in January of the following year. (Social Security payments always reflect benefits due for the preceding month.) A COLA trigger mechanism was first adopted in P.L. 92-603, the Social Security Amendments of 1972, and triggered COLAs were first payable in 1975.  Prior to 1975, Congress sporadically approved COLAs through the adoption of legislation.  – CRS

More so now than ever.  The mode of the baby boom, 1957, will begin to retire next year and the ranks of the retired set will begin to accelerate dramatically.

Oh, by the way, the Social Security fund will run a deficit this year for the first time since the early 1980’s.  It has been in primary deficit since around 2010.
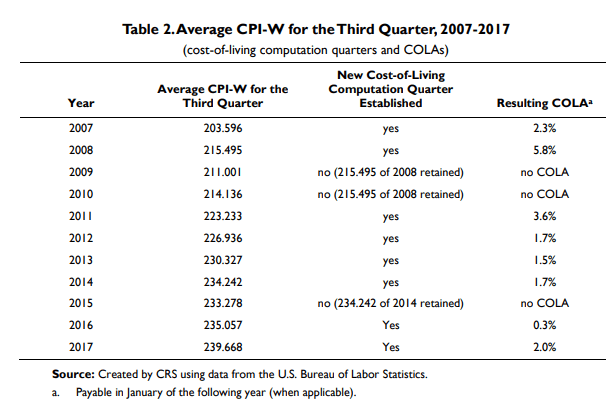
 

COLA


COLA_2


Posted in Inflation/Deflation, Uncategorized | Tagged , , | Comments Off on Distorted Inflation Data & Dynamic Pricing

Dalio on Turkey, Argentina, and the Next Economic Downturn

Sep.12 — Ray Dalio, co-chairman and founder at Bridgewater Associates, examines the crises is Turkey and Argentina and explains his expectations for the next economic downturn. He speaks with Bloomberg’s Erik Schatzker on “Bloomberg Daybreak: Americas.”

Posted in Black Swan Watch, Economics, Uncategorized | Tagged , , | Leave a comment

Week In Review – September 14

Summary

  • Decent week for risk
  • Nice action in Euro periphery and most EMs
  • Tighter U.S. credit spreads

Commentary:   Not much this week.  Markets reflecting strong U.S. economy.  It’s a mug’s game trying to predict short-term stock moves (frickin’ futile), especially in our QE distorted, supply-side restricted world.  We can’t help ourselves.


Week_2018_ETFs


Week_Table

Posted in Uncategorized, Week in Review | Tagged | Leave a comment

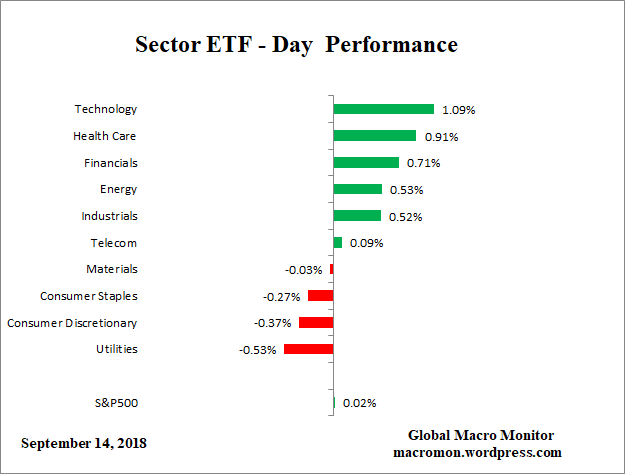
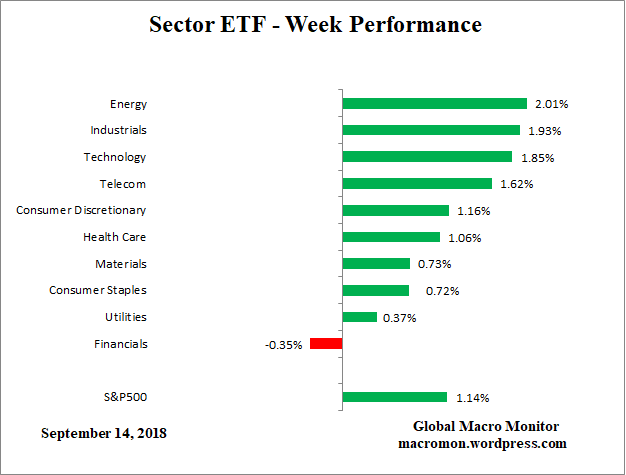
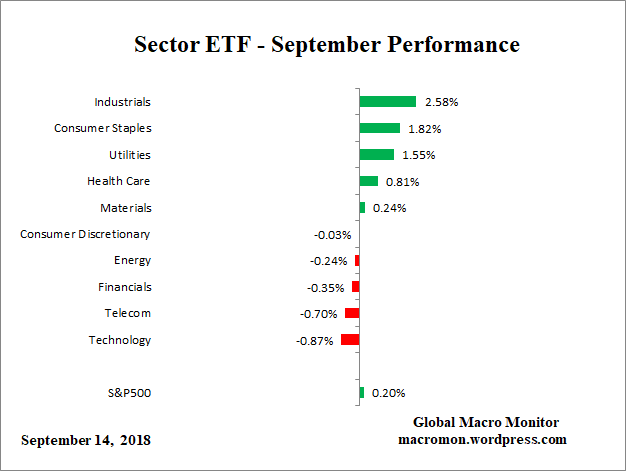
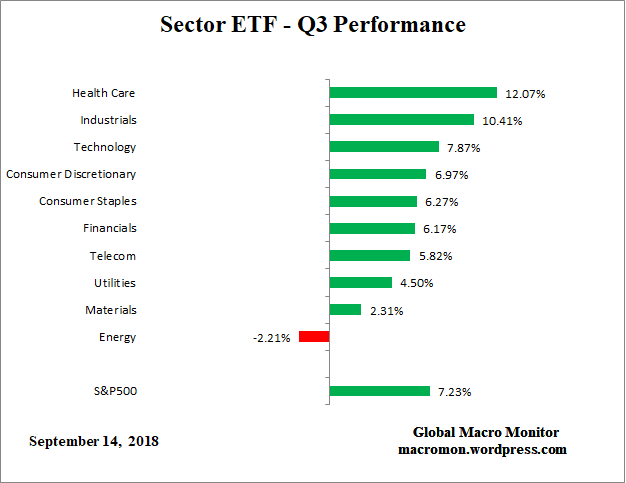
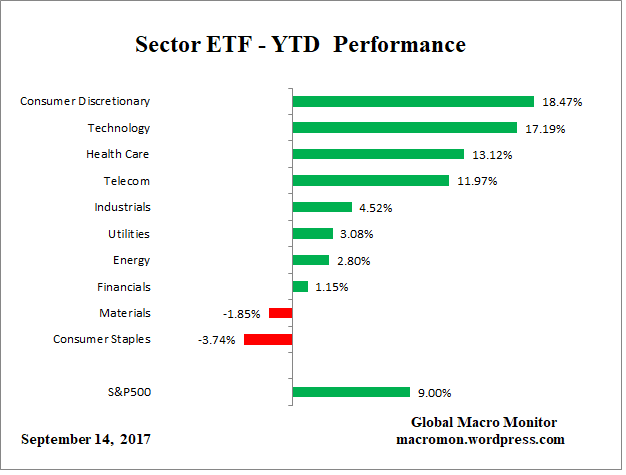
Sector ETF Performance – September 14

ETF_D

ETF_W

ETF_M

ETF_Q

ETF_YTD

Posted in Sector ETF Peformance, Uncategorized | Tagged , | Leave a comment

Global Risk Monitor – September 14

RiskMon_1

RiskMon_2


Posted in Daily Risk Monitor, Uncategorized | Tagged , , , , , | Leave a comment