[Dangerous] Tweet of the Day

Yikes!  Buckle up, folks.

Posted in Politics, President Trump, Uncategorized | Tagged , , | Leave a comment

Tweet of the Day: Cuban Cigars and JFK

https://twitter.com/HistoryInPix/status/969446709930508288

Posted in Tweet of the Day, Uncategorized | Tagged , | Leave a comment

Steel Yourselves

We almost got the Jackie Moon moment – i.e., a panic sell-off – which we warned about in our early morning post if trade tariffs were announced today.   We believe a five percent one day downdraft  would constitute a Jackie Moon move.

Uncanny Similarities With 1962

In our JFK-Trump S&P500 Analog post we mentioned how steel was a big part of the 1962 bear market, when the president referred to steel executives, who broke an agreement with the labor unions and the administration to hold down inflation, as sons of bitches.  JFK’s rant helped accelerate what was a modest correction over inflation worries into a full blown bear market.   The S&P500 was down 5.8 percent off its peak when President Kennedy held his press conference on April 11, 1962 accusing the execs of having “utter contempt” for the United States.  Imagine if Jack had access to Twitter back then!

Today, steel was also at the center of the sell-off in what looks to be the next leg down in what we suspect will also end in a bear market.   The S&P500 was off  a similar 5.5 percent from ts peak when President Trump announced his steel tariffs today.  Hmmmm,..

The Steel Curtain bear markets?


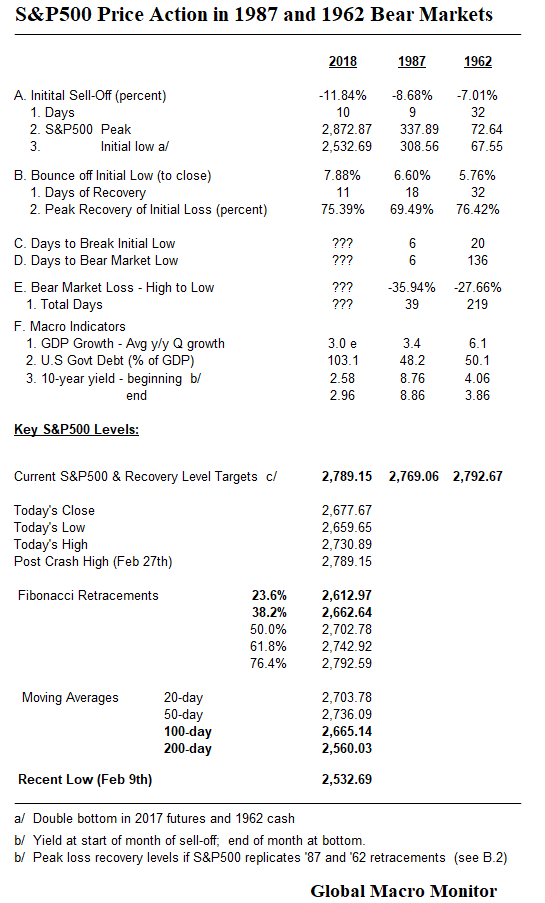
Table_March1


The table also illustrates very similar trough to peak bounces in the first leg of the bear market, 76.42 percent, in 1962,  versus today’s 75.39 percent, which occurred just this past Tuesday.    Close enough for government work, in our opinion.

Moreover, check out this headline today:

Pentagon: We Are “Fully Prepared” For A Russian Nuclear Attack

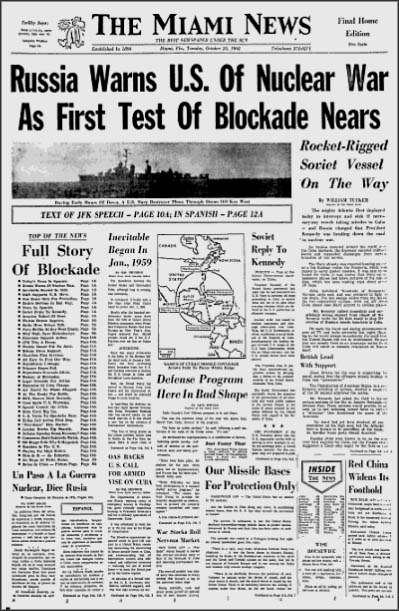
In 1962,

Cuban Missile Crisis_March1


No comparison of today’s danger to the 1962 headline but, hey,  we thought the cold war was way over?

Back to the future,  folks.  Let’s hope not.

Watch These Levels 

The S&P500 breached its 100-day moving average at 2,665.14 and the key Fibonacci retracement level of 38.2 percent at 2,662.64 today but managed to close above both.  We doubt they hold and a retest of of 2,532.69 low is in cards in the next week or two.

We don’t think that holds either.

Unless President Trump walks back the tariffs and his tough trade rhetoric, consider today a game changer, and not for the better.

Steel yourselves.

Appendix

Beware Of Share Buyback Alchemy

Just finished looking through a market cheerleader data set on earnings and revenue projections.  Always quoting earnings on an  EPS basis, which is distorted by buyback alchemy, and non-GAAP accounting.   An example of  Truth Decay in the financial sector.

The later stages of the 2009-2017 bull market are a valuation illusion built on share buyback alchemy.  Absent this accounting trick the S&P500 index would already be in an earnings recession.  Share buybacks have accounted for +40% of the total earnings-per-share growth since 2009, and an astounding +72% of the earnings growth since 2012, compared to +24%.   Since 2009, an estimated +30% of the stock market gains are attributable to share buybacks.  Without share buybacks the S&P500 index would currently trade at an expensive 27x earnings. Not surprisingly, a recent study found a positive relationship between insider equity sales and share repurchases, supporting the idea that buybacks are more about managerial self-interest than share holder value — Artemis Capital, October 2017

Stocks are not cheap, folks.  Be patient.  We may be wrong but believe you will get them much cheaper.  The time to buy will be when the cheerleaders are panicking.

Nevertheless,  don’t bet your career on our views and have a plan to act contingent on if  stocks tank or rally from here.

S&P500 Approaching the Navarro Falls

Analog_March1

Posted in Equities, Uncategorized | Tagged , , , | Leave a comment

Feels Like Jackie Moon Moment Coming

Markets are going to start to fret over potential trade wars after steel and aluminum tariffs are announced by Trump Administration.

Imagine if China retaliates by shutting market to Apple?

Can Jay Powell save the day?

If you are going to panic, always best to do it before everyone else does!

Posted in Uncategorized | Leave a comment

Charles Dickens 2.0

This is a f**ling outrage!  Straight out of a Dickens novel.

Don’t these idjits understand they are sowing the seeds for a mega-mega political backlash?    Can you hear Karl calling?  Or is that Marie trolling us?

Posted in Uncategorized | Leave a comment

POTD: DoJ Flipping Off The President?

It is heating up, folks.  Keep it on your radar.

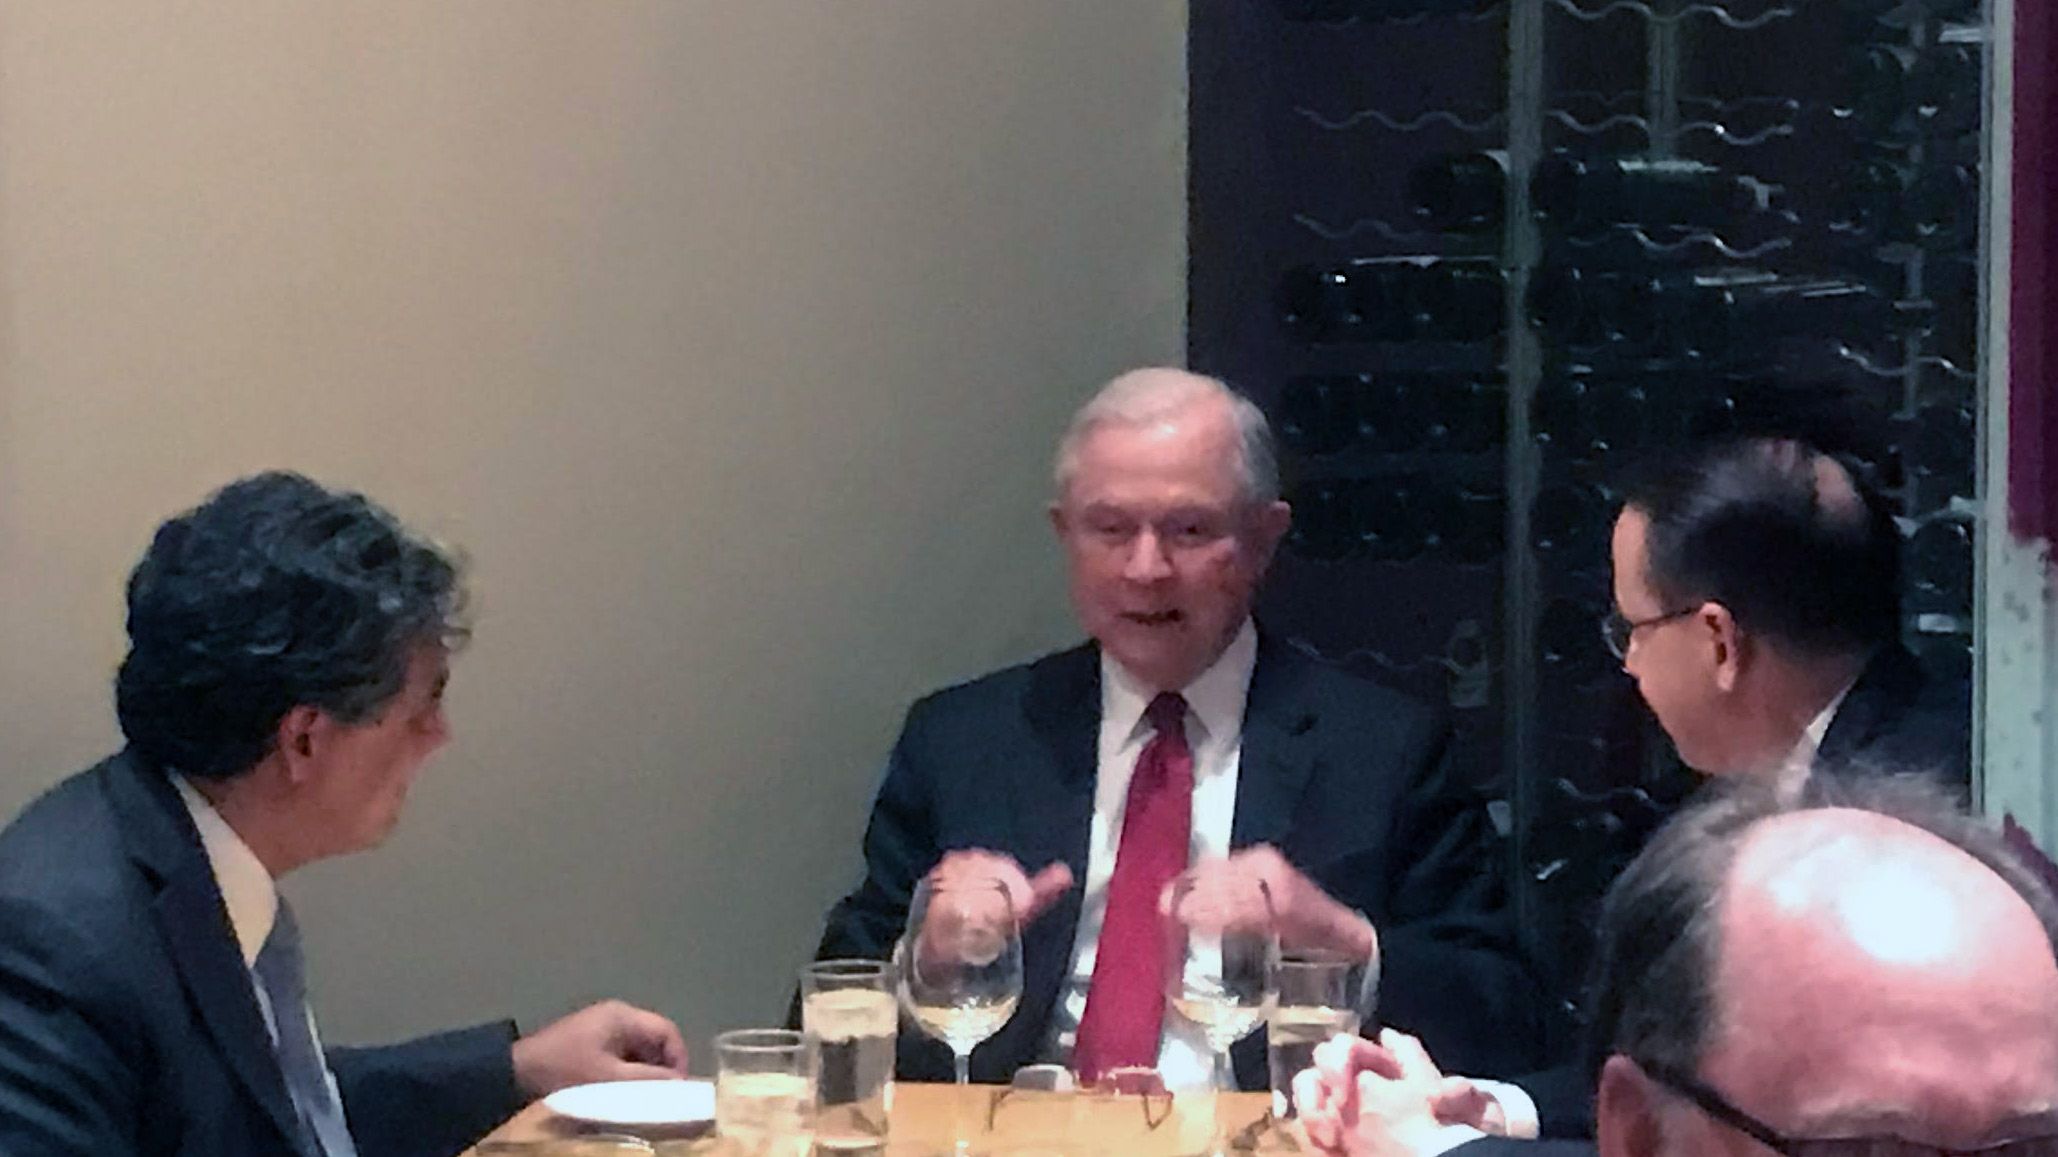
Scoop: Besieged Sessions dines with Rosenstein
If Donald Trump finally follows through on his rage 
and fires Jeff Sessions, the image with this story will be printed in history books.

Tonight at 7:35pm, the Attorney General strode into a high-end Washington restaurant to dine with his deputy Rod Rosenstein and the Solicitor General Noel Francisco.

The symbolism was unmistakable: the three top ranking officials in the Justice Department appearing together in a show of solidarity on the same day Trump is publicly and privately raging about Sessions.

When Trump sees this photo he’ll have to absorb a concept that some of his aides have been trying to impress upon him for nearly a year, since he first began telling them he wanted to get rid of Sessions.

The concept: Fire Sessions, then what next? Are you going to fire Rosenstein too? And then what after that?

Sources close to the situation say today feels different than Trump’s usual rages. Sessions’ allies are deeply concerned and Trump is totally fed up with his AG.

Trump has been taunting and publicly humiliating Sessions for months now, but his tweet this morning was as rough as any he’s sent:

A source close to Sessions, who has spoken with him, says that this meeting was “in no way planned as pushback or an act of solidarity against the president.” The source said Solicitor General Noel Francisco requested the meeting some time ago to talk about carrying out various aspects of the department’s and administration’s agenda. – Axios

(POTD = Picture of the Day)

Posted in Policy, Politics, Uncategorized | Tagged , , | Leave a comment

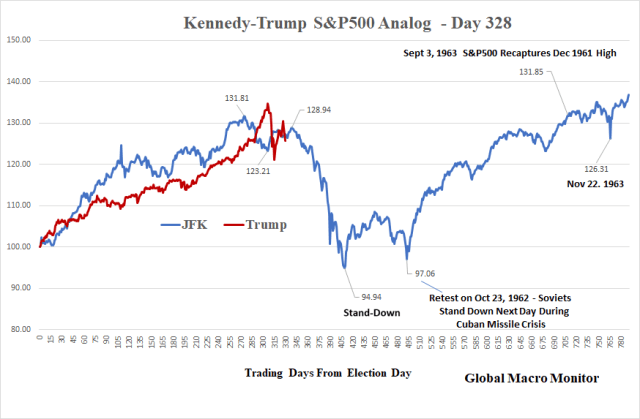
JFK-Trump S&P500 Analog – Five Basis Points On Day 328

After 328 trading days since election day, the Trump S&P500 sits right on top of the JFK S&P500.  That is the performance of the index, 328 trading days after the election day of each president, is less than five basis points within one another.

Rather stunning, don’t you think?

Similar Volatility Shock

Recall in our earlier posts (see here and here), there have been three other massive volatility shocks since 1950,  similar to the one the S&P500 just experienced.

1) 1955: Ike’s heart attack;  2) 1962:  the “Kennedy slide” or JFK bear market; and 3) 1987:  the “crash” bear market, which lasted only 38 days.

We threw out Ike’s heart attack as it was not a prelude to a bear market.  The S&P500 recovered shortly after the sharp Monday sell-off after President Eisenhower had a heart attack on the 8th hole at Cherry Hills Country Club the prior Saturday afternoon.

Though the current S&P500 has the same theme, set-up, and backdrop as the JFK post-election rally and bear market in 1961-62,  the fundamentals drivers of the current correction are very similar to those of the 1987 rout (see here).

The run up in stocks after JFK’s election was spooked by rising inflationary pressures and the president jawboning “big steel” as he felt the executives broke an agreement with the administration and labor unions,

The pact, with ten of the nation’s 11 steel companies, called for an increase in fringe benefits worth 10 cents an hour in 1962, but no wage hikes that year. Then-AFL-CIO President George Meany said that in the pact, the union “settled on a wage increase figure somewhat less than the Steelworkers thought they would get.”

Kennedy praised the contract as “obviously non-inflationary” and said both the USW and the steel firms showed “industrial statesmanship of the highest order.” The agreement also implicitly said the companies would not raise prices, as that would be inflationary.

But on April 10, Roger Blough, CEO of U.S. Steel, the largest of the firms, with 25% of the market, met Kennedy in the Oval Office and told him the company was immediately raising prices by $6 a ton – and that other steel companies would follow. Six did. The 3.5% hike enraged the president. What he said in public was biting – but he was even more caustic in private.

In an April 11, 1962 press conference, Kennedy called the price hikes “a wholly unjustifiable and irresponsible defiance of the public interest.” He criticized “a tiny handful of steel executives whose pursuit of power and profit exceeds their sense of public responsibility.” The execs had “utter contempt” for the U.S., Kennedy said.

In private, Kennedy added: “My father always told me that all businessmen were sons of bitches, but I never believed it until now.” The line quickly became public. –  People’s World

“Sons of bitches” coming from the mouth of a president.  Where have we heard that before?

President Kennedy’s rant against steel came about a month into the S&P’s big downdraft.

True Analog Tracker?

If the analog continues to track, the S&P500 should rally around 1.27 percent in the next ten trading days from today’s close before rolling over hard, suffering a decline of 26.37 percent in the next 73 trading days, bottoming in late June.  The index would then bounce 14.26 percent from the June low the next 41 days before rolling over again to retest the low in late October.  Interesting how October is the month of market bottoms.

Of course, they will not track perfectly,  but they are thus far rhyming with each other on fairly consistent basis.

Nevertheless,  328 days after election day, with both markets experiencing similar volatility shocks – the JFK shock coming a little later than the Trump S&P500 shock – the fact both S&Ps are performing within five basis points of each other is simply amazing.

It’s Right here, Right Now for the analog in the next ten trading days. The Navarro waterfall beckons.

It is starting to get interesting.  The interns now in charge may be about to experience their baptism by fire.

Stay tuned.

JFK_Trump S&P500_Feb28

Posted in Equities, Uncategorized | Tagged | 25 Comments

QOTD: On Fed Chair, Jay Powell

Larry Kudlow just on CNBC quoting President Trump after interviewing Jay Powell for the Fed chair:

“The guy looks like a central banker.”
– President Trump (via Larry Kudlow)

(QOTD = Quote of the Day)

Posted in Monetary Policy, Quote of the Day, Uncategorized | Tagged , , | Leave a comment

Semiannual Monetary Policy Report to the Congress

February 27, 2018

Semiannual Monetary Policy Report to the Congress

Chairman Jerome H. Powell

Before the Committee on Financial Services, U.S. House of Representatives, Washington, D.C.

Chairman Hensarling, Ranking Member Waters, and members of the Committee, I am pleased to present the Federal Reserve’s semiannual Monetary Policy Report to the Congress.

On the occasion of my first appearance before this Committee as Chairman of the Federal Reserve, I want to express my appreciation for my predecessor, Chair Janet Yellen, and her important contributions. During her term as Chair, the economy continued to strengthen and Federal Reserve policymakers began to normalize both the level of interest rates and the size of the balance sheet. Together, Chair Yellen and I have worked to ensure a smooth leadership transition and provide for continuity in monetary policy. I also want to express my appreciation for my colleagues on the Federal Open Market Committee (FOMC). Finally, I want to affirm my continued support for the objectives assigned to us by the Congress–maximum employment and price stability–and for transparency about the Federal Reserve’s policies and programs. Transparency is the foundation for our accountability, and I am committed to clearly explaining what we are doing and why we are doing it. Today I will briefly discuss the current economic situation and outlook before turning to monetary policy.

Current Economic Situation and Outlook
The U.S. economy grew at a solid pace over the second half of 2017 and into this year. Monthly job gains averaged 179,000 from July through December, and payrolls rose an additional 200,000 in January. This pace of job growth was sufficient to push the unemployment rate down to 4.1 percent, about 3/4 percentage point lower than a year earlier and the lowest level since December 2000. In addition, the labor force participation rate remained roughly unchanged, on net, as it has for the past several years–that is a sign of job market strength, given that retiring baby boomers are putting downward pressure on the participation rate. Strong job gains in recent years have led to widespread reductions in unemployment across the income spectrum and for all major demographic groups. For example, the unemployment rate for adults without a high school education has fallen from about 15 percent in 2009 to 5-1/2 percent in January of this year, while the jobless rate for those with a college degree has moved down from 5 percent to 2 percent over the same period. In addition, unemployment rates for African Americans and Hispanics are now at or below rates seen before the recession, although they are still significantly above the rate for whites. Wages have continued to grow moderately, with a modest acceleration in some measures, although the extent of the pickup likely has been damped in part by the weak pace of productivity growth in recent years.

Turning from the labor market to production, inflation-adjusted gross domestic product rose at an annual rate of about 3 percent in the second half of 2017, 1 percentage point faster than its pace in the first half of the year. Economic growth in the second half was led by solid gains in consumer spending, supported by rising household incomes and wealth, and upbeat sentiment. In addition, growth in business investment stepped up sharply last year, which should support higher productivity growth in time. The housing market has continued to improve slowly. Economic activity abroad also has been solid in recent quarters, and the associated strengthening in the demand for U.S. exports has provided considerable support to our manufacturing industry.

Against this backdrop of solid growth and a strong labor market, inflation has been low and stable. In fact, inflation has continued to run below the 2 percent rate that the FOMC judges to be most consistent over the longer run with our congressional mandate. Overall consumer prices, as measured by the price index for personal consumption expenditures (PCE), increased 1.7 percent in the 12 months ending in December, about the same as in 2016. The core PCE price index, which excludes the prices of energy and food items and is a better indicator of future inflation, rose 1.5 percent over the same period, somewhat less than in the previous year. We continue to view some of the shortfall in inflation last year as likely reflecting transitory influences that we do not expect will repeat; consistent with this view, the monthly readings were a little higher toward the end of the year than in earlier months.

After easing substantially during 2017, financial conditions in the United States have reversed some of that easing. At this point, we do not see these developments as weighing heavily on the outlook for economic activity, the labor market, and inflation. Indeed, the economic outlook remains strong. The robust job market should continue to support growth in household incomes and consumer spending, solid economic growth among our trading partners should lead to further gains in U.S. exports, and upbeat business sentiment and strong sales growth will likely continue to boost business investment. Moreover, fiscal policy is becoming more stimulative. In this environment, we anticipate that inflation on a 12-month basis will move up this year and stabilize around the FOMC’s 2 percent objective over the medium term. Wages should increase at a faster pace as well. The Committee views the near-term risks to the economic outlook as roughly balanced but will continue to monitor inflation developments closely.

Monetary Policy
I will now turn to monetary policy. The Congress has assigned us the goals of promoting maximum employment and stable prices. Over the second half of 2017, the FOMC continued to gradually reduce monetary policy accommodation. Specifically, we raised the target range for the federal funds rate by 1/4 percentage point at our December meeting, bringing the target to a range of 1-1/4 to 1-1/2 percent. In addition, in October we initiated a balance sheet normalization program to gradually reduce the Federal Reserve’s securities holdings. That program has been proceeding smoothly. These interest rate and balance sheet actions reflect the Committee’s view that gradually reducing monetary policy accommodation will sustain a strong labor market while fostering a return of inflation to 2 percent.

In gauging the appropriate path for monetary policy over the next few years, the FOMC will continue to strike a balance between avoiding an overheated economy and bringing PCE price inflation to 2 percent on a sustained basis. While many factors shape the economic outlook, some of the headwinds the U.S. economy faced in previous years have turned into tailwinds: In particular, fiscal policy has become more stimulative and foreign demand for U.S. exports is on a firmer trajectory. Despite the recent volatility, financial conditions remain accommodative. At the same time, inflation remains below our 2 percent longer-run objective. In the FOMC’s view, further gradual increases in the federal funds rate will best promote attainment of both of our objectives. As always, the path of monetary policy will depend on the economic outlook as informed by incoming data.

In evaluating the stance of monetary policy, the FOMC routinely consults monetary policy rules that connect prescriptions for the policy rate with variables associated with our mandated objectives. Personally, I find these rule prescriptions helpful. Careful judgments are required about the measurement of the variables used, as well as about the implications of the many issues these rules do not take into account. I would like to note that this Monetary Policy Report provides further discussion of monetary policy rules and their role in the Federal Reserve’s policy process, extending the analysis we introduced in July.

Thank you. I would be pleased to take your questions.

Related Content
Congressional Hearing Transcripts
Hearing transcripts are posted to this website as they become available.
Back to Top
Last Update: February 27, 2018

Posted in Fed, Monetary Policy, PMIs, Policy, RSIs, Sector ETF Peformance, Sports, Uncategorized | Tagged , | Leave a comment

Ambiguity Of The Dow’s Value: -3.3% GAAP v 10.5% non-GAAP 2017 Earnings

One more example of the ambiguity of stock value  and why earnings are, or can be, the creature of  a company’s CFO.  This is exactly why we prefer top line metrics, such as sales and revenues.  See here for debate on GAAP vs. non-GAAP measures.

Posted in Earnings, Equities, Uncategorized | Tagged , , | Leave a comment