Reflexivity And Why The Fed Must Sell The Long End

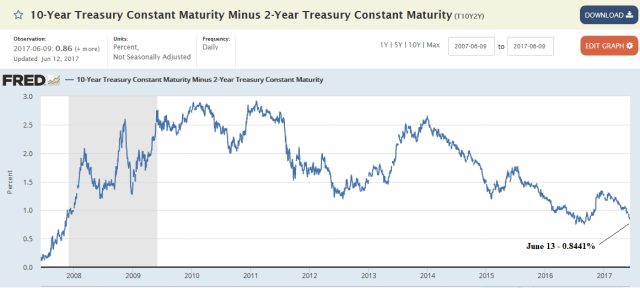
The yield curve is flattening like a pancake.   Tightening cycles tend to do that.

Bond_Yield Curve

Curve_June13

Furthermore, the effective float of 10-year and longer U.S. notes and bonds is relatively small and greatly distorts the bond market signal.   We have written about this several times.

…how small the actual float of longer-term marketable U.S. Treasury securities is available to traders and investors. The data show the Fed owns about 35 percent of Treasury securities with maturities 10-years or longer. Note the data only include notes and bonds and excludes T-Bills.

The Fed’s holdings combined with foreign ownership of longer maturities — more than 1-year — exceeds 80 percent of marketable Treasuries outstanding. The Fed combined with just foreign official holdings, mainly, foreign central banks, is 65 percent of maturities longer than 1-year. Thus, almost 2/3rds of tradeable Treasuries longer than 1-year are held by entities with no sensitivity to market forces.  –  GMM, March 2017

Given the small float of tradeable Treasury notes and bonds,  the market is subject to both massive short squeezes if it gets too far offside and rapid ramps if traders algos try and game duration.

Information Positive Feedback Loop
Many in the market,  we fear, are being hoodwinked by the flattening yield curve, however.  It’s purely the result of technicals and not economic fundamentals.

Nevertheless,  some still look to the badly distorted bond market as a signal of the health of the economy and act accordingly.   Such as delaying capital spending;  becoming more risk averse;  and cutting back on consumption, for example.

A flatter yeld curve also makes bank lending less profitable.

This could thus lead to what George Soros calls “reflexivity“,  a feedback loop where the negative, but false, signal from the bond market actually causes an economic slowdown or leads to a recession.   So much for efficient markets.

Recall the famous line of one prominent market strategist during the dark days of the great recession,

“ We’re in a depression. That is what the bond market is telling us.”

Or the ubiquitous,  “what is the bond market telling us?”    Come on, man!

The Fed Needs To Start Selling Longer Dated Securities
It would, therefore,  behoove the Fed to sell some of its longer dated Treasury holdings in order to steepen the yield curve.

The following table shows the Federal Reserve’s holdings of U.S. Treasury securites and the total Treasury outstandings for each year.  This table does not include T-Bills.

If the Fed were to just let its balance sheet “run off” — that is not rollover maturing notes and bonds — it would cause additional pressure on short-term interest rates even as policy rates are rising.  It could also  potentially invert or further distort the front-end of the yield curve and destablize the money markets.

Looking at the data in 2018 and 2019  large maturities are coming due, of which, the Fed holds about 25 percent of the total of Treasuries maturing.

Rolling a portion of these maturities and selling longer-dated securities would probably cause less disruption in the market and be a more optimal strategy of reducing the Fed balance sheet.
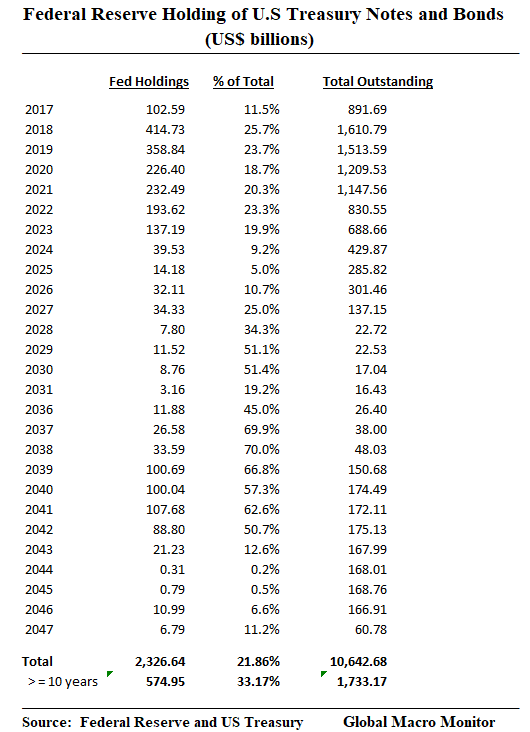
Notes and Bonds_June13

Announcement Effect
Just announcing the fact the Fed was contemplating such a strategy of unloading longer dated Treasuries first would cause the yield curve to steepen.   The market would  begin to front run the Fed.  Bill Gross & Co. would kick into action and start “selling what the Fed wants to sell.”

And because there are so relatively few Treasuries outstanding with maturities longer than 10-years,  it is unlikely it would cause the bond market debacle, which many believe is coming.  The total stock of Treasury securities with maturities longer than 10-years is smaller than the combined market capitalization of just Apple, Google, and Amazon, for example.

If bonds become too oversold, the Fed could easily engineer a short squeeze to bring the yield curve back to where it desires.

Recall, the Fed losing control of the yield curve prior to the financial crisis to foreign central banks recyling capital flows back into the U.S. bond market is what Alan Greenspan singles out as the major cause of the housing bubble.   The Fed moved the funds rate up 425 bps and the 10-year and mortgage rates barely budged.

During the 2004-07 tightening cycle, the era of the Greenspan bond market conundrum, for example, the 10-year yield managed to rise only a maximum of 64 bps during the entire cycle from a beginning yield of 4.62 percent to a cycle high yield of 5.26 percent. This as Greenspan raised the fed funds rate by 4.25 percent, from 1.0 percent to 5.25 percent.  – GMM, March 2017

Risks
The major risk is that foreigners begin to sell.  But where will they go?

Spanish 10-years at 1.43 percent?  German 10-year bunds at 0.266 percent?  How about a 10-year Japanese JGB at 0.067 percent?    In fact,  low foreign yields and the ensuing portfolio effect is keeping the U.S. 10-year note well anchored below 2.60 percent and another factor distorting the yield curve.

Central banks could also be forced to sell some of their $4 trillion U.S. Treasury holdings if global currencies come under pressure via-a-vis the dollar.  To maintain currency stability, monetary authorities could be forced to intervene in their foreign exchange markets.

Such was the case with China over the past few years, which experienced a major bout of capital flight.  The PBOC suffered a loss of FX reserves close to a trillion dollars, some of which were held in U.S Treasuries.

Credit and Equity Markets
That is where we could have some short-term problems and overshooting.   But our sense, many are waiting to pounce on a sell-off in the spread and equity markets.   Too many pensions are underfunded and too many seniors are yield strarved.

Having some dry powder makes sense.    It’s coming and you will have to act fast.

Conclusion
A sustained spike in inflation?

Tilt!  Game over, comrades.
 

Posted in Bonds, Economics, Monetary Policy, Uncategorized | Tagged , , | 31 Comments

Of Course, There’s No Inflation. NOT!

Okay,  before the emails hit – it’s peak load pricing or a relative price increase.

There, satisfied?

Buyer pays $133K for two courtside tickets to Game 5 of NBA Finals

A person paid $133,000, including fees, for two floor seats to Game 5 of the NBA Finals at Oracle Arena to possibly see the Golden State Warriors win their second title in three years.

A team source said that a Warriors season-ticket holder sold the seats on the team’s Ticketmaster resale site on Sunday night. With buyer fees at 15 percent, the buyer paid more than $17,000 in fees alone for the pair of tickets.

While the face value of the specific tickets is unknown, some courtside seats for the Finals have a face value of $3,000 each, according to a document sent by the Warriors to fans during renewal time last year.

The average resale price on the team site for Game 5 is $1,731, which is almost 20 percent higher than last year’s Game 5 between the Warriors and the Cleveland Cavaliers ($1,444).

The site had two other big sales for the most prime seats in the arena — one pair was sold for $90,000, while another was sold for $82,000.   — USA Today

The above sure sounds like the mark of the top of something, no?   The Roaring ………… something.

Inflation in the Real World
Nevertheless,  just, today,  noticed the local grocery market increased the price of a two-liter bottle of soda by 10-20 percent in the past few weeks.

Who is the government kidding?   You and I know, first hand, the real inflation rate is running much higher than the official figures.

Where you drink champagne and it tastes just like cherry (COLA)
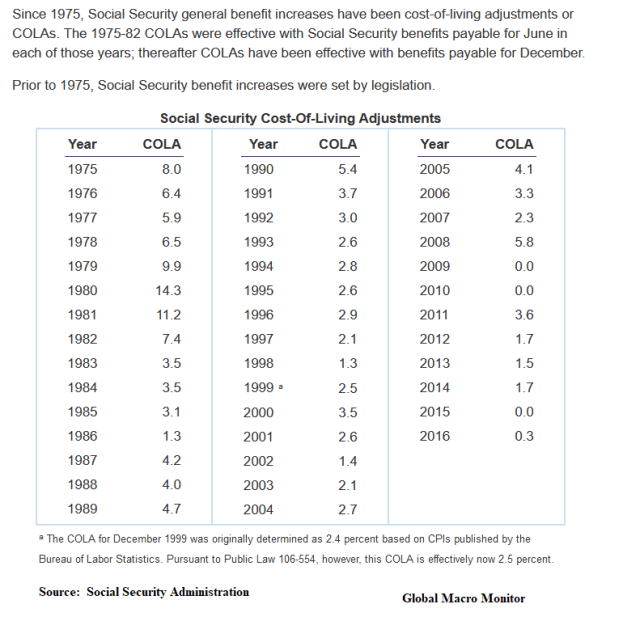
With all the baby boomers retiring the government and taxpayer, not to mention those on fixed incomes, are in deep doo-doo if  the “so-called” official inflation picks up and the cost of living adjustments (COLA) on social security payments begin to spike.

Expect more inflation data repression:  seasonal adustments;  changing consumption baskets;  and hedonic pricing adjustments.

The use of the word “hedonic” to describe this technique stems from the word’s Greek origin meaning “of or related to pleasure.” Economists approximate pleasure to the idea of utility – a measure of relative satisfaction from consumption of goods. In price index methodology, hedonic quality adjustment has come to mean the practice of decomposing an item into its constituent characteristics, obtaining estimates of the value of the utility derived from each characteristic, and using those value estimates to adjust prices when the quality of a good changes.  – BLS

Bond Market Predicting Deflation?
But, you say, the bond market is predicting deflation?   Complete Nonsense.  There is no signal from the bond markets.

QE Distortion
The intervention into the bond markets by central banks through quantitative easing (QE) in the big four sovereign bond markets – U.S., Japan, Eurozone, and UK – has created a structural shortage of risk-free instruments and distorted the most important price in the world — the yield on 10-year hard currency sovereign bonds. – GMM, March 2017

SS_Cola

With elderly conservative savers earning zero on their CDs and the social security COLA averaging only 1 percent over the past five years no wonder the economy feels so punk.   Definite deletarious impact on the demand of the senior set.

By the way,  how much copper does it take to write code for artificial intelligence or robotics software?   Just askin’.    The Times They Are A Changin’.

Posted in Demographics, Economics, Inflation/Deflation, Uncategorized | Tagged , | Leave a comment

The Pinball Wizards Romp!

Just to understand what high expectations we have for the Golden State Warriors in the Bay Area,  I am a little deflated because the Dubs didn’t go 16-0 in the playoffs.   Tough to live up to those expectations, no?  But, hey, I will take 16-1!

I can now definitively say,  “Kevin Durant (aka KD) is the best athlete in the world.”   Have you ever seen a 7-footer move the way he does?

Ever since I was a young boy,
I’ve followed basketball.
From ‘Frisco down to Oakland
The ‘Dubs can whip them all
But I ain’t seen nothing like them
In any roundball hall…

That Steph, KD, Dray and Klay kid
Sure play a mean b-ball!

They’re the Pinball Wizards
There has got to be a twist
The Pinball Wizards,
Love the sound of that three point swish!

.

Chron_Front Page.png

.

Posted in Sports, Uncategorized | Tagged , , | Leave a comment

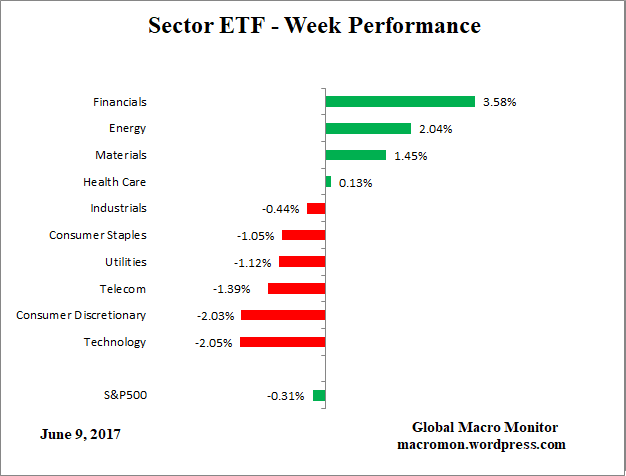
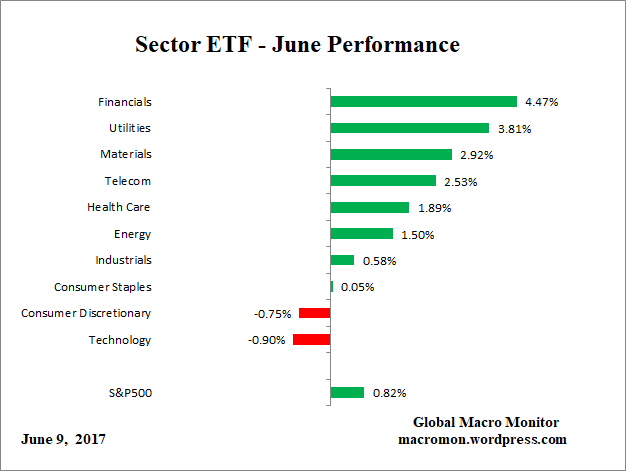
US Sector ETF Performance – June 9

ETF_DayETF_WeekETF_MonthETF_QETF_YTD

Posted in Sector ETF Peformance, Uncategorized | Tagged , | Leave a comment

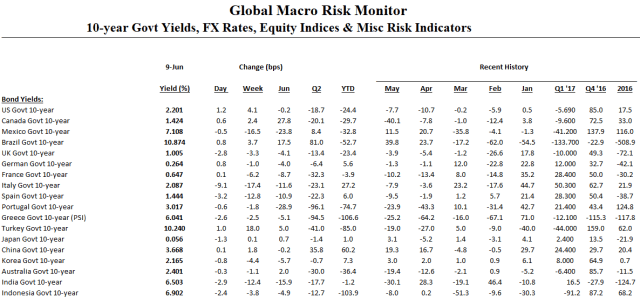
Global Risk Monitor – June 9

Click on table to enlarge and for better resolution

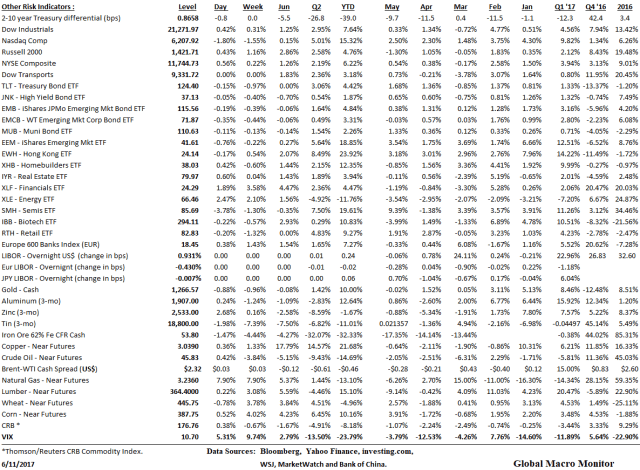
RiskMon_1RiskMon_2RiskMon_3

Posted in Daily Risk Monitor, Uncategorized | Tagged , , , , , | Leave a comment

Volatility Returns (to the NASDAQ)

At around 2 pm (New York) Friday, we see the Nasty (NASDAQ 100 futures) trading down over 3 percent and the Dow and S&P500 relatively flat.  The FANG stocks, including Apple, were getting shellacked

I recall a few weeks ago a prominent strategist saying on CNBC that Apple was the closest thing to risk-free in the market.  The FANG trade is more crowded than Oakland’s Oracle Arena will be on Monday night, Game 5 of the NBA Finals.

Dipping Our Toes In
Nevertheless,  we thought we’d give it the old college try,  venturing out of commodites (that is where the volatility has been), which has been a disaster for us this year, to trade the Nasty into the close,  both long and short.

Not every trade was profitable and it was one helluva a ride, but, in the end, we made some cheese.  The index ended the last hour and a half gapping around 30-60 points at a time in just few minute intervals.   It’s been hard making money this year in commodities and it was nice winning a few rounds from the Algos, for once.

Overall Volatility Still Low
The NASDAQ ended down around 1.8 percent on the day, the Dow and Russell were up 0.4 percent and the S&P500 was flat to down a bit.   The VIX closed  up at 10.7.

A consensus seems to be buiding the Trump trade — industrials,  materials, banks, and energy stocks — is back on.    Is the the growth scare over?   Watch this space.

Trump Trade Returns
We believe, and so seems the market, the James Comey testimoney on Thursday was Trump positive (or not that negative — i.e., no schmoking gun) and that Republicans are kicking into the “two-minute” drill.    That is they are now in hurry up mode to pass legistlation as they realize the political guillotine looms in Novemeber 2018 and could potentially cost them both houses of Congress.

Crash Coming?
There is just too much global liquidity for asset markets  to correct on a general basis, in our opinion.

Relative price and sector shifts?   Absolutely!

A sustained market crash?  NFW!

Not until central banks start draining the swamp.  Furthermore,  Mario Draghi sounded more dovish than Saint Francis of Assisi at Thursday’s ECB meeting.   And, remember,  “John Bull will still be able to stand many things but won’t stand for 1 percent.  Or was it 2 percent?

The global flood of money has to go somewhere  until its starts being removed from the financial system through central bank balance sheet reduction.   And we believe the tipping point on policy interest rates for the markets is 3 percentish, but the Fed will be reluctant to take it there as it will have a deletrious effect on the U.S. budget deficit. Higher interest rates equate to higher interest payments on the national debt and crowding out of other discretionary spending programs.

Don’t want to enter that ugly positive feedback loop, which will be the beginning of the end for the debt supercycle and could result in enornous political stress.

Fall Correction
However, beware the ides of October.

The Fed may start draining the swamp in the fall , i.e., reducing their balance sheet and, thus,  the monetary base;   and China’s  Communist Party Congress wil conclude, which may clear the way for a policy or an economic surprise.

Those wanting to get long should have a nice opportunity to do so when the leaves turn brown and gold in the autumn.

Conclusion
Finally,  remember comrades, just like everyone else, we can’t predict the future and may be completely wrong.   Flexible conviction is all the rage.

And all of the above are just our opinions,  and you know what they say about opinons.   They are like arses, everyone has one.   Some are developed more riguously than others, and some may look  better than others.

Stay tuned.

Nasty_1Nasty_2

Posted in Algos, Equities, Uncategorized | Tagged , , , | Leave a comment

Headline of the Day: Bookies Swallow the Doughnut Again

Bookies declare the U.K. election is all over but the shouting

Bookies now give Theresa May, Tories an 85% chance to win an outright majority.   –  Market Watch, June 8, 2017


Posted in Politics, Reads, Uncategorized | Tagged , | Leave a comment

The Pinball Wizards


Ever since I was a young boy,

I’ve followed basketball.
From ‘Frisco down to Oakland
The ‘Dubs can whip them all
But I ain’t seen nothing like them
In any roundball hall…

That Steph,KD, Dray and Klay kid
Sure play a mean b-ball!

They’re the Pinball Wizards
There has got to be a twist
The Pinball Wizards,
Love that three point swish!

.

.

Thank you,  Grace!

Posted in Sports, Uncategorized | Tagged , | Leave a comment

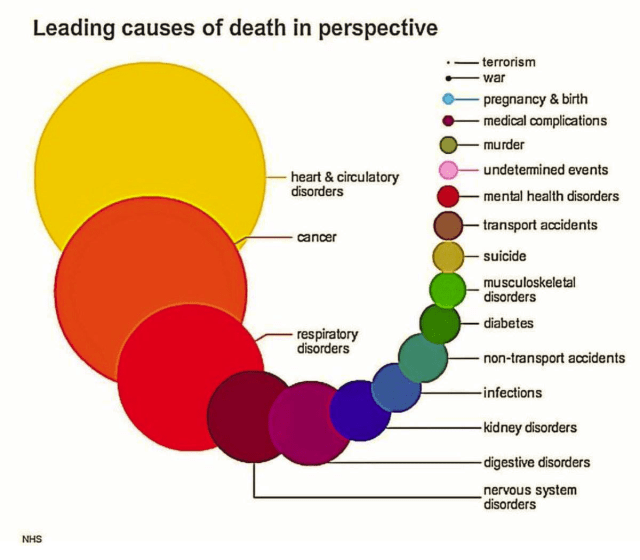
Chart and Quote of the Day: Death and Uncle Joe

One death is a tragedy; one million is a statistic.  — Joseph Stalin

Man, our spending priorities are out of whack.   Connect the dots.
Leading Causes of Death_June 5
Posted in Economics, Uncategorized | Tagged , | 3 Comments

Strange Currencies and Barter 101

Once upon a time, currencies had intrinsic value.  But now the dollar slouches towards Bethlehem  Wampum.

Ever wonder where the term “buck” comes from?

As in “Ray Nichols, you owe me 100 bucks for our bet the Golden State Warriors would sweep the Cleveland Caviliers in the 2017 NBA Finals?”  And “the buck stops here?”

Animal Skins

Animal skins have a surprisingly important history as currency in different parts of the world.

In Russia and Finland, squirrel pelts were a key medium of exchange during medieval times. Even today, the Finnish word “raha”, which now refers to money, originally meant the “fur of squirrel”.

In North America, the European settlers and First Nations tribes found skins to be one commodity they both agreed had value.

In 1748, Beaver pelts became the “standard of trade” in the north. One pelt could buy two pounds of sugar.

Lastly, the use of buck skins in trade gave rise to “buck” as a slang word for currency, which we still use to describe dollars today.  – Visual Capitalist

.

Buck_June4

Or how about the etymology of the term “salary” or the phrase Lebron is “not worth his salt?”

Salt

The importance of salt to ancient civilizations cannot be understated. The first written record on salt appears in 2700 BCE in China.

Salt was highly valued for food preservation, but its production was very limited. As a result, in many places of the world, salt was used as currency.

  • As early as the 6th century, Moorish merchants in sub-Saharan Africa routinely traded salt and gold at the same value per ounce.
  • In what is now modern-day Ethiopia, slabs of rock salt were used as coins. Each coin was 10 inches long and two inches thick.
  • Salt was also used as pay soldiers in Ancient Rome. This became known as “solarium argentum”, from which we now derive the word “salary”
  • A soldier’s salary was cut if he was “not worth his salt”, a phrase that still exists today. – Visual Capitalist

Salt_June4

Interesting stuff, no?

Go Dubs!    I will trade you one Steph Curry and one Kevin Durant basketball card for ten Lebron James cards.  How is that for an exchange rate?

PPP, over or undervalued?

Posted in Monetary Policy, Uncategorized | Tagged , , , | 1 Comment