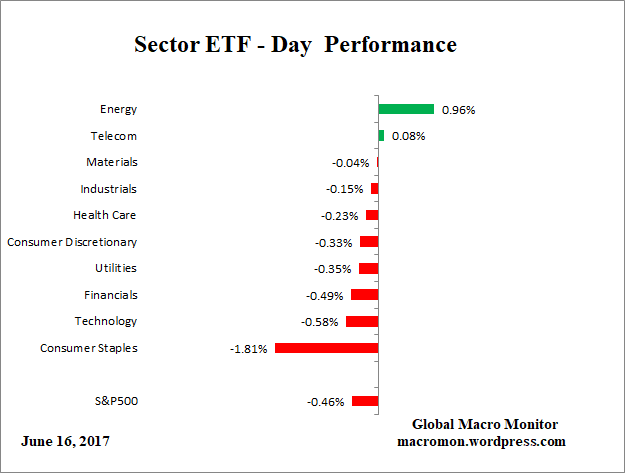
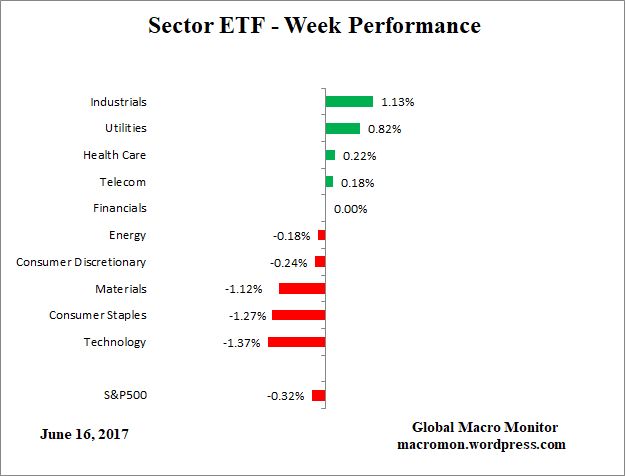
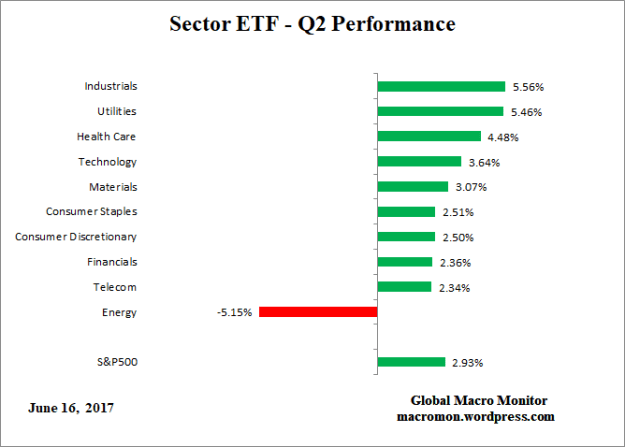
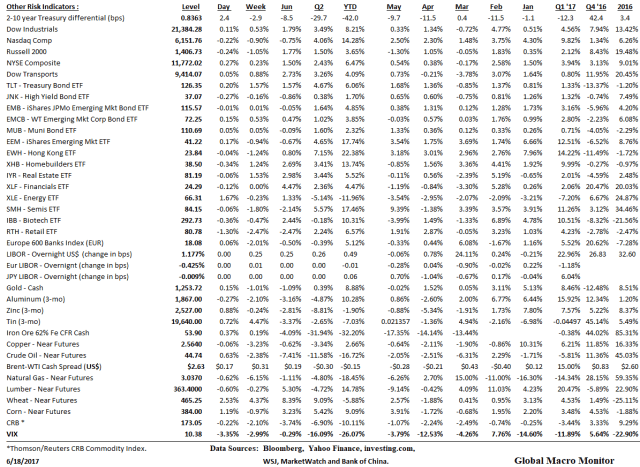
Click on table to enlarge and for better resolution
Click on table to enlarge and for better resolution
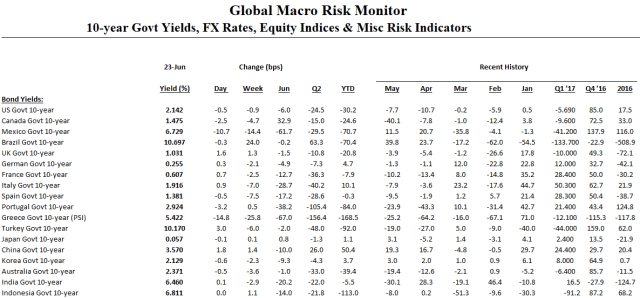
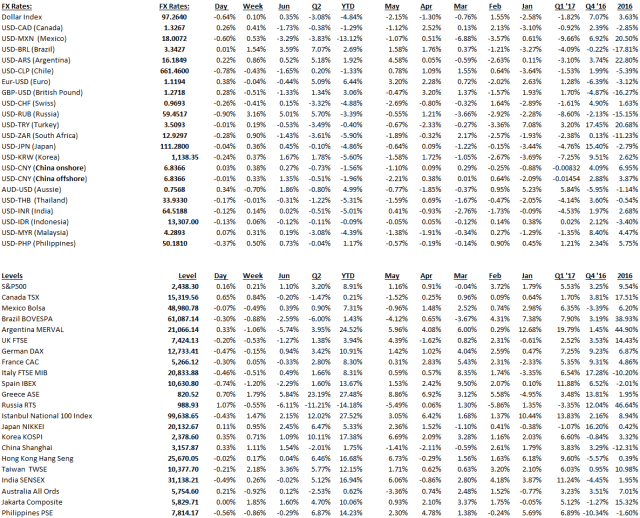
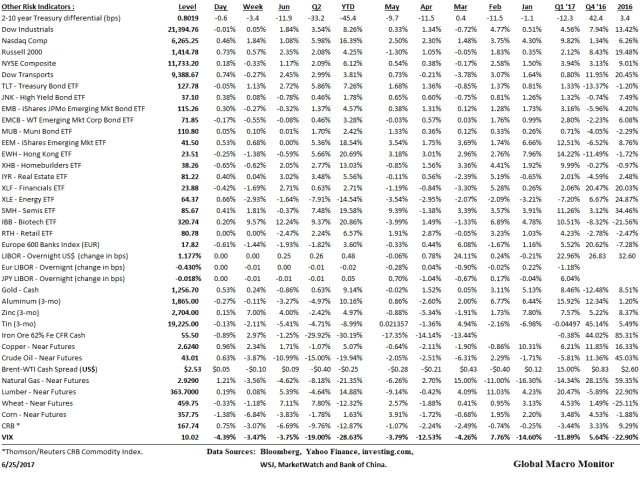
Lot’s of hand wringing these days about the flattening yield curve. We still maintain our position that the signal from the bond market is significantly distorted due to the global central bank intervention (QE) into the bond markets. See here and here.
Most of what is happening with the U.S. yield curve is technical. Sure, traders can get a wild hair up their arse, believing the economy is slowing and try and game duration by punting in the cash or futures markets. Given the small relative float of the U.S. Treasury bond market, however, it doesn’t take much buying to move yields. In the words of economists, the supply curve of outstanding Treasuries is very inelastic.
This is illustrated in the following chart. The combined market cap of just Apple and Amazon at today’s close is larger than the entire the float of outstanding Treasury notes and bonds that mature from 2027-2027. We define float (US$1.16 trillion) as total Treasury securities (2027-2047) outstanding (US$1.73 trillion) less Fed holdings (US$575 billion).

Now consider you started the year with, say, a hypothetical $3 billion portfolio of Amazon, Apple, and Treasury notes and bonds, each with a 33.3 percent weighting.
Given the rise of Apple and Amazon stock prices just this year, the current under weight in your Treasury position relative to the start of year would force an additional purchase of US$226 million of bonds to get back to the 33.33 percent weighting. The allocation effect of a stock bull market or bubble on the bond markets can be a powerful source of demand.
This is a classic case of a positive feedback loop between two markets. The allocation effect and the increased demand for bonds lowers the interest rate making stocks fundamentally more attractive as the rate to discount corporate cash flows declines. This drives up stock prices ergo another allocation effect on bonds.
Here’s to hoping that in the next decade we, and the policy makers, don’t look back at this period with regret realizing we got the signal from the yield curve entirely wrong. In hindsight, it is always so obvious.
Wow! When is the last time you met a cop that spoke nine languages?
Robocop
On Wednesday, May 24, Dubai will launch a new police robot that marks the first phase of the integration of robots into the police force. This modified version of the REEM robot (Designed by PAL robotics and unveiled in 2011) is capable of feeding video to a command center, forwarding reported crimes to police, settling fines, facial recognition, and speaking nine languages. It will operate at most malls and tourist attractions.
Dubai hopes robots will constitute 25 percent of its police force by 2030, with the next stage being to use them as receptionists in police stations. Brigadier Khalid Nasser Alrazooqi, General Director of Dubai Police’s Smart Services Department, told CNN that they eventually want to release a “fully-functional robot that can work as [a] normal police officer.” — WEF, May 2017

File this one under, “What If.”
We have a very good source who tells us that the U.S. and the major European and Arab powers had a plan to exile Saddam Hussein to Saudi Arabia before the Iraq war began in March 2003. Apparently, Saddam was on board with the plan. But the U.S. and other major powers had to show complete solidarity lest Saddam would sense disunity and misread it as a lack of will to take him out and thus back out of the deal.
Recall, Hussein had a history of miscalculating and misreading the United States. In a meeting with the U.S. ambassador in July 1990 , Saddam took the conversation as tacit approval for his invasion of Kuwait eight days later.
July 25, 1990 – Presidential Palace – Baghdad
U.S. Ambassador Glaspie – I have direct instructions from President Bush to improve our relations with Iraq. We have considerable sympathy for your quest for higher oil prices, the immediate cause of your confrontation with Kuwait. (pause) As you know, I lived here for years and admire your extraordinary efforts to rebuild your country. We know you need funds. We understand that, and our opinion is that you should have the opportunity to rebuild your country. (pause) We can see that you have deployed massive numbers of troops in the south. Normally that would be none of our business, but when this happens in the context of your threat s against Kuwait, then it would be reasonable for us to be concerned. For this reason, I have received an instruction to ask you, in the spirit of friendship – not confrontation – regarding your intentions: Why are your troops massed so very close to Kuwait’s borders?
– July 25, Eight days before the August 2, 1990 Iraqi Invasion of Kuwait
A big mistake and that was even before Twitter.
The Need To Show Political Unity
A recent article in Foreign Policy magazine put the need for unity among the big powers before the second Iraq war more eloquently,
Political unity among western democracies, can have an impact at least as great as the application of raw power on real-world outcomes. It is worth paying a high cost up front to get those perceptions right, because the consequences down the road can be severe.
…The idea was to create a credible threat of military force that would cause him to shut down programs and allow intrusive inspections. —
To the horror of this world leader, he awoke one morning to see France’s President, Jacques Chirac, on television announcing France would not support the war effort and vote against the second United Nations resolution. Saddam sensed weakness that there would be no invasion and, as expected, backed out of the deal. Once again, miscalculating and misreading the intentions of another Bush Administration in the United States.
Chirac’s Relationship With Saddam
Jacques Chirac always had a suspect relationship with Saddam Hussein. Bush #43 called him Mr. Arab.
Statfor wrote in 2003,
Chirac and Hussein formed what Chirac called a close personal relationship. As the New York Times put it in a 1986 report about Chirac’s attempt to return to the premiership, the French official “has said many times that he is a personal friend of Saddam Hussein of Iraq.” In 1987, the Manchester Guardian Weekly quoted Chirac as saying that he was “truly fascinated by Saddam Hussein since 1974.” Whatever personal chemistry there might have been between the two leaders obviously remained in place a decade later, and clearly was not simply linked to the deals of 1974-75.
Politicians and businessmen move on; they don’t linger the way Chirac did. Partly because of the breadth of the relationship Chirac and Hussein had created in a relatively short period of time and the obvious warmth of their personal ties, there was intense speculation about the less visible aspects of the relationship. For example, one unsubstantiated rumor that still can be heard in places like Beirut was that Hussein helped to finance Chirac’s run for mayor of Paris in 1977, after he lost the French premiership.
Another, equally unsubstantiated rumor was that Hussein had skimmed funds from the huge amounts of money that were being moved around, and that he did so with Chirac’s full knowledge. There are endless rumors, all unproven and perhaps all scurrilous, about the relationship.
Some of these might have been moved by malice, but they also are powered by the unfathomability of the relationship and by Chirac’s willingness to publicly affirm it. It reached the point that Iranians referred to Chirac as “Shah-Iraq” and Israelis spoke of the Osirak reactor as “O-Chirac.”
Indeed, as recently as last week, a STRATFOR source in Lebanon reasserted these claims as if they were incontestable. Innuendo has become reality. Former French President Valery Giscard d’Estaing, who held office at the time of the negotiations with Iraq, said in 1984 that the deal “came out of an agreement that was not negotiated in Paris and therefore did not originate with the president of the republic.” – Strafor, Feb 2003
Maybe Mr. Chirac also miscalculated and misread President Bush #43.
Middle East Mess Solely the Bush Administration’s Fault
Nevertheless, we are not trying to dismiss or place the blame of the Iraq war and the subsequent destabilization of the Middle East and the mess it made on Jacques Chirac or France, for that matter. The blame lies solely, and unequivocally, on the Cheney wing of the Bush Administration, in our opinion.
We are very confident in our source and just thought we would throw it out there and maybe some young investigative reporter will pick it up and run with it.
We do like France’s new President. The new Leader of the Free World, in our opinion.
An Aside: Wag The Dog in the Middle East?
Interesting the U.S. ambassador mentioned the price of oil in her 1990 meeting with Saddam,
We have considerable sympathy for your quest for higher oil prices
– Ambassador Glaspie
After the invasion of Kuwait, the average monthly price of oil rose from $17 per barrel in July 1990 to $36 per barrel in October.
With the Middle East now blowing up, the price of oil in free fall, and Saudi and Iran at each other’s throat, we wouldn’t be surprised to see a major “wag the dog” event in the Persian Gulf sometime soon. Makes us very nervous holding shorts in oil.
If the U.S. ambassador in 1990 was sympathetic to Iraq’s concerns over the oil price, how much more is the State Department currently going to be with an “oil man” as Secretary of State?
In my prior life I used to trade emerging market (EM) bonds and came up with the following analytical framework using options analysis to understand and teach the basic fundamental principles of how to value EM hard currency bonds. The analysis is relatively crude and simplistic but a very powerful tool to internalize the understanding of valuing emerging market fixed-income securities.
The analysis is timely given Argentina’s recent sale of a 100-year sovereign bond.
Option Based Analytical Framework
Because the value of corporate securities is, in effect, a contingent claim on the firm’s value, options analysis can be applied to construct an alternative analytical framework to determine and understand relative value. Equity is essentially the residual claim on the value of the firm after all liabilities have been paid. If bankruptcy occurs, equity holders receive nothing.
The economic return to equity holders is therefore the maximum of zero, or the total value of the firm’s assets less all outstanding debt liabilities. The equity claim is thus a call option on the value of the firm with the strike price equivalent to value of the outstanding debt.
Corporate Bonds As A Hybrid
In the event of bankruptcy, equity investors are off the hook if the value of the corporation falls below zero when liabilities exceed assets, but they lose the entire value of their claims on the firm, however. The limited liability of a common stockholder therefore corresponds to the limited downside of a holder of a call option.
Using this framework, corporate bonds are then effectively a hybrid of a risk-free bond and a series of annual puts written on the value of the firm. The strike price of the put is also equivalent the point at which the firm’s assets equal its debt outstanding.
If the value of the firm’s assets fall below its debt liabilities, the loss to the bondholder is similar to the loss of a writer of a put option. The loss to the bond holder is the difference between the liquidation value of the firm and value of the debt outstanding. The bond’s credit spread over the comparable risk-free rate is equivalent to the annual option premium bondholders receive for writing the implied put.
Note this a very simplistic analytical framework and ignores many factors such as the firm’s capital structure, for example, but has very powerful conceptual value. The same analysis can be applied to credit default swaps (CDS).
Application to Emerging Market Sovereign Bonds
The option-based framework can be extended to better understand the nature of sovereign risk, particularly transfer risk, inherent in emerging market hard currency bonds. The option based analysis is modified, however, from a balance sheet perspective to a cash flow perspective. Lack of clear international bankruptcy proceedings and access to the sovereign’s balance sheet limits the analysis to a flow (cash flow) versus stock (balance sheet) variables.
Emerging market dollar denominated sovereign bonds can similarly be viewed as a hybrid of a risk-free bond and a series of puts written on the level of the international reserves of the issuer country. This assumes all risk factors, including political, economic, willingness to pay, and the global macro factors are reflected in the level of the country’s international reserve position. Not an unrealistic assumption as material changes in these risk variables will impact capital flows and the country’s reserve position.
Strike Price On International Reserves
The strike price of the put is the minimum level of reserves to cover the country’s debt service. The credit spread on the emerging market bonds is therefore the option premium for writing the annual put on FX reserves.
As the reserve position declines, for example, and moves closer to the strike price, or minimum level of reserves, the put premium or credit spread should increase. If reserves move below the minimum level, the loss to the bondholder is the same as the loss on the put, or difference between debt service actually paid and the contractual payment.
Conversely, as reserves rise to a debt sustainable level, the put moves further out-of-the-money and the options premium or credit spread declines. The expected volatility of capital flows, the country’s foreign exchange reserve earnings, and import volatility will also affect the premium value or credit spread.
The figure below shows the annual payoff of each put written on the value of the country’s foreign exchange reserves. As reserves fall close to or below the minimum level for debt service, the put moves in-the-money.

Default
If the country defaults calculating the recovery value is much more difficult than in a corporate default as bondholders rarely have access to a balance sheet and a bankruptcy judge. The workout is subject to good faith negotiations and the estimated debt servicing capacity of the country. Fairly complicated.
We’ve done some back of the envelope calculations on a 10-year bond with a credit spread of 330 bps at issuance. The present value of the credit spreads or “put option premiums” is about 30 percent of the value of the bond.
Large Increase In International Reserves
From the mid-1990’s to around 2014, the world experienced a large increase in international reserves. This was the result of three major factors.
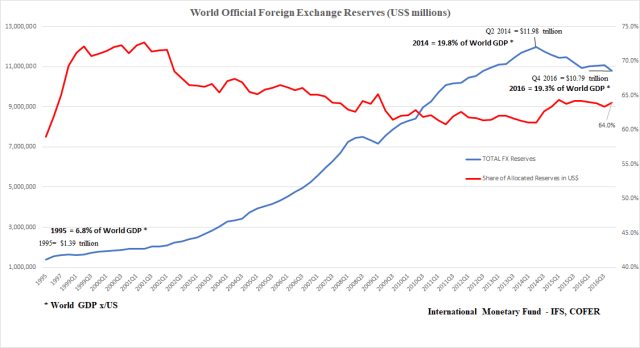
First was the rise of China as an export powerhouse and its massive build up of FX reserves.
Change in FX Regimes
Second, after the Mexican peso and Asian Financial crises of the mid-to late 1990’s, emerging market policy makers learned a hard lesson that running large current account deficits as the result of strengthening currencies could lead to a very destabilizing and costly balance of payments crisis. Policy makers became very vigilant not to allow their currencies to become overvalued and intervened in their foreign exchange markets purchasing the dollars and thus increasing their reserve positions.
Third, the U.S. began to run larger current account deficits and effectively monetized them though relatively easy monetary policy. The result was an abundance of excess dollars in the international financial system, which found their way into the official accounts of foreign central banks.
Tight Spreads and High International Reserves
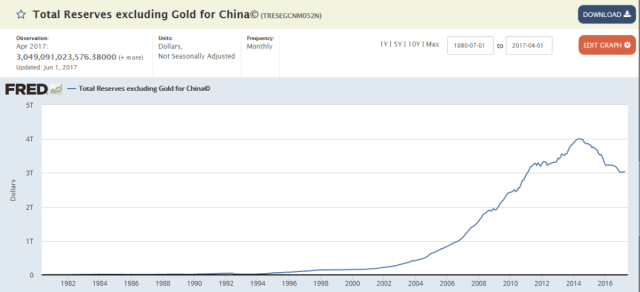
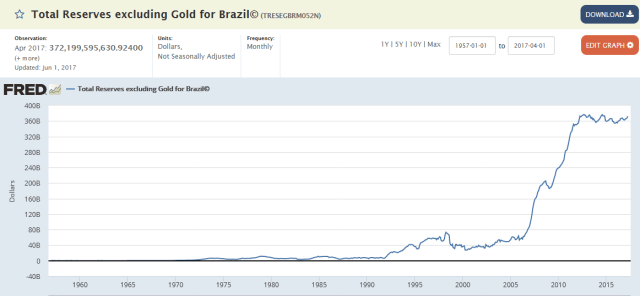
Using the above analysis makes it easier to understand why EM sovereign dollar bonds are trading so tight, or so wide, for that matter. Just take a look at the following time series of the international reserve position of some of the major emerging market countries.
.
.

.

.

Click on table to enlarge and for better resolution

The last words my father spoke to me before he died in 1996 was, [“Gregor], somebody is going to have to do something to help the poor.”
Fast forward to 2017. Never has the wealth gap in America been so wide. This creates the initial conditions for a very uncertain and potentially unstable and explosive political and economic future.
I just woke up, for example, to see these two articles juxatposed on my news aggregator.
One article is about how 13 million American children go to bed hungry every night and the other is about the 1 percenters, who are now taking helicopters to their Hampton summer homes to avoid traffic. What in the hell is happening to our country?
Average wealth has increased over the past 50 years, but it has not grown equally for all groups. Between 1963 and 2013, families near the bottom of the wealth distribution (those at the 10th percentile) went from having no wealth on average to being about $2,000 in debt, those in the middle roughly doubled their wealth—mostly between 1963 and 1983, families near the top (at the 90th percentile) saw their wealth quadruple, and the wealth of those at the 99th percentile—in other words, those wealthier than 99 percent of all families—grew sixfold. – Urban Institute
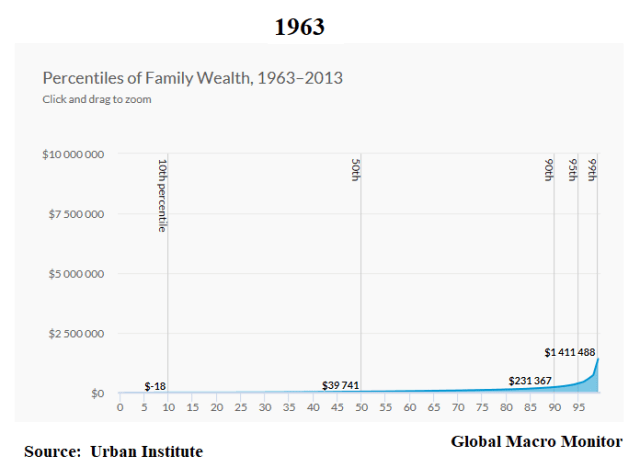
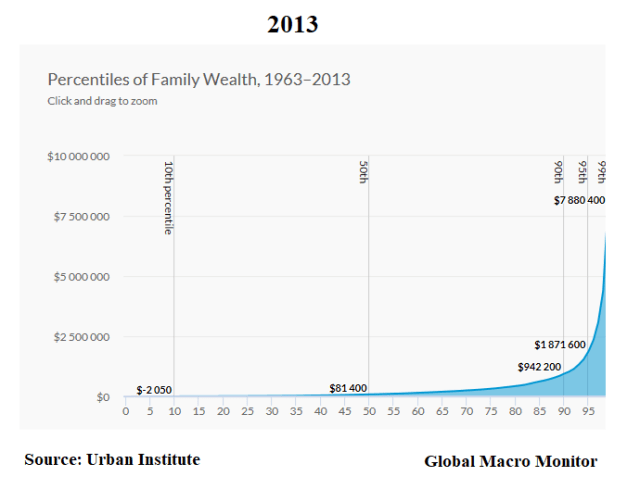
The current data is much worse as the above doesn’t take into account the massive runup in asset prices over the past 3 1/2 years.
Philanthropic 1 Percenters, But……..
I know many 1 percenters who are great and generous people and give so much in an effort reduce poverty. Paul Tudor Jones’ Robin Hood Foundation, for example, is God’s work. Though they make a difference in many individual lives, these good works can only go so far and only make just a small dent in the problem of our vanishing middle class and increasing American poverty rate.
It’s the policies, Stupid!
The kumbaya moment Congress is now experiencing after the shooting of its Republican congressional members last week now needs to be translated into action.
Policy changes are imperative if we are going to really — first, we must decide if we want to — make a change. It’s time to move away from the ugly and tired dialectic of “tax cuts for the rich and government help for the poor.” Everything must change.
Creative public policy and a change of thinking are the only hope, comrades.
Here is one example,
The United States exports more food than any other country in the world. So why do families with children have trouble getting enough food in such a prosperous nation?
“The non-politcal answer, to me, is greed and government,” Stallings said.
“There’s too many government health restrictions that force restaurants to throw away food” instead of donating it to the needy. “It’s also greed: We’re not helping our neighbors.” -Bryan Stallings, CNN
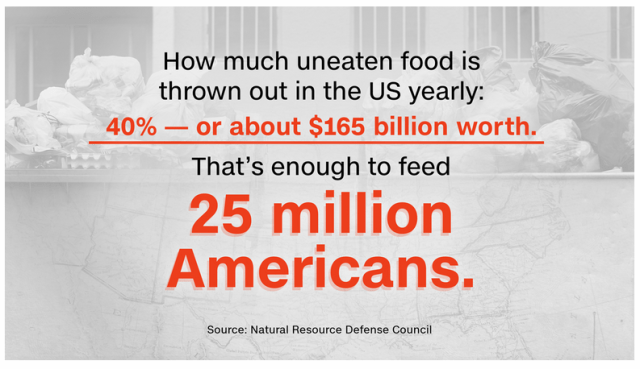
Wow! We trash 40 percent of the food we produce.
Lessons From The Godfather
Special interests will surely stand in the way of the much needed new policy thinking/making, including from reforming education to allowing restaurants to donate their food to the needy, for example. So how do we deal with them?
Take a lesson from the Godfather and mayor of Chicago, Rahm Emanuel, when he was Chief of Staff for President Obama and negotiating the bailout of the auto companies. Some in the bailout group raised concerns about pushback from the United Auto Workers.
To which the Godfather replied,
F$*K the UAW – Rahm Emanuel
To which we say,
F$*K the Special Interests – Global Macro Monitor
My God, we are talking about hungry children, for Pete’s sake.
Happy Father’s Day
Before hitting the hay we need to call a big B.S. on the bastard ‘bots from Rip (Off) City. They screwed us again yesterday (June 14) in crude oil futures.
First, before we get into the trade, a little background.
We have posted about our experiences of being ripped off by these “so-called” trading ‘bots, who prey and stalk the markets, looking to pick-off traders through blatant market manipulation. Flash crash, my arse.
We put on a short position in nattie Thursday night before driving back from Sacramento to the Bay Area. We checked the market at dinner and see its down about 1 percent, we feel happy and give high fives. Then we look at the position and we have none!
It was taken out (buy stop) as a Seek and Destroy Bot came in around around 9 pm, guns the market to the upside to take out all the buy stops of the short sellers, then turns around and guns it to the downside to destroy all sell stops of longs. Finally, moves the market back to where it was before all the nonsense began. Not a bad day’s work for the robot. – GMM, January 2017
But, this is the doozy:
Remember the AP Twitter hack in April 2013, where,
“Wall Street collided with social media on Tuesday, when a false tweet from a trusted news organization sent the US stock market into free fall.
The 143-point fall in the Dow Jones industrial average came after hackers sent a message from the Twitter feed of the Associated Press, saying the White House had been hit by two explosions and that Barack Obama was injured. The fake tweet, which was immediately corrected by Associated Press employees, caused a sensation on Twitter and in the stock market.” – The Guardian
That one cost us big as our long stops were hit. – GMM, January 2017
Never heard a word after that ugly April day in 2013. Why didn’t the SEC follow up on this or keep the public posted on their investigations?
Was it a Russian 400 pound hacker/day trader sitting on his bed in New Jersey parlaying the hack into an easy money short trade? We have zero doubt it was “financial nefarious” and the AP hack was done to manipulate the market. Somebody made a ton of money, some of it ours.
To be fair, perhaps the SEC did follow up and informed the public of its findings and we just missed it.
Wednesday’s Crude Oil Trade
As you know crude oil has been trading very ugly since OPEC announced the externsion of their production cuts, falling more than 10 percent from the May 25th recent high.
If the market can’t go up on an OPEC cut, we figure its time to get shorty crude oil. Usually, we don’t go into an inventory number with a sizable position, but given the ugly API inventory data on Tuesday and the strong downtrend, we decide to keep the short on through EIA , which is released at 10:30 AM eastern.
About 10 seconds before the release the crude price gaps up $.50 taking out our buy stop and then immediately gaps down on the number. It was too fast for a human to execute and was definitely a machine.
Check out Wednesday’s one minute price chart,

Note the big spike up at just before 9:30 AM central. It wasn’t a headfake as it took place just a few seconds before the data release. We put the short back on about a $.70 lower from where the machine flogged us. Expensive. It cost us (both accounting and economic losses) around $5K. Bastard ‘bots!
An aside, crude now feels kind of sold out to us.
We’ll admit maybe some bad trading on our part — leaving a stop hanging out there before a data release — but this is TOTAL BULLSHIT. Where in the hell is the CFTC and SEC?
No wonder the hoi polloi are starting to revolt.
Beware the “American Street.”
Long water cannons/short John Henry, the Steel Driving Man.
Don’t you just love his homework assignment?