Growth looks good – FT

Published on Jan 3, 2017

John Authers looks at encouraging signs of strength from the US to China, while the strengthening dollar may signal problems for emerging markets.

► Subscribe to FT.com here: http://on.ft.com/2eZZoLI

Posted in Economics, Uncategorized | Tagged , , | Leave a comment

2017 Fastest Growing Economies

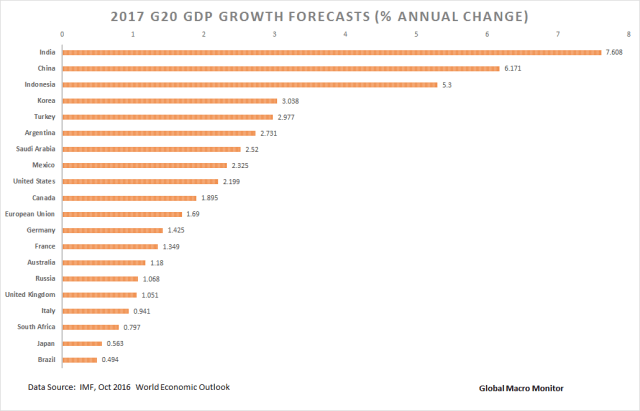
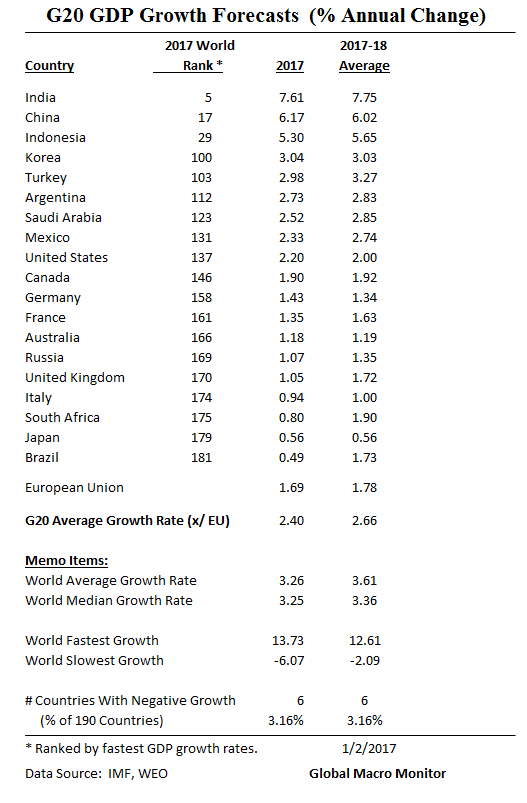
New year, time to look forward.   Which countries are expected to grow the fastest in 2017?

We have ranked the world’s country 2017 GDP forecasts in the ginormous table below.  The data are from the October 2016 IMF’s World Economic Outlook.   A little dated, especially, post-Trump, but gives a feel of the how economies around the world are expected to grow.

But, first, check out the G20.

gdp-growth_g20_chart

gdp-growth_g20_table

gdp-growth_world-rank_2017


Posted in Uncategorized | Tagged , , , , | 19 Comments

Seek and Destroy Trading Bots Killing Us

We are mad as hell.  The markets are rigged,

It had enabled a massive amount of predatory trading and had institutionalized a systemic and totally unnecessary unfairness in the market and, in the bargain, rendered it less stable and more prone to flash crashes and outages and other unhappy events. – Michael Lewis,  Vanity Fair

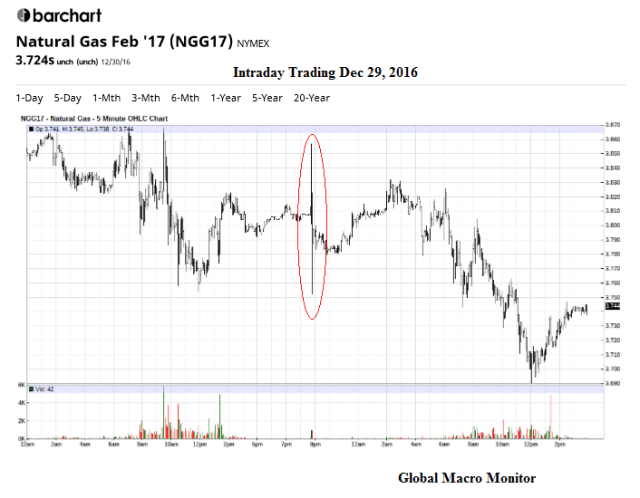
Check out the price action in natural gas futures last Thursday evening, the same night of the dollar flash crash.   We are sick and tired of this blatant market manipulation and a lot poorer from it.

We put on a short position in nattie Thursday night before driving back from Sacramento to the Bay Area.   We checked the market at dinner and see its down about 1 percent, we feel happy and give high fives.   Then we look at the position and we have none!

It was taken out (buy stop) as  a Seek and Destroy Bot came in around around 9 pm, guns the market to the upside to take out all the buy stops of the short sellers, then turns around and guns it to the downside to destroy all sell stops of longs.  Finally,  moves the market back to where it was before the all the nonsense began.  Not a bad day’s work for the robot.

Nattie’s total move in those few minutes last Thursday evening was almost 4 percent or almost 7 percent of the entire 59 percent move up in natural gas futures for the entire year.  This is total B.S.!

nattie_manip

This is not the first and only time we have lost money due to market manipulation.   Remember the AP Twitter hack in April 2013, where

Wall Street collided with social media on Tuesday, when a false tweet from a trusted news organization sent the US stock market into free fall.

The 143-point fall in the Dow Jones industrial average came after hackers sent a message from the Twitter feed of the Associated Press, saying the White House had been hit by two explosions and that Barack Obama was injured. The fake tweet, which was immediately corrected by Associated Press employees, caused a sensation on Twitter and in the stock market.  – The Guardian

sp500_flash-crash

That one cost us big as our long stops were hit.

It really angers us that the CFTC and SEC are not more aggressive on this crap.   Didn’t we just have a Presidential election on all things rigged?

But, hey, we have the best government money can buy and, it seems to us, big money has bought the government agencies charged with protecting the public and that “bought” allows the Bots to seek and destroy the little guys like us, no?

It also really pisses us off when we hear that the exchanges sell the stop-loss order info to the type of firms engaged in this blatant market manipulation.  Makes us kind of feel like Gregor Samsa.  Kafkaesque!

We don’t want to engage in fake news so don’t quote us on the exchange selling info to the HFTs.  We cannot confirm it at this moment and will get back to you on this one.

We can no longer spend 23/5 watching the markets, which seems to be the necessary condition these days to protect yourself,  and are reassessing and rethinking are long-term strategy for the new year.

John Henry,  we feel your pain!

John Henry: The Steel Driving Man

A West Virginia Legend

retold by

S.E. Schlosser

Now John Henry was a mighty man, yes sir. He was born a slave in the 1840’s but was freed after the war. He went to work as a steel-driver for the Chesapeake & Ohio Railroad, don’t ya know. And John Henry was the strongest, the most powerful man working the rails.

John Henry, he would spend his day’s drilling holes by hitting thick steel spikes into rocks with his faithful shaker crouching close to the hole, turning the drill after each mighty blow. There was no one who could match him, though many tried.

Well, the new railroad was moving along right quick, thanks in no little part to the mighty John Henry. But looming right smack in its path was a mighty enemy – the Big Bend Mountain. Now the big bosses at the C&O Railroad decided that they couldn’t go around the mile and a quarter thick mountain. No sir, the men of the C&O were going to go through it – drilling right into the heart of the mountain.

A thousand men would lose their lives before the great enemy was conquered. It took three long years, and before it was done the ground outside the mountain was filled with makeshift, sandy graves. The new tunnels were filled with smoke and dust. Ya couldn’t see no-how and could hardly breathe. But John Henry, he worked tirelessly, drilling with a 14-pound hammer, and going 10 to 12 feet in one workday. No one else could match him.

Then one day a salesman came along to the camp. He had a steam-powered drill and claimed it could out-drill any man. Well, they set up a contest then and there between John Henry and that there drill. The foreman ran that newfangled steam-drill. John Henry, he just pulled out two 20-pound hammers, one in each hand. They drilled and drilled, dust rising everywhere. The men were howling and cheering. At the end of 35 minutes, John Henry had drilled two seven foot holes – a total of fourteen feet, while the steam drill had only drilled one nine-foot hole.

John Henry held up his hammers in triumph! The men shouted and cheered. The noise was so loud, it took a moment for the men to realize that John Henry was tottering. Exhausted, the mighty man crashed to the ground, the hammer’s rolling from his grasp. The crowd went silent as the foreman rushed to his side. But it was too late. A blood vessel had burst in his brain. The greatest driller in the C&O Railroad was dead.

Some folks say that John Henry’s likeness is carved right into the rock inside the Big Bend Tunnel. And if you walk to the edge of the blackness of the tunnel, sometimes you can hear the sound of two 20-pound hammers drilling their way to victory over the machine.

Posted in Technical Analysis, Uncategorized | Tagged , , , | 23 Comments

How Is That Reagan-Trump S&P500 Analog Working Out?

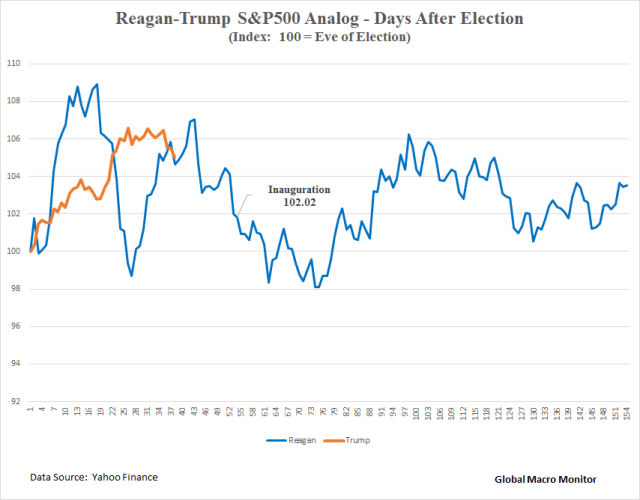
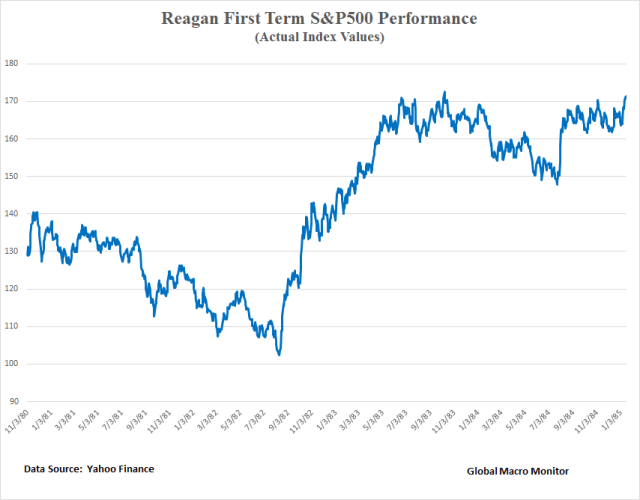
So far, at the close of 2016,  the Trump S&P500 is outperforming  the Reagan S&P500 by 0.38 percent, 38 days after the close of their respective election days.  The Trump bump has been a relatively steady climb before rolling over last week whereas a much more volatile S&P 40 days after the Reagan election.

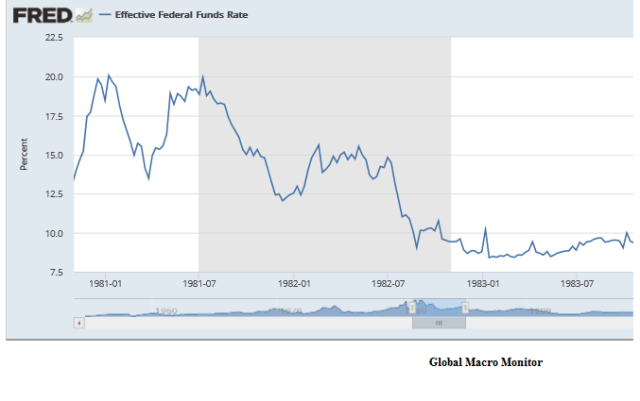
Note also the Reagan bull market really didn’t begin until a year and a half into his Administration.  The S&P500 continued to slide after his inauguration as the economy was in the throes of a deep recession.   Monetary policy began to ease — see chart below where Fed Funds rate fell over 1,ooo bps from July 1981 to August 1982 * —  and the stock market finally bottomed toward the end of the recession in the fall of 1982.

The Reagan-Trump Analog is completely useless, in our opinion, as the relative  macroeconomic initial conditions at the advent of their two Presidencies are entirely different.   Nevertheless,  a fun tracking exercise and we do expect a little more give back in the S&P500 in the next month.  We don’t expect the almost 30 percent high-to-low give back in the first year and half of the new Administration.

President Trump will inherit and entirely different economy than President Reagan.   Stay tuned.

* Fed funds was not a target variable at the time, but does reflect monetary conditions.

reagan-v-trump_reagan

reagan-v-trump_reagan_1st-termreagan-v-trump_effective-fund-funds

Posted in Equities, Uncategorized | Tagged , , | Leave a comment

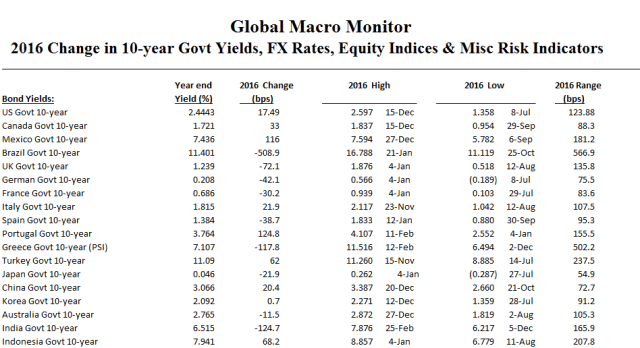
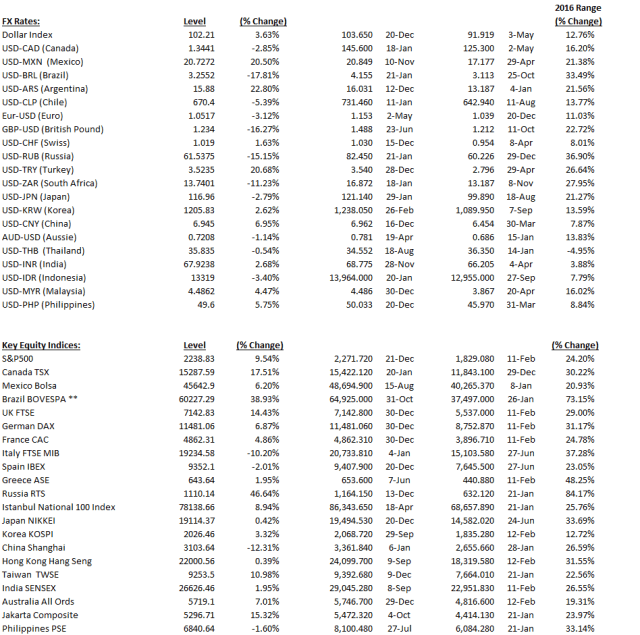
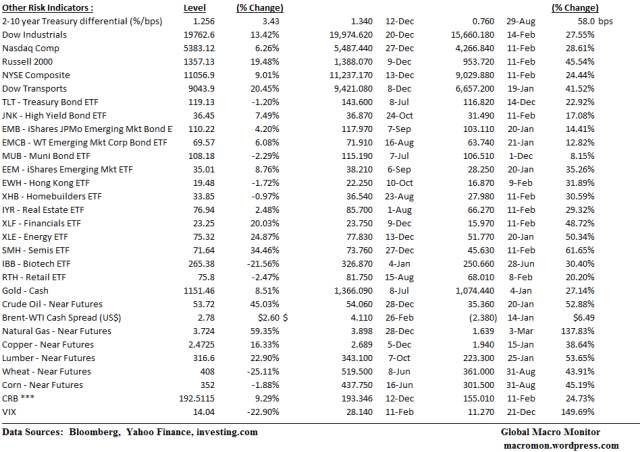
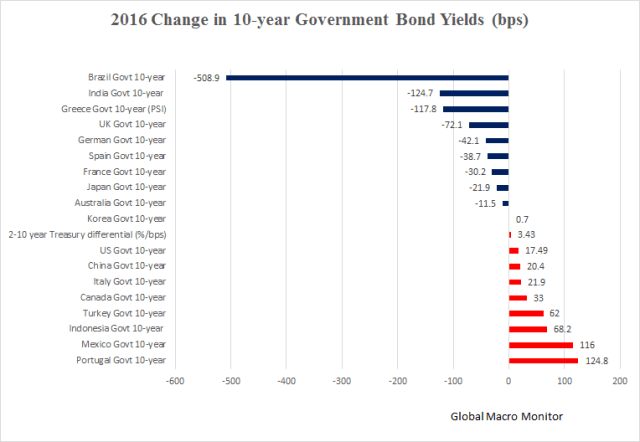
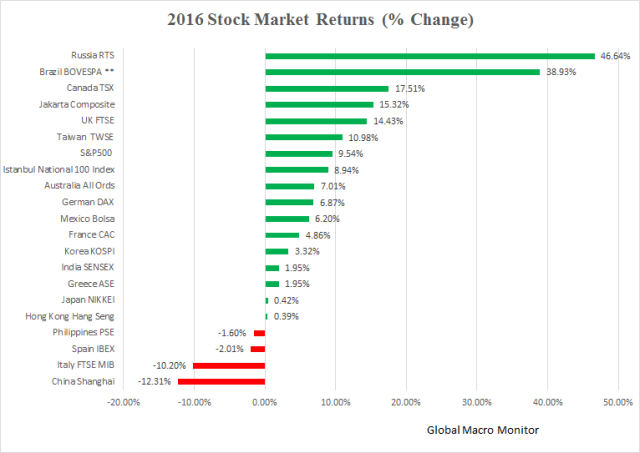
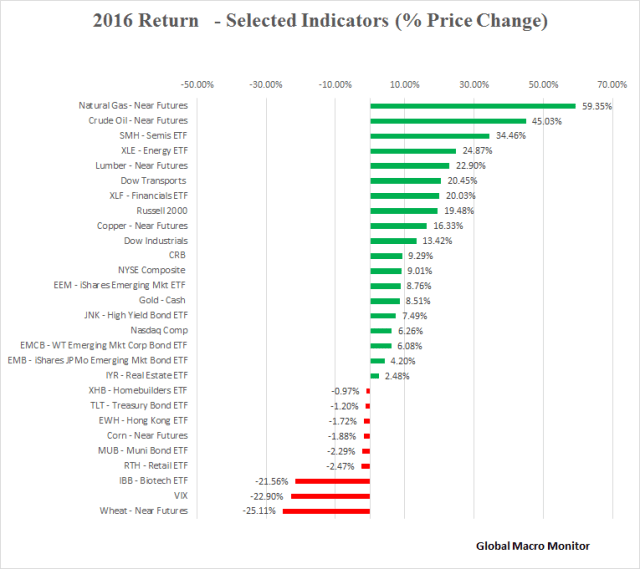
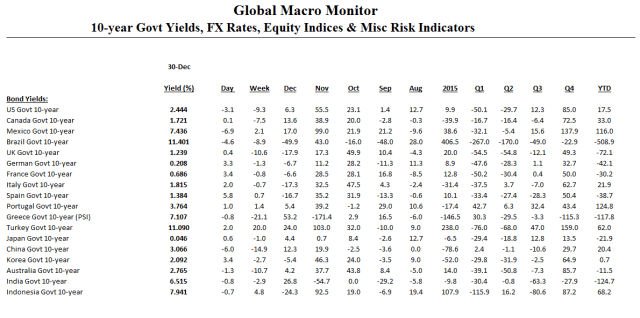
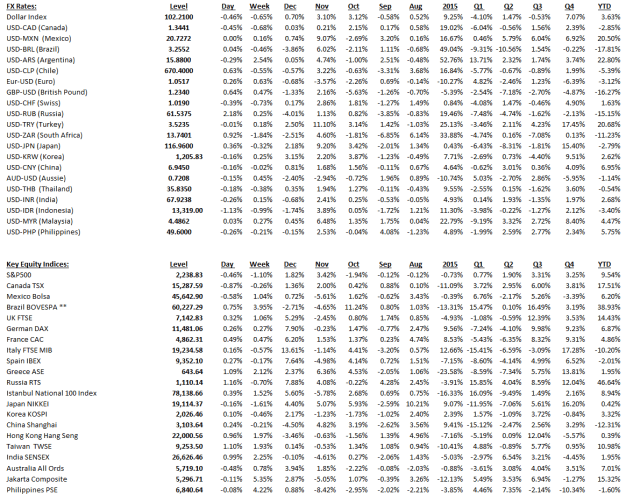
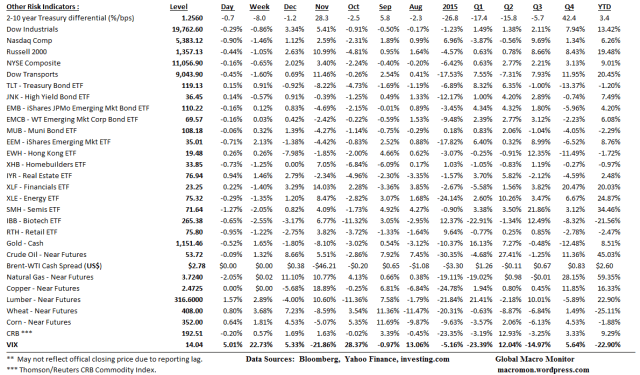
Global Macro Data Year in Review

Click on table to enlarge and for better resolution

2016_riskmon_12016_riskmon_22016_riskmon_3

2016_bonds2016_stocks2016_selected

Posted in Daily Risk Monitor, Uncategorized | Tagged , , , , , , | Leave a comment

The biggest moment of 2017: Donald Trump’s inauguration – Economist

Published on Dec 30, 2016

On January 20th 2017, the eyes of the world will be on Donald Trump as he takes the oath of office and is sworn in as America’s 45th president. The political tremors will reverberate around the world. But it is inauguration day itself that tops our list of the coming year’s biggest talking points.

Click here to subscribe to The Economist on YouTube: http://econ.trib.al/rWl91R7

Posted in Economics, Policy, Politics, Uncategorized | Tagged , , | Leave a comment

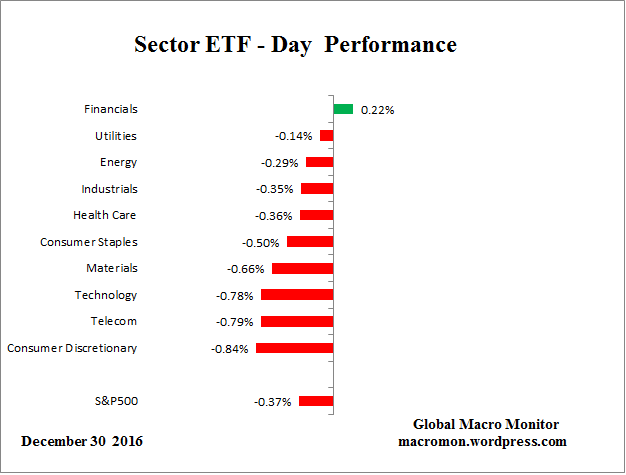
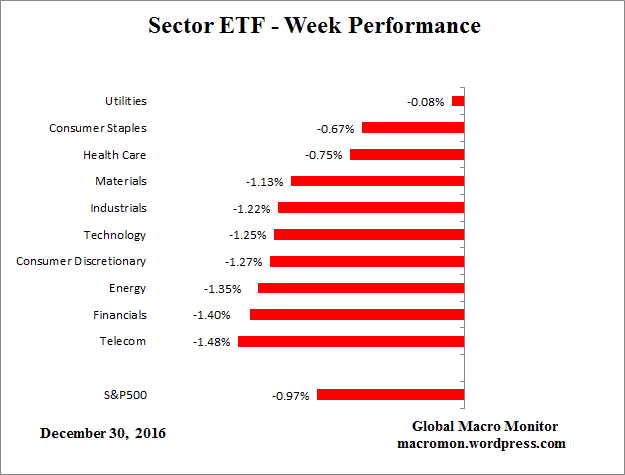
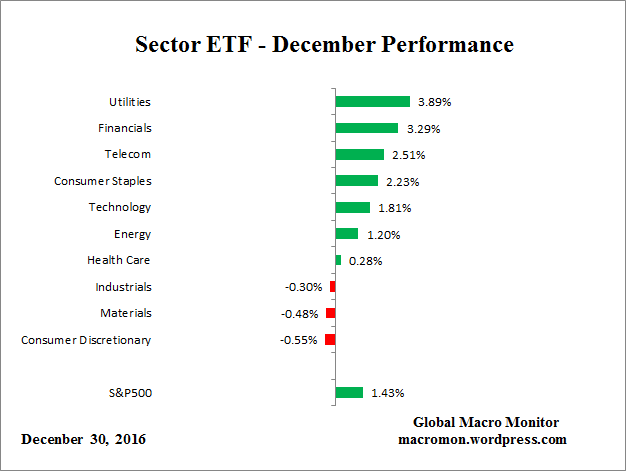
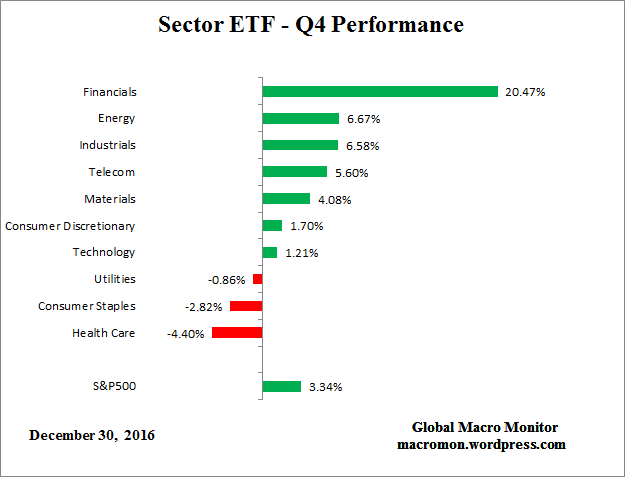
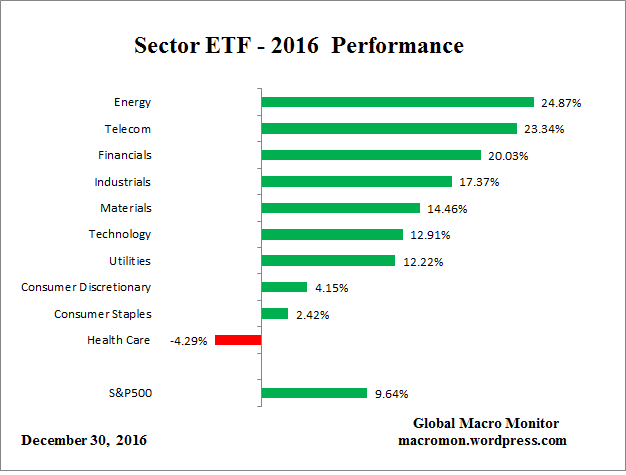
US Sector ETF Performance – Dec 30

etf_detf_wetf_metf_q4etf_ytd

Posted in Sector ETF Peformance, Uncategorized | Tagged , | Leave a comment

Daily Risk Monitor – December 30

Click on table to enlarge and for better resolution

riskmon_1riskmon_2riskmon_3

Posted in Daily Risk Monitor | Tagged , , , , , | Leave a comment

History Shows Why Prognosticators Should Be Discounted

It is the end of the year and prognosticators are crawling out of the woodwork.  So, it’s time to repost a piece from Global Macro Monitor years’ past.

Prophets are usually false, and that includes us.  After all, look at where we thought the Gold Miners Index (GDX) would at the end of the year?    Trading is calculated risk and if you stick with a forecast or outlook that biases your money management,  you’re dead.   Punto

Happy New Year!

History Shows Why Prognosticators Should Be Discounted

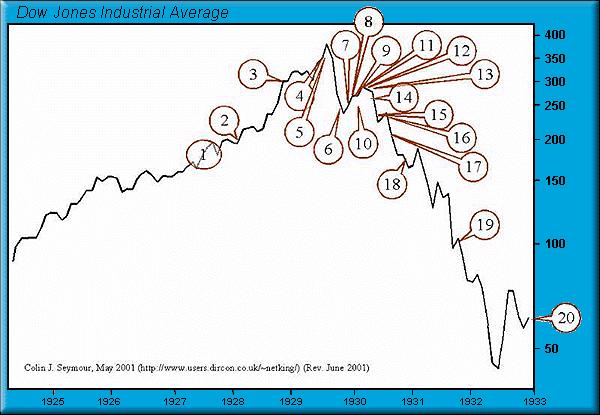
1927-1933 Chart of Pompous Prognosticators

1.  “We will not have any more crashes in our time.”
– John Maynard Keynes in 1927

2.  “I cannot help but raise a dissenting voice to statements that we are living in a fool’s paradise, and that prosperity in this country must necessarily diminish and recede in the near future.”
– E. H. H. Simmons, President, New York Stock Exchange, January 12, 1928

“There will be no interruption of our permanent prosperity.”
– Myron E. Forbes, President, Pierce Arrow Motor Car Co., January 12, 1928

3.  “No Congress of the United States ever assembled, on surveying the state of the Union, has met with a more pleasing prospect than that which appears at the present time. In the domestic field there is tranquility and contentment…and the highest record of years of prosperity. In the foreign field there is peace, the goodwill which comes from mutual understanding.”  – Calvin Coolidge December 4, 1928

4.  “There may be a recession in stock prices, but not anything in the nature of a crash.”
– Irving Fisher, leading U.S. economist , New York Times, Sept. 5, 1929

5.  “Stock prices have reached what looks like a permanently high plateau. I do not feel there will be soon if ever a 50 or 60 point break from present levels, such as (bears) have predicted. I expect to see the stock market a good deal higher within a few months.”
– Irving Fisher, Ph.D. in economics, Oct. 17, 1929

“This crash is not going to have much effect on business.”
– Arthur Reynolds, Chairman of Continental Illinois Bank of Chicago, October 24, 1929

“There will be no repetition of the break of yesterday… I have no fear of another comparable decline.”
– Arthur W. Loasby (President of the Equitable Trust Company), quoted in NYT, Friday, October 25, 1929

“We feel that fundamentally Wall Street is sound, and that for people who can afford to pay for them outright, good stocks are cheap at these prices.”
– Goodbody and Company market-letter quoted in The New York Times, Friday, October 25, 1929

6.  “This is the time to buy stocks. This is the time to recall the words of the late J. P. Morgan… that any man who is bearish on America will go broke. Within a few days there is likely to be a bear panic rather than a bull panic. Many of the low prices as a result of this hysterical selling are not likely to be reached again in many years.”
– R. W. McNeel, market analyst, as quoted in the New York Herald Tribune, October 30, 1929

“Buying of sound, seasoned issues now will not be regretted”
– E. A. Pearce market letter quoted in the New York Herald Tribune, October 30, 1929

“Some pretty intelligent people are now buying stocks… Unless we are to have a panic — which no one seriously believes, stocks have hit bottom.”
– R. W. McNeal, financial analyst in October 1929

7.  “The decline is in paper values, not in tangible goods and services…America is now in the eighth year of prosperity as commercially defined. The former great periods of prosperity in America averaged eleven years. On this basis we now have three more years to go before the tailspin.”
– Stuart Chase (American economist and author), NY Herald Tribune, November 1, 1929

“Hysteria has now disappeared from Wall Street.”
– The Times of London, November 2, 1929

“The Wall Street crash doesn’t mean that there will be any general or serious business depression… For six years American business has been diverting a substantial part of its attention, its energies and its resources on the speculative game… Now that irrelevant, alien and hazardous adventure is over. Business has come home again, back to its job, providentially unscathed, sound in wind and limb, financially stronger than ever before.”
– Business Week, November 2, 1929

“…despite its severity, we believe that the slump in stock prices will prove an intermediate movement and not the precursor of a business depression such as would entail prolonged further liquidation…”  – Harvard Economic Society (HES), November 2, 1929

8.  “… a serious depression seems improbable; [we expect] recovery of business next spring, with further improvement in the fall.” – HES, November 10, 1929

“The end of the decline of the Stock Market will probably not be long, only a few more days at most.”
– Irving Fisher, Professor of Economics at Yale University, November 14, 1929

“In most of the cities and towns of this country, this Wall Street panic will have no effect.”
– Paul Block (President of the Block newspaper chain), editorial, November 15, 1929

“Financial storm definitely passed.”
– Bernard Baruch, cablegram to Winston Churchill, November 15, 1929

9.  “I see nothing in the present situation that is either menacing or warrants pessimism… I have every confidence that there will be a revival of activity in the spring, and that during this coming year the country will make steady progress.”
– Andrew W. Mellon, U.S. Secretary of the Treasury December 31, 1929

“I am convinced that through these measures we have reestablished confidence.”
– Herbert Hoover, December 1929

“[1930 will be] a splendid employment year.”
– U.S. Dept. of Labor, New Year’s Forecast, December 1929

10. “For the immediate future, at least, the outlook (stocks) is bright.”
– Irving Fisher, Ph.D. in Economics, in early 1930

11.  “…there are indications that the severest phase of the recession is over…”
– Harvard Economic Society (HES) Jan 18, 1930

12.  “There is nothing in the situation to be disturbed about.”
– Secretary of the Treasury Andrew Mellon, Feb 1930

13.  “The spring of 1930 marks the end of a period of grave concern…American business is steadily coming back to a normal level of prosperity.”
– Julius Barnes, head of Hoover’s National Business Survey Conference, Mar 16, 1930

“… the outlook continues favorable…”  – HES Mar 29, 1930

14.  “… the outlook is favorable…”  – HES Apr 19, 1930

15.  “While the crash only took place six months ago, I am convinced we have now passed through the worst — and with continued unity of effort we shall rapidly recover. There has been no significant bank or industrial failure. That danger, too, is safely behind us.”
– Herbert Hoover, President of the United States, May 1, 1930

“…by May or June the spring recovery forecast in our letters of last December and November should clearly be apparent…”  – HES May 17, 1930

“Gentleman, you have come sixty days too late. The depression is over.”
– Herbert Hoover, responding to a delegation requesting a public works program to help speed the recovery, June 1930

16.  “… irregular and conflicting movements of business should soon give way to a sustained recovery…”  – HES June 28, 1930

17.  “… the present depression has about spent its force…” – HES, Aug 30, 1930

18. “We are now near the end of the declining phase of the depression.”- HES Nov 15, 1930

19.  “Stabilization at [present] levels is clearly possible.” – HES Oct 31, 1931

20.  “All safe deposit boxes in banks or financial institutions have been sealed… and may only be opened in the presence of an agent of the I.R.S.” – President F.D. Roosevelt, 1933

Colin J. Seymour, June 2001
http://www.users.dircon.co.uk/~netking
20 June 2001

Posted in Economist, Uncategorized | Tagged , | Leave a comment

Reagan v Trump Macro Initial Conditions

We hear lots of talk these days about,  Why Donald Trump’s Market Rally Echoes Ronald Reagan’s.   

We are big fans of Chaos Theory,

Chaos theory is a branch of mathematics focused on the behavior of dynamical systems that are highly sensitive to initial conditions—a response popularly referred to as the butterfly effect.[1] Small differences in initial conditions (such as those due to rounding errors in numerical computation) yield widely diverging outcomes for such dynamical systems, rendering long-term prediction of their behavior impossible in general.

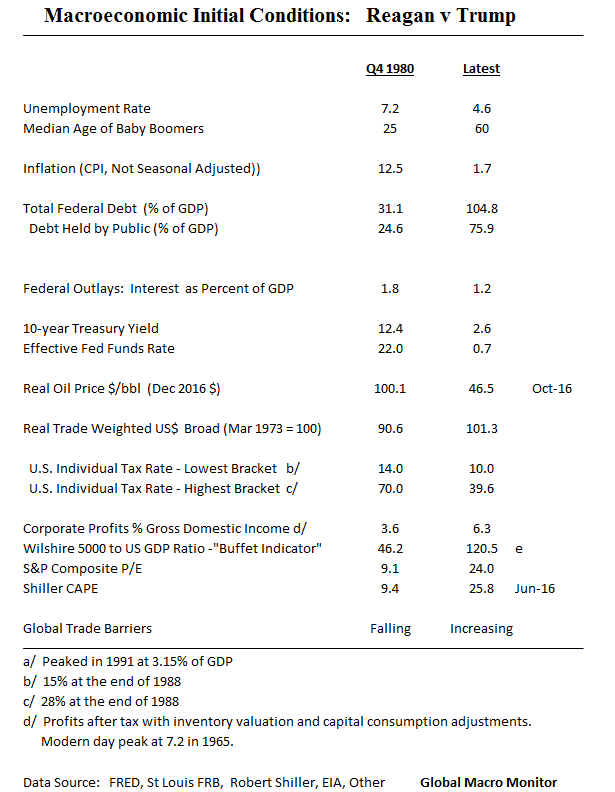
So we thought we’d take a look at the macroeconomic initial conditions at the start of the Reagan Presidency versus the incoming Trump Presidency.

Check out the data:

reagan-v-trump_initial-conditions

In most all macro categories that we have have researched here,  the initial conditions just aren’t there for a Reagan type bull market, in our opinion.  First, and foremost, are the monetary headwinds.

Monetary Conditions
Reagan began his Presidency with interest rates nowhere to go but south with a 22 percent Fed Funds rate and a 10-year Treasury yield of 12 1/2 percent.  Though interest rates were not the policy target of the Fed at the time,  just several months into the Reagan Presidency the 35-year bond bull market ignited and drove almost all asset prices from real estate to stocks, including the expansion of the price to earnings multiple.

The polar opposite monetary conditions exist at the advent of the Trump Presidency.  Interest rates have nowhere to go but north, we believe,  especially if Mr. Trump’s fiscal policy is implemented.

Unemployment
Mr. Trump will not have the labor slack and surplus to draw upon to drive economic growth.   The country is pretty much at full employment although the level of tautness in the labor market can be debated. This risks much higher inflation than anticipated if his policies are passed and thus a more aggressive Fed.  Also note the aging of the baby boom generation, which has driven much of the growth over the past 30 years.

Total Debt
President Reagan began his Presidency with a relatively small stock of debt.   Mr. Trump will inherit a debt-to-GDP ratio almost three times that of President Reagan.  This leaves less room for deficits as a result of his tax cuts and increased spending.   The Trump plan is to increase economic growth and thus tax revenues through supply side and micro and regulatory policy.   This is the second chance for this argument to succeed.  Watch this space.

The high debt stock, coupled with expected large deficit spending,  risks a spike in real interest rates and a sovereign credit downgrade.

Real Oil Price
President Reagan took office with a relatively high real oil price.  Note this was in an era when high oil prices were considered “bad” for the economy.   The real oil price dropped almost 75 percent in the first five years of the Reagan administration.   President Trump will inherit a real oil price half that of Mr. Reagan, coupled with the ambiguity of not knowing if higher oil prices are good or bad for the economy.  We don’t know where to go with this one.

Dollar
Mr. Trump inherits a real trade weighted dollar a little over 10 percent stronger than President Reagan and, most likely, headed north given the world’s divergant growth and monetary policies. This could act as a headwind on corporate profits and export growth.

Individual Marginal Tax Rates
This is the pearl and central to the supply side argument.  Cutting marginal tax rates to incentivize economic behavior and growth, which will increase tax revenues that offset the revenue loss from the tax cuts.   Note,  President Reagan cut the top rate from 70 percent to 28 percent.   That was Yuuuge!   Mr. Trump just doesn’t have the room to do such large tax cuts as he starts at a lower base with the highest tax rate at around 40 percent.

Corporate Profit Margins
President Reagan took office with a lot of corporate inefficiency and room to expand corporate profits.  It feels we are close to peak margins.   Didn’t we just have an election to improve the wages of the average worker?    Watch this space.

Stock Valuations
Much like the debt stock,  Mr. Trump will inherit a stock market that is relatively highly valued.  Note,  one of Warren Buffet’s stock market valuation metrics,  Stock Market Cap to GDP, is more than 160 percent higher now than it was when President Reagan took office.  The U.S. will need lots of economic growth to “grow” into this metric.

Conclusion
There you have it.  The macroeconomic initial conditions at the beginning of two Presidencies.   This is just our first quick whack at this analysis.

President Trump is going to have to depend on “animal spirits” to do a lot of the heavy lifting and an exquisite execution of supply side, microeconomic, and regulatory reform to increase potential GDP growth.   Higher growth will increase the top line of companies and improve earnings.  But we think, after looking at the data,  the window is narrow.

Can we rally a lot?  Absolutely.  And probably will given the better business conditions initially created by regulatory reform and the fiscal stimulus.

A Reagan bull market?   We don’t think so.

By the way, and contrary to the conventional wisdom,  the Reagan bull market is only the 5th largest Presidential bull market since Teddy Roosevelt, just behind the Obama bull market.

We could be wrong and it surely hasn’t paid to short or underestimate Donald Trump.   But, he just won’t, and probably, can’t,  have the macro tailwinds that President Reagan had at his back given the initial conditions of the macro data.

Stay tuned.

Posted in Equities, President Trump, Uncategorized | Tagged , , | 11 Comments