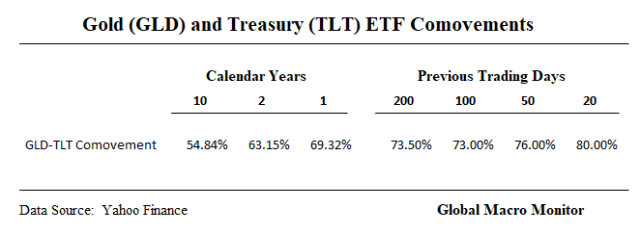
We have posted several pieces over this year noting the high correlation of gold and 10-year bond futures. See here, here and here.
Here is how the gold ETF (GLD) and the Treasury ETF (TLT) have moved together over various periods. The data show the correlation is increasing. For example, over the past 20 trading days, the GLD and TLT have moved in the same direction on the same day 80 percent of the time, this compares to around 55 percent over the past ten years.
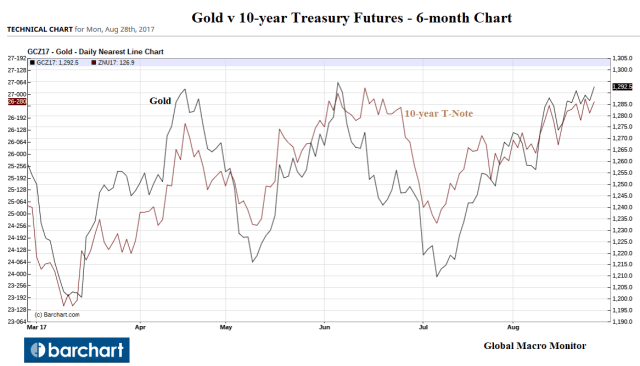
Now check out how the nearest gold and 10-year Treasury futures have tracked each other over the past six months.
We wrote many years ago that gold often takes on many personalities at any given time:
Gold is a weird cat with multiple personalities and more than nine lives. The yellow metal is up almost $100 since last Friday’s weak U.S. employment report.
At any given time period gold will assume any one of its multiple personalities based on a fundamental story and trade as: 1) a safe haven; 2) an inflation hedge; 3) a commodity; 4) a store of value against central bank balance sheet expansion; 5) an alternative currency; 6) central bank reserve currency; 7) a diversification asset; 8) an Armageddon hedge; and/or 9) all of the above.
– Global Macro Monitor, June 6, 2012
Add to that, what we have induced through market observation, the potential for a gold-bond tracking risk-on/risk-off algorithm. That is algos programmed to track gold with the bond on an almost daily basis.
Gold As An Inflation Hedge?
Is the recent rise in gold forecasting inflation? Don’t think so.
Why would it be tracking the bond — but…….
We are convinced the bond market signal has been so distorted by quantitative easing; it is now almost meaningless. At the very least, the level of interest rates is greatly distorted.
The Fed and foreign central banks now own more than 60 percent of Treasuries with maturities longer than one year. The Fed, alone, holds around 35 percent of Treasuries maturing in 2027-2047.
We will concede the directional change in yields may mirror changes in short-term fundamentals as traders buy and sell and whip and drive the markets.
As Mark Dow more eloquently put it:
“The bond market—in both shape and level—has been telling us very little about US economic prospects/activity. However, short-term changes do inform us as to the prevailing narrative.” – Mark Dow
So it may be possible that bond yields are so repressed, and all the bond market vigilantes have been killed off by the central banks over the years, that any future inflation signal from bonds has been drowned out.
Any distortion in the bond market signal — the most important price in the world in which all risk markets are priced — is not good, folks.
Some think the inflation hedge has been transferred to the cryptocurrencies as a new form of money.
We sincerely doubt it. A medium of exchange doesn’t move 5-25 percent in one day.
We do find, however, the blockchain technology behind the cryptos fascinating and the potential for an enormously disruptive force in finance and the economy.
Is The Bond-Correlation Signalling Trouble For the Dollar?
Nope.
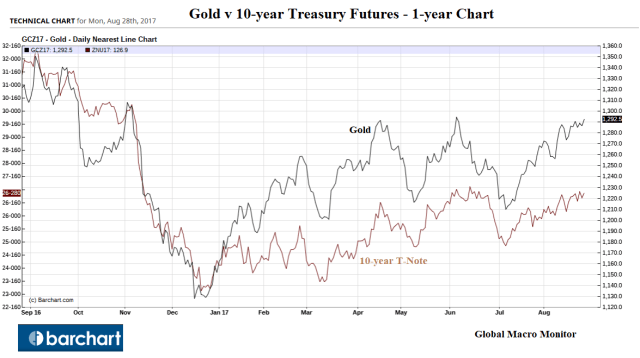
The dollar was soaring before the Trump slump, which began around inauguration day. Here is the one-year chart of the gold-bond correlation.
The dollar is in trouble because it had run up before the inauguration, pricing in a significant fiscal expansion — tax cuts and infrastructure spend — higher relative policy rates and economic growth. That’s all deflating now and the European economic recovery is picking up steam. In addition, the Dixie now trades with Trump’s poll ratings and currently sits at the critical level of 92.
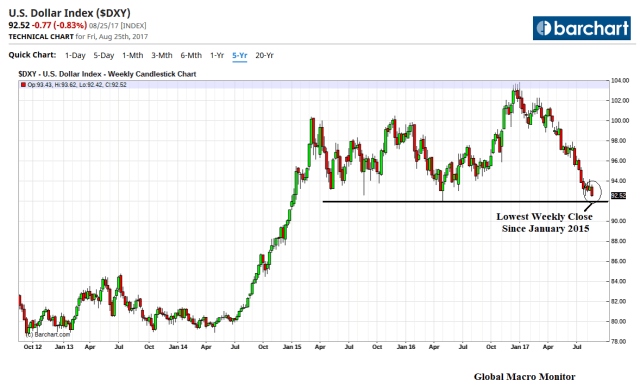
If the long-term viability of the dollar and its reserve status were really in doubt, we would expect gold and bonds to diverge and move in the opposite directions. That is gold soaring and bonds tanking. Watch that space.
Upshot?
Making sense of today’s markets is hard.
We have never seen this or been here before. Who would have imagined that raising policy interest rates would require more liquidity injected into the financial system rather the traditional monetary policy approach, where reserves and liquidity are drained from the system?
Maybe that is what seemed to be in the Fed’s cryptic warning in the latest FOMC minutes.
In assessing recent developments in financial market conditions, participants referred to the continued low level of longer-term interest rates, in particular those on U.S Treasury securities. The level of such yields appeared to reflect both low expected future short-term interest rates and depressed term premiums. Asset purchases by foreign central banks and the Federal Reserve’s securities holdings were also likely contributing to currently low term premiums, although the exact size of these contributions was uncertain.
…Several participants noted that the further increases in equity prices, together with continued low longer-term interest rates, had led to an easing of financial conditions. However, different assessments were expressed about the implications of this development for the outlook for aggregate demand and, consequently, appropriate monetary policy. – FOMC Minutes from July 25-26 Meeting
We sold the lows on gold in December, by the way, as we thought it would trade down into the triple digits with the Fed raising rates, reducing their balance sheet and the central government expanding fiscal policy. It’s tough trading these days.
What Are The Markets Signaling?
The 10-year is only six bps from the June 14th intraday low for the year, at 2.103 percent and just three bps off closing low on June 26th.
If gold is tracking the bond, which is massively distorted, do the trading ‘bots understand these distortions caused by QE and the new dynamic structure of the markets and the global economy?
Feedback Loop Between Asset Markets and Economy
Markets trade as if there is a massive feedback loop between asset prices and real economy — the risk-on/risk-off trade and gold-bond correlation, for example. That is because there is.
The secular stagnation in real wages for those with higher propensities to consume has weakened organic aggregate demand, which is now insufficient to absorb the massive increase in global productive capacity caused by the huge positive labor supply shock of China, India, and Eastern Europe entering the world economy. As wages converge across economies — what economists call “factor price equalization” — inequality is increasing in the developed markets, but decreasing across the developed vis-a-vis the developing economies.
With real wages, at best stagnant, in the developed world, global economic growth is now, as it has been for years, highly dependent on the wealth effect of ever higher asset prices to stimulate aggregate demand. Witness the slow recovery in the measured inflation of goods and services even as asset prices inflate.
Enter Unorthodox Monetary Policy
Developed economies are at the end of a long-term debt cycle. Monetary policy, rather than working through the credit channels, as interest rates are at or still close to the lower bound, is now more dependent on asset prices and exchange rates as the primary transmission mechanisms of stimulating aggregate demand and economic growth.
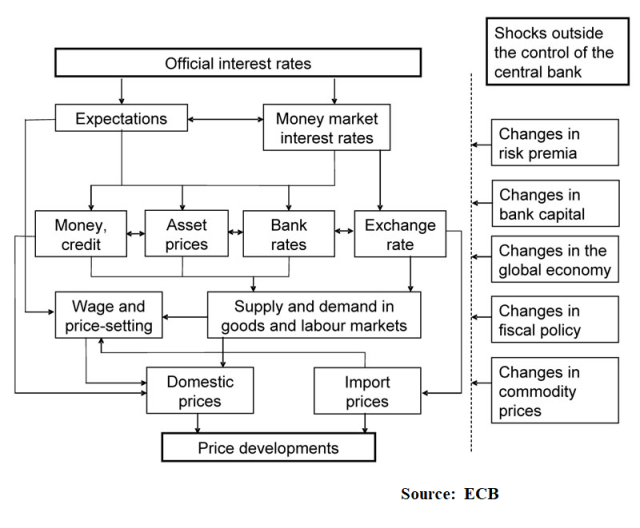
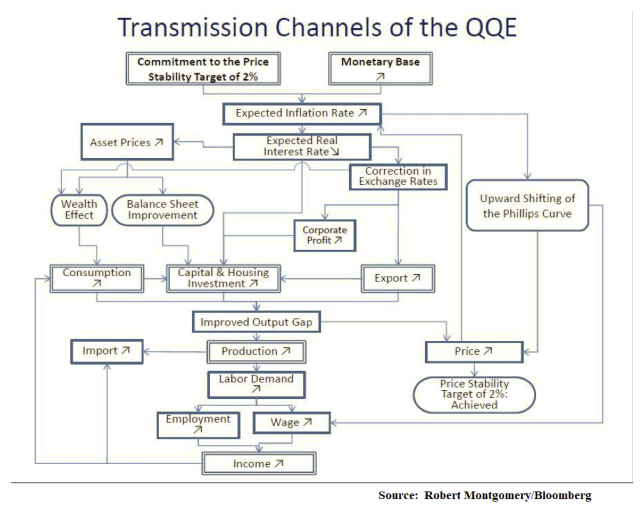
If the credit channel begins to really loosen up and credit flows into the real economy (rather than stock buybacks, e.g.), inflation will pick up and the global central banks will have a lot of catching up to do. Especially given how much they have flooded the world’s financial system with high powered money over the past decade.
Machine Learning Algos
Most of the trading these days are done by machines based on so-called sophisticated algorithms.
Computers have taken over the majority of trading on Wall Street and are threatening the very nature of the trading profession. Laura French asks whether traditional traders are fighting a losing battle – World Finance
Remember the days when the S&P500 traded almost tick for tick with the Aussie dollar? More ridiculous was the story that algos were programmed to buy Berkshire Hathaway stock when Anne Hathaway’s name was mentioned on the tape!
Some, or most, algos use machine learning or self-programming. But what are they learning?
Developing, tracking and trading spurious correlations? Designed and matured in the age of ZIRP, NIRP, and quantitative easing. Is it any wonder that most asset markets and their price action now seem divorced from reality?
Record low volatility given all the event risk on the horizon?
Dhaval Joshi, chief strategist for BCA Research, says: “At our client meetings, almost everybody disbelieves that current valuations allow developed market equities to generate attractive long-term returns. Yet many investors are willing to suspend this disbelief, at least for the time being.” – FT
But, hey, this is the market we live in today and have to adapt to make money for ourselves and our investors.
What Now?
We are not saying that the bull in risk assets can’t last for much longer than many think. As long as measured inflation appears tame, asset markets can remain overvalued much longer than shorts and cash hoarders can remain solvent.
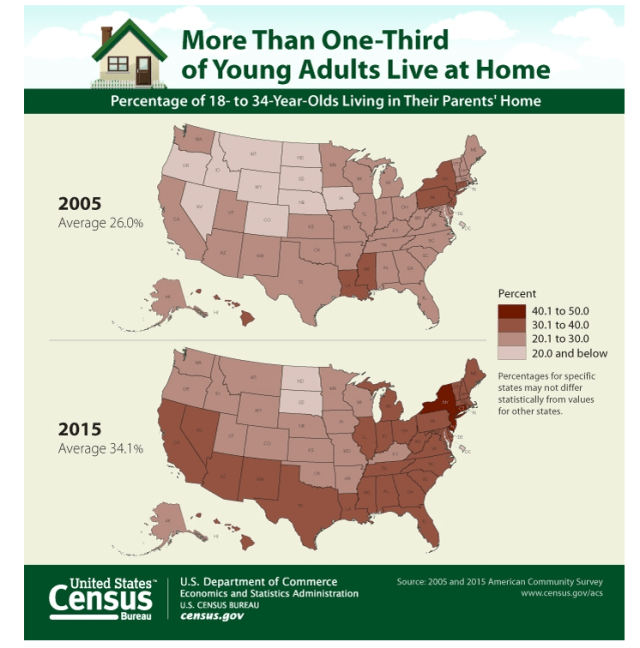
The big question is, as Raoul Pal asks, which generation will take the hit?
The younger generations paying up for overvalued assets, not to mention all the pension liabilities and debt they have inherited. Furthermore, at current prices, they will realize relatively small returns on their savings over their lifetime vis-a-vis the boomers.
Or will it be the baby boomers taking the hit through a significant downward asset price adjustment and bear market to cheapen assets in order to provide the basis for a decent long-run return for the millennials and other younger generations?
If the former, the seeds will be sown for a potental political rupture in America’s body politic, some of which we are now starting to experience with the rise of populism and the election of Donald Trump. However, we think it will be the latter, but maybe a bit later than many think, with more political chop and volatility ahead.
We’ve been writing about this coming “clash of generations” for years.
Inflation: Build It And It Will Come
We do disagree with Mr. Pal on the end game, however. We think this all ends in higher inflation rather than Mr. Pal’s deflation scenario, though we agree there could first be a period of deflation panic.
Central banks have already shown us they will do whatever it takes to fend off deflation. If that means becoming effective employment agencies, and monetizing wages and pensions, either directly or indirectly, that is what they will do.
Still, central banks execute monetary policy using indirect transmission mechanisms, but they have resorted to policies unthinkable 20 years ago. Directly buying stocks hoping to stimulate aggregate demand, for example.
The Bank of Japan’s controversial march to the top of the shareholder rankings in the world’s third-largest equity market is picking up pace.
Already a top-five owner of 81 companies in the Nikkei 225 stock average, the BOJ is on course to become the No. 1 shareholder in 55 of those firms by the end of next year, according to estimates compiled by Bloomberg from the central bank’s exchange-traded fund holdings. – The Japan Times
We are, or eventually, will be inching ever closer to direct monetization of aggregate demand if the global economy begins to slide again.
There is already talk of a “universal basic income“, which will almost certainly be monetized, and in the U.K. there is the “People’s QE”.
The UK policy of increasing money supply in the past has always been based on two premises to avoid hyperinflation and currency destruction: the independence of the central bank as a central pillar of monetary policy, and the constant sterilization of asset purchases (ie, what it buys is also sold to monitor market real demand). The balance sheet of the Bank of England has remained stable since 2012, coinciding with the highest economic growth period, and is below 25% of GDP.
Corbyn´s People´s QE means that the central bank will lose its independence altogether and become a government agency that prints currency whenever the government wants, but the increase of money supply does not become part of the transmission mechanism that reaches job creators and citizens in the real economy. All the new money is for the government, with the Bank of England forced to buy all the debt issued by a “Public Investment Bank”.
– Zero Hedge, August 19
If not for the contraction in the money multiplier and secular decline in the velocity of money, coupled with the reserve and hard currency status of the big four central banks — Fed., BoJ, ECB, and BoE, — where the economy has the confidence and willingness to hold the local currency, QE would have descended into a burst of high inflation.
But confidence is a very fragile thing and we can’t print our way to growth. At some point, there is a tipping point. Rollover risk greatly increases with the decline in the confidence in the local currency.
The timing of the coming debt ceiling debate is not optimal given the precipitous decline and current fragile nature of the dollar. A very low probability event of a crisis, in our opinion, but an extremely high impact event.
Don’t lose sleep, however, but at least keep it on your radar. The upside is everybody in the world is short dollars.
Why Can’t We Just Be Long-Term Optimists?
We are. Especially, after monetary policies are normalized and an asset valuation adjustment takes place.
Stock prices will be higher in 10, 20, and 30 years from now.
The journey is sometimes more important than the destination, however.
As with any journey, the path we take is more important than the destination we arrive – Todd Harrison
We do admit the above analysis is based on linear thinking and that is usually not a good forecasting framework. Economic progress and innovation usually takes place exponentially.
Emerging Markets Are The Place To Be
Finally, Green Acres emerging markets is are the place for me. Because, to paraphrase, the bank robber, Willie Sutton, “that’s where the money growth is.”
Younger demographics, lower debt profiles, and the potential for significant productivity and efficiency gains. Think India — with a median age of 28 years-old versus Japan and Germany’s median age of 47-years old — for the long term.
Not going big until an asset price adjustment, however. Especially after this year’s big run up.