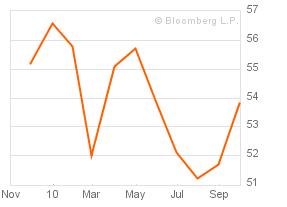
China’s September PMI 53.8 v. August 51.7

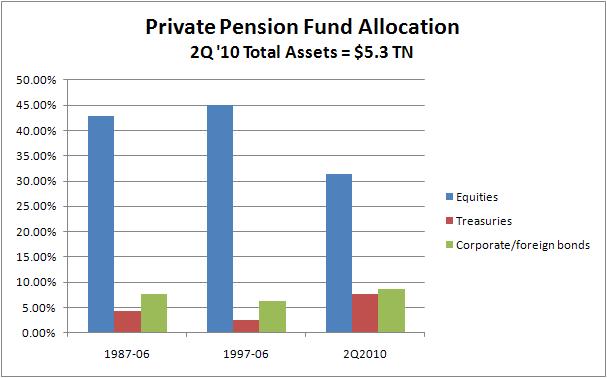
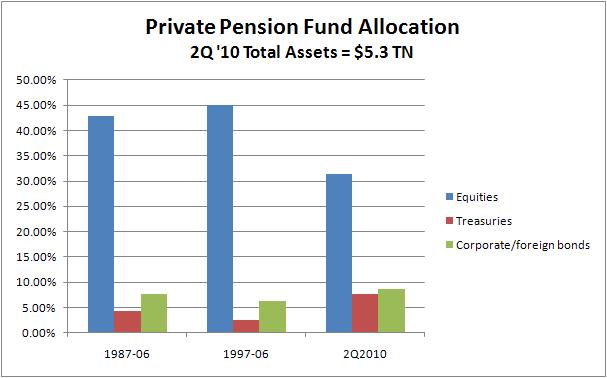
China’s PMI came in at 53.8,  erasing fears the economy was slowing.  A decent ISM (54.5   consensus) tomorrow will set a positive tone for Q4.  Recall our analysis of the under invested private pension funds sector (see chart below), which is a reflection of the overall market, in our opinion.  This could spark a buying panic in the next few months, especially in emerging market equities.

The WSJ reports,

BEIJING (Dow Jones)–China’s manufacturing activity expanded in September and accelerated from the previous month, an official gauge showed Friday, adding to evidence that Chinese growth remains robust.

China’s Purchasing Managers Index rose to 53.8 in September from 51.7 in August, the China Federation of Logistics and Purchasing, which issues the data with the National Bureau of Statistics, said in a statement.

A PMI reading above 50 indicates an expansion in manufacturing activity, while a reading below 50 indicates contraction.

Of the PMI’s 11 categories, nine rose and two fell compared with August, indicating broad-based strength. Only two categories, stocks of purchases and stocks of finished goods, were below the expansionary threshold of 50.


Posted in Uncategorized | Leave a comment

The “Catch-Up”Trade

Interesting chart of today’s activity.  They sold the grains and bought crude, which has been a laggard.  The “catch-up” trade, where laggards outperform,  may be the theme of the markets for the next few weeks.

Posted in Bonds, BRICs, Commodities, Credit, Currency, Equities, Gold | Tagged , , , , | 3 Comments

Will the Republican “Young Guns” Lasso Gold?

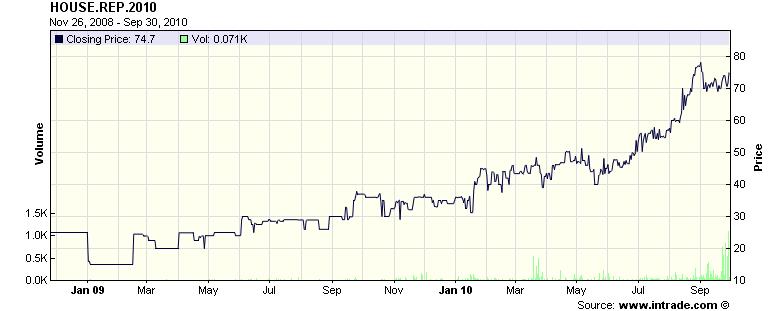
We’ve commented that an off-radar risk to gold is the hard money inclinations of the Republican leadership.  A Republican House in the next Congress is a done deal according to the prediction markets.  Intrade gives the scenario a 75 percent probability.

Rep. Eric Cantor,  the miniority Whip and “Young Gun”,   is the assumed heir apparent to John Boehner, who will become Speaker in January.  He’ll have tremendous influence on policy and strategy and we caught a glimpse of his view on monetary policy on the Kudlow Report a few days ago,

Kudlow:  Let me ask you one more….. The Federal Reserve , Mr. Cantor, is fixing to start pumping more cash into the economy and, as sure as we are talking tonight, that is going to deliberately sink the dollar, which was the same mistake we made in the middle 2000’s that exploded assets and energy and gold and oil at 150 bucks.  Do you, or anybody else in the GOP caucus, do you ever think about a stable dollar, linked to gold, stop the Fed’s destruction of our currency?

Cantor:  A lot of us our concerned about a weak dollar….There is no question, coupled with the fiscal policy of this Obama administration, and a more active Federal Reserve at this point raises an awful lot of concerns in many, many minds in Washington.  – 6:23 minutes

There you have it.  Not that they’ll stop the printing press, here, Japan, or elsewhere, but as the rhetoric heats up closer to the election , it could cause a nice correction in over bought commodities, including gold.  We’re not trading on it yet, but keeping it on our radar and will be looking to buy the pullback.

Posted in Commodities, Currency, Geopolitical, Gold, Monetary Policy | Tagged , , , | 3 Comments

Black Swans Everywhere

Equities are holding up well given some very ugly headlines (see below).   The markets ignored the strikes in Europe today, which is quite remarkable as it was the live CNBC video feed of the Greek riots that got the flash crash rolling.   These events are known and, therefore, don’t qualify as pure Black Swans.  The worst case scenarios have also been discounted as a low probability.   We will comment more on the specific issues and which we believe pose the most danger in later posts.  Click highlighted sources to read articles.

House passes bill aimed at Chinese currency – Bloomberg
Fed Presidents Far From Unanimous on Need for Further Easing – Bloomberg
Europe on strike over austerity measures – Telegraph
Block on Minerals Called Threat to Japan’s Economy – NY Times
Moody’s downgrades Spain rating to Aa1 – MarketWatch
Does a 1930s-style trade war loom as recovery falters?  – Globe and Mail
Paris terrorist alerts multiply – The Connection
Capital controls eyed as global currency wars escalate – Telegraph

Posted in Black Swan Watch, Commodities, Currency, Geopolitical | Leave a comment

Solar “Death Ray” Burns Lawyer. Stocks Up Big!

Wow!  This sounds like something out of Shakespeare Star Wars.   The Daily Tech reports,

Hotel Accidentally Makes Solar “Death Ray,” Burns Lawyer…

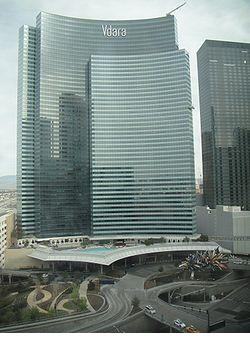
Bill Pintas was vacationing in Las Vegas when he decided to stay at the swank new Vdara hotel, a curvy 57-story tower owned by MGM Resorts.  He was sitting at the pool… “I’m sitting there in the chair and all of the sudden my hair and the top of my head are burning.  I’m rubbing my head and it felt like a chemical burn. I couldn’t imagine what it could be.”

Like an ant under a magnifying glass, he remembers running to an umbrella, but being unable to escape the hot light…”My first inclination was thinking: Jesus we’ve destroyed the ozone layer because I am burning.”

…The “death ray” appears to be created by the glass surface of the hotel itself — acting as a concentrating parabolic dish — similar to those used to heat water to a boil in solar power systems.  The dish concentrates light on a 10-foot by 15-foot hot zone moving across the pool.  Temperatures in this area spike 20 degrees Fahrenheit — or more.

…It looks like the Vrada may have exposed the wrong guest to the death ray, though —  Mr. Pintas is a Chicago-based lawyer.

We’ve long been advocates for Concentrated Solar Power (CSP) since a goldfish bowl burnt a hole in our kitchen counter, but this takes it to next level.

Solar stocks had a good day.  We like Trina (TSL) and LDK Solar (LDK),  both up over 4 percent.  TAN, the solar ETF,  is on the verge of breaking upside resistance.   We’re a bit cautious, however,  as the RSI is in overbought territory and would wait for a pullback or definitive breakout.

Posted in Equities | Tagged , | Leave a comment

What is Spec? Baby, don’t hurt me, don’t me. No more!

Molycorp (MCP) and the rare earthers are getting hammered again today on reports that China has lifted the ban on REEs to Japan.   [Schrödinger’s] cat is out the bag and to think it is business as usual is complete nonsense.   Toyota and Boeing,  just to name a few, are scrambling to secure REEs (see our earlier post).   The great Tim Collins at Real Money posted this morning,

“Momentum favorite Molycorp (MCP) has reversed sharply after hitting $30 yesterday, down some 20% from that level. I would look for the $22.36 area as a potential long entry if we close beneath $24.18, the 13 day SMA which has been support on multiple occasions on this move higher.”

Trading REEs is trading rocket fuel. And we’ve traded a lot of rocket fuel in our day, including Peruvian defaulted debt, Russian defaulted bank debt denominated in French franc, and Sudan debt wall paper at 2 cents on the dollar.  The common characteristics were high uncertainty, extreme volatility, low liquidity, mega noise, and, at the end of the day, high returns.   This is spec, our friends.  Stay small, focused, and disciplined.  Maintain a core position for the long-term with a size you’re comfortable with.

Posted in China, Commodities, Equities, Gold, Rare Earth Elements | Tagged , , | 1 Comment

Pension Funds Under Allocated to Equities – Fuel for Rally?

Just a quick post of an interesting chart we constructed after a night of data crunching.  This is preliminary analysis as we still need to look at flows versus valuation effects, and the data should also be viewed with a few caveats. *


The chart illustrates how under allocated the private pension funds sector is to the equity market relative to their historical averages.  For example,  the sector’s  allocation to equities averaged 45% from 1997-2006 and 43% for the 20-year period, 1987-06.   The 2Q 2010 data from the Federal Reserve shows an allocation of  only 31% to equities. Their most recent allocation to Treasuries is more than three times the 1997-06 average.

Such a large and under invested institutional sector provides the technical fuel and necessary condition for a decent equity rally.   It will be difficult for the defined benefit pension plans to fund their liabilities with such paltry bond returns and,  out of necessity,  will be forced to take more risk.

The sufficient condition for a rally is a story and catalyst.  Will a 2.0% 10-year and QE2 be enough?    We are leaning that way, but would like to see a 3-5% correction to get longer.

We’ll have more analysis in future posts.  Stay tuned!

* The data are aggregated and combine defined benefit plans and defined contribution plans, including retirement funds of nonprofits and single-employer and multi-employer plans of for profit firms.
Posted in Bonds, Credit, Equities | 3 Comments

The New Gold Rush?

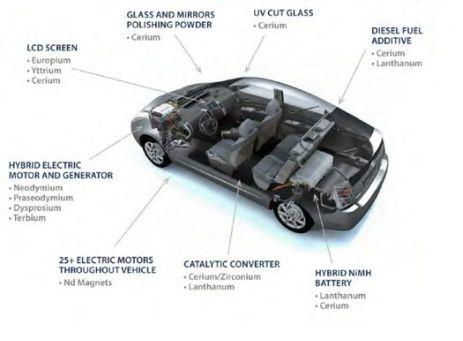
Rare Earth (REE) stocks,  including Molycorp,  got hammered today and we added a little to our position.  These  stocks are over extended as most are up over 100 percent in the past month. We believe this story has legs and is just getting started. Consider,

“Toyota Motor Corp. has set up a task force on rare earth minerals used in hybrid cars amid reports of China’s ban on exports of the materials to Japan. – Bloomberg

“Boeing has signed a deal to deploy remote sensing technology to map out U.S. deposits of rare earth elements…Boeing’s decision to bring its technology to bear in the hunt for rare earth elements is not surprising, given that it is a massive end user of the metals.” – TechNewsDaily

Scarce commodities, which have no substitutes and critical for industry and national security?   Sounds like “Gold on Steroids” to us.  We wouldn’t bet the ranch, but don’t want to miss what could be a nice run as the market begins to focus.  This is a long-term story and experts say that rebuilding an independent U.S. supply chain could take 15 years.   The Defense Department is about to release a study on the national security aspects of the U.S. REE dependence on China.


Posted in Black Swan Watch, China, Commodities, Equities, Geopolitical, Gold, Rare Earth Elements | Tagged , | 3 Comments

The 10-year sets sail for 2 percent…

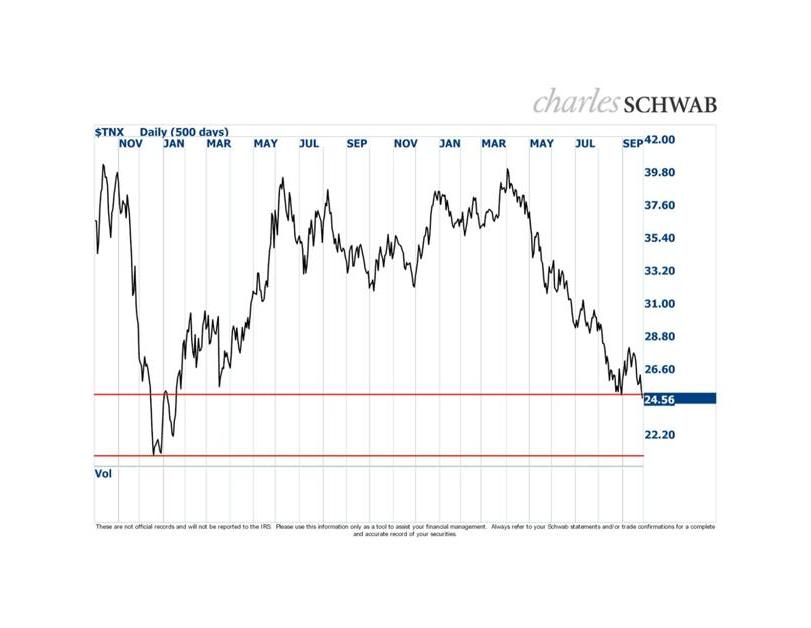
The 10-year closed at 2.46 percent today, a 20-month low,  on the back of weak consumer confidence.  Bond buyers and traders hear the horn of QE2 and anticipate a  [Kentucky] FED take-out at higher prices.

Stocks up,  commodities x/grains up,  bonds up, dollar spanked.  Loose monetary conditions starting to bite.    “John Bull can stand many things, but he cannot stand two zero percent.” Stay tuned!

Posted in Bonds, Credit, Currency, Equities, Gold | Tagged , , | Leave a comment

The Quantum Mechanics of the U.S. Bond Market

The 10-year Treasury rate fell almost 10 bps to close at 2.52 percent,  just 4 bps off its August 24 recent low.   A close below 2.50 percent will clear the way for a move to challenge the December ’08 low of 2.03 percent.   Surprisingly, the S&P 500 is almost 100 points above its August 24 close.  The bond, equities, and commodities have been moving together in a powerful rally since early September.   If sustained,  it would be an early sign loose monetary conditions are beginning to bite.

We wrote in August that the 1o-year Treasury bond was fundamentally overvalued at 2.5 percent yet could rally to 2.0 percent with a new round of European sovereign debt worries or the announcement of QE2.   We expected a back up and thought 2.80 percent would provide a good entry for traders.  The closing high during the correction was 2.795 percent.
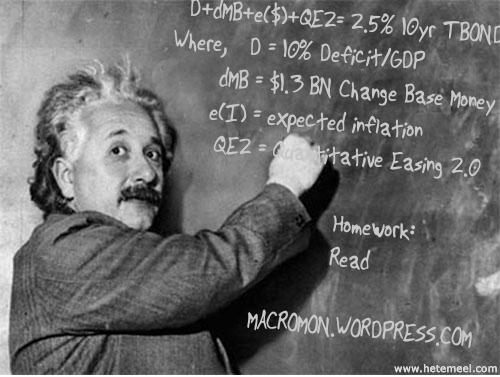
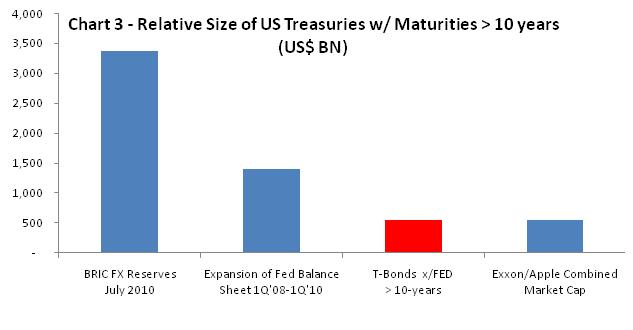
We recognize the bond, given its small size relative to other asset classes and pools of liquidity,  lives,  simultaneously,  in two realities.   The fundamental reality,  based on economic,  credit,  monetary and foreign exchange risks,  is that the bond is overvalued at 2.50 percent,  in our opinion.   The technical reality is different story, however, where the Fed could theoretically could buy up the entire curve from 10-30 years with just half what it spent in QE1 (see chart).    We have learned not to fight the Fed.

Finally, even just observing the 2.50 percent interest rate through fundamental reality increases the risks of self fulfilling deflation through a positive feedback loop.  We wrote,

“One danger of the lack of price discovery [in the bond market] is the potential formation of a positive feed-back loop, where other markets fail to discount these distortions and act accordingly.  One prominent economic strategist recently stated, ‘We’re in a depression. That is what the bond market is telling us.’“

So there you have it.  Two realities, two cats.  One cat named Dave, who says the bond is fundamentally cheap based on the economic outlook and move to 2 percent is a done deal.  The other cat named Doug, who says the bond is  the “short of the decade,” but getting the timing right is difficult.

We side with Doug and will look for strong technical confirmation before entry or a reversal in the fundamental reality, such as change in monetary policy and/or  economic conditions. Stay tuned!
Posted in Bonds, Monetary Policy, Sovereign Risk | 27 Comments