When Algos Go Rogue

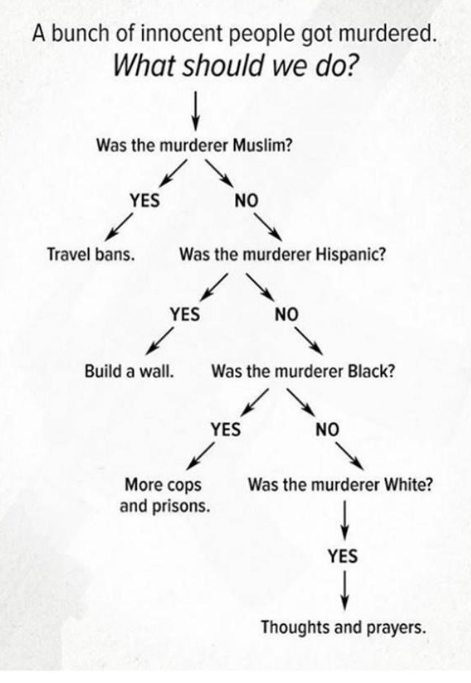
No political statement here but the following decision tree illustrates how algorithms can be biased. Note decision trees are a fundamental tool of artificial intelligence, algorithms and predictive analytics and their biases can destroy lives and even countries.
Rogue Algo_Feb16                          Hat Tip:  @ianbremmer

Algo Or Government Reaction Function 

We hope the decision tree is not the algo or reaction function of the current U.S. government and the Congressional leadership, but to use Milton Friedman’s analogy of the pool player using but not understanding the laws of physics, they act as if it is.

To illustrate this, consider Milton Friedman’s famous exposition of the as if argument. He used the analogy of a snooker player who does not know the geometry of the shots they make but behaves in close approximation to how they would if they did make the appropriate calculations. We could, therefore, model the snooker player’s game by using such equations, even though this would not strictly describe the mechanics of the game. – Unlearning Economics

It is also one reason why we are bearish on the American Street and expect political and social instability to increase in the U.S. over the next few years. The politicos are stunningly tone deaf to the mood and needs of the vast majority of the American public.   The “Swamp” is now at the elbow of  exponential growth.   Something is going to break.

We now fear the American Street more than the Arab Street.

Don’t Forget The Victims Of Florida School Shooting

Just look at the pictures and listen to stories of the kids and adults killed in the recent school shooting in Florida.  Heartbreaking.

Picture of Victim_Feb16

The reaction of the country, the victims’ families, and even the high school students that survived the shooting seems different this time.

Do you sense the rage building?  Could this be the tipping point?

The Second Amendment

We are strict constructionists in reading the U.S. Constitution here at the Global Macro Monitor.  Therefore we believe the second amendment allows for the right of every American to carry a Brown Bess, the most common musket used on both sides during the Revolutionary War, the timeframe when the Constitution was written.  Nothing more.

Brown Bess_Feb16
Assault rifles, such as the AR-15?  No f#*king way  (NFW).

On The Side Of Reagan And Scalia

We side with both President Reagan and Justice Scalia on this one.

“I do not believe in taking away the right of the citizen for sporting, for hunting and so forth, or for home defense,” he said. “But I do believe that an AK-47, a machine gun, is not a sporting weapon or needed for defense of a home.” – President Reagan

“It may be objected that if weapons that are most useful in military service — M-16 rifles and the like — may be banned, then the Second Amendment right is completely detached from the prefatory clause. But as we have said, the conception of the militia at the time of the Second Amendment’s ratification was the body of all citizens capable of military service, who would bring the sorts of lawful weapons that they possessed at home to militia duty. It may well be true today that a militia, to be as effective as militias in the 18th century, would require sophisticated arms that are highly unusual in society at large. Indeed, it may be true that no amount of small arms could be useful against modern-day bombers and tanks. But the fact that modern developments have limited the degree of fit between the prefatory clause and the protected right cannot change our interpretation of the right.” – Justice Scalia

The time, though long past, has come.

Appendix 

If you have time, make sure to watch this 12 minute video on the dangers of bias in algos and artificial intelligence.  Well worth your time.
 

Posted in Politics, Uncategorized | Tagged , , | Leave a comment

Lies, Damned Lies, And Statistics…And The CPI

The first three of those words are attributed to the British Prime Minister,  Benjamin Disraeli, and also sometimes associated with Mark Twain.

You know our skepticism of most government data, especially the BLS calculation of inflation in consumer goods and services.  The data are so massaged by seasonal and hedonic adjustments, and even full-blown methodological revamps when the numbers do not fit the objectives of the government, they just don’t reflect reality.

Go back to 1982 when the BLS came up with the concept of “owner’s equivalent rent (OER),” a large component of how the price of shelter is calculated in the CPI.  This was in response to the government believing rising housing prices were distorting the true cost of housing.  Houses were then recategorized as capital goods.   The data for OER are not hard,  not real world data points that can be measured,  such as egg prices.

A friend pointed out the following in today’s Wall Street Journal,

A monthly measure of what households pay for everything except gasoline and food rose a seasonally adjusted 0.349% in January—the strongest one-month increase since March 2005—driven by broad-based increases in costs like rent, clothing and medical services.  – WSJ, February 15

We wonder out loud about the 0.349 percent print.  Round it down, Charlie Brown!

Just another 0.001 percent and the BLS would have posted a core CPI monthly change of 0.4 instead of the 0.3 percent. The market response?

The headline number print of 0.5 percent was also very close to its rounding point.   Going out three more decimals, the number was .5448 percent.  Another 0.0012 percent, headline CPI prints at 0.6 percent.

Could they have?

Bureaucrats day trading (the data not securities) the monthly economic data?  The word comes down from on high not to kill Goldilocks with RoundUp?

You decide.

File this one under all things rigged and don’t cry for me, Argentina!


Posted in Inflation/Deflation, Uncategorized | Tagged , | 125 Comments

Europe’s Bad Debts Still Haunt The Euro Banks

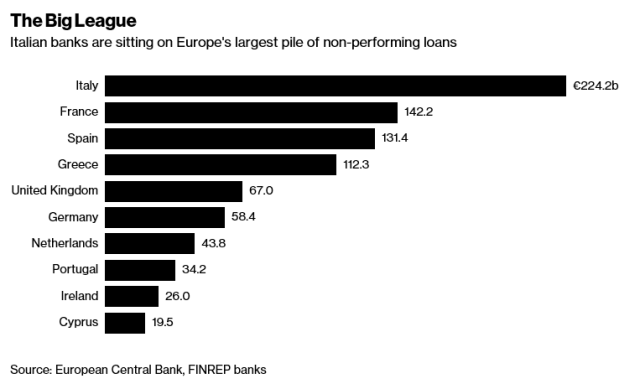
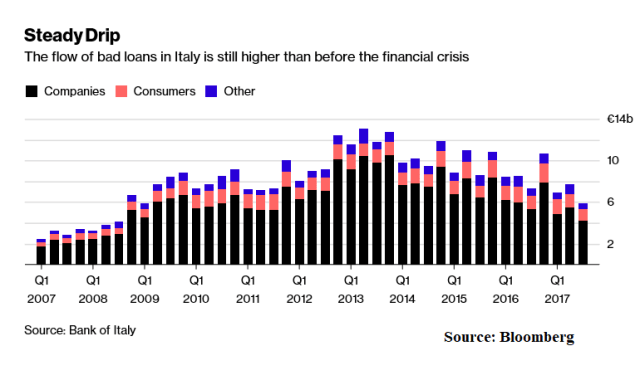
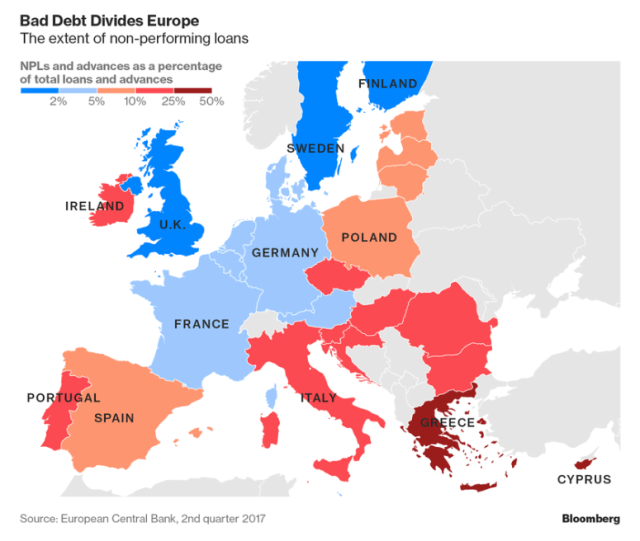
Looks like the new “Iron Curtain” in Europe is the non-performing loans (NPLs)  in each country’s banking system.    Greece and Italy stand out.

For European banks, it’s a headache that just won’t go away: the 944 billion euros ($1.17 trillion) of non-performing loans that’s weighing down their balance sheets.

Economists say the pile of past-due and delinquent debt makes it harder for banks to lend more money, hurting their earnings. European authorities are prodding lenders to sell or wind down non-performing credit, but they’re split on how to tackle the issue, and some investors are disappointed by the pace of progress.  – Bloomberg

Europe's Bad Debt Problems_Feb14


Europe's Bad Debt Problems__2_Feb14

Europe's Bad Debt Problems__3_Feb14

Posted in Banking, Debt, Euro, Uncategorized | Tagged , , | 2 Comments

Impressive Win For The Bulls


WinFlag_Feb14

That was impressive.

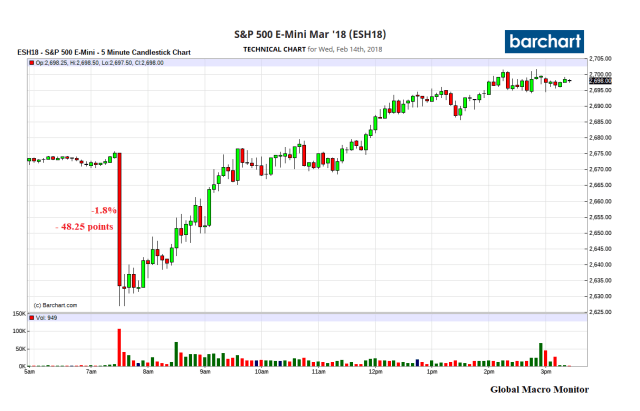
The hot CPI and weak retail sales data hits the tape at 8:30 eastern, S&P500 futures trade down 48.25 points or 1.8 percent in a Jackie Moon moment,  bounces around for about 20 minutes, then takes off and trades up 2.8 percent from the low into the close.  Even as the 10-year yield breaks and closes through the Maginot Line of 2.9 percent.

S&P500_intraday_Feb14

The cash S&P500 has now rallied 6.55 percent off its Friday low and recovered 48.78 percent of the high-to-low loss in this market move.   A move through the 20-day moving average at around 2770 will force the bears and shorts to reconsider their market view.

Can’t believe we are sucked into commenting on short-term moves, which are noise and random at best, determined almost solely by how the fast money is positioned and leaning.  But in the long-run there is always another short-run.

Nevertheless, today’s price action signals:  1) the market is “sold out” in the short-term;  2) there are few real sellers left in this leg, and 3) the fast money and machines were offside going into the CPI betting on an Armageddon number, which they kind of  got but were not rewarded.  Bond shorts faired much better.

The bullish and FOMO psychology hasn’t washed out yet and thus still makes us suspect the lows are not in.   The market is still very expensive and you can throw out the widely touted “fairly valued” EPS, which are the result of financial engineering and stock buybacks.

We like the S&P500 Price to Sales ratio as a more objective valuation metric as even earnings can easily be manipulated and are creatures of corporate CFOs.   We know that from our experience of working in a large money center bank.

Moreover,  the dollar continues to weaken, when fundamentals favors strength, which is a major concern.  Especially as interest rates rise.

Something is rotten and driving the capital flight.

Today was impressive, however.  Chalk another one up for the bulls.

Next Levels

Today’s high on the cash S&P500 was 2702.1, just a little more than 50 bps below 2702.78, the 50 percent retracement and key Fibonacci level.  The next level is 2726.67, last Wednesday’s high before the swan dive to 2532.69 on Friday morning.

Where Are 10-Year Yields Headed?

Nobody knows and because of that uncertainty, we look to gurus or technical analysis to comfort us and ease the anxiety of not knowing the future.

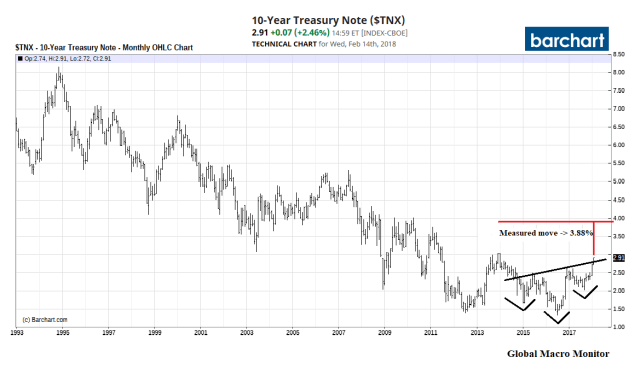
We do know the long-term downtrend on yields has been broken and looking at the chart, a reverse head-and-shoulders bottom has formed.   The neckline has been broken and a measured move  will take the 10-year to around 4 percent.

TNOTE Yield_Feb14

Makes sense to us, fundamentally,  as real interest rates are set to rise due to the supply and demand dynamics in the U.S. bond market and inflation is increasing.    A two to three percent real rate plus inflation has always been a running assumption for the long-term equilibrium interest rate all throughout our research career.

Technical Analysis

Technical analysis is imperfect but a tool, and one way to light the uncertain and a foggy-lit path of future prices.    We are not religious zealots and only half way sold on the utility of technical analysis but just throwing it out there for you.

We infer from the price action and lots of losses of the past several years that the machines use technical analysis to set bear and bull traps.   It has rarely paid to place a bet when a key technical level breaks as the algos are programmed to generate a giant reversal and squeeze when they calculate and estimate the net position of traders is leaning the wrong way.

Whatever your view, however, three percent is the next big number for the 10-year note yield.

By the way, remind us not to comment on short-term market moves.

Posted in Bonds, Equities, Uncategorized | Tagged , , | Leave a comment

German coalition agreement: AI program shows bias

Wow,  the robots are even coming for the political scientists.

Researchers used artificial intelligence to compare the manifestos of the German parties with the coalition agreement. And it showed that 70 percent of the content referred to the SPD manifesto and only 30 percent to that of the conservatives…

READ MORE:  http://www.euronews.com/2018/02/13/german-coalition-agreement-ai-program-shows-bias


Posted in Germany, Politics, Uncategorized | Tagged , , | Leave a comment

…Just Like The Titanic, But It’s Full of Bears!

Bad inflation print, bad retail print.

Market had a Jackie Moon moment just after the data release and is now trying to stabilize.  Ten minutes to open.  Big test today.  Not a buyer.

The S&P500 needs to hold 2612.97, the 23.6 fibo.   If that breaks, then Friday’s S&P low at 2532.69, which is just a few points below the 200-day moving average, is the red line.   If that breaks, look out below.

The massive short position in bond futures may provide some support. 

If you are gonna panic, you gotta do it before everyone else does.

Posted in Equities, Uncategorized | Tagged | Leave a comment

FinTech Investment By Top U.S. Banks

Fintech_Feb13

Posted in Banking, Uncategorized | Tagged , | Leave a comment

Watch These Levels

Is that it?  Is the sell-off over, new highs on the short-tem horizon?

Nobody knows.  The recovery is a process and unfolds one step tick at a time.

In our last Week In Review post, we noted,

Only three times since 1950 has intraday volatility jumped so high as measured by a modified version of the Average True Range: 1) September 1955 after an extraordinarily period of calm the S&P500 tanked on September 26th when markets opened after President Eisenhower’s heart attack on the 8th hole of Cherry Hills Country Club over the weekend. The market quickly recovered; 2) January 1962 when the “Kennedy slide” began to accelerate, and 3) the October 1987 stock market crash. – Global Macro Monitor, February 11

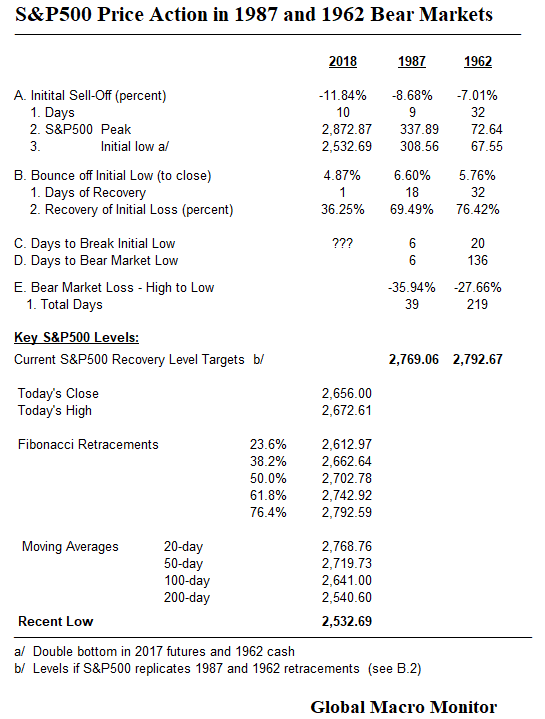
Given the historic vol shock we just experienced, we thought we would take a look at how the bear market of 1987 and 1962 unfolded after their volatility spikes.

We dismiss the 1955 Eisenhower heart attack shock as it was short-lived and did not result in a bear market.


S&P500_Feb12

The table juxtaposes the 1987 and 1962 bear markets with the current S&P500.

The recent sell-off is several hundred basis points greater than that of the first wave of both the 1987 and 1962 bear markets, 11.84 versus 8.68 percent in 1987 and 1962’s 7.01 percent.  The first leg of the bear took nine days in 1987 and 32 days in 1962 versus ten days in this recent period.

Note the first leg down of the 1962 bear also ended with a double bottom as did the current S&P500 futures.

First Bounce

The S&P500 has thus far rebounded 4.87 percent off its Friday low, recovering 36.23 percent of its losses from the peak.  It compares to the initial bounce of 6.60 percent, and a 69.49 percent recovery in 1987, which lasted 18 days; and 5.76 percent in 1962, which recovered 76.42 percent of its peak to first low loss in 32 days.

Next Leg Down

The data are still unfolding for the current S&P500.

In 1987,  it took six days to break the initial lows after making the swing high.  The market then bounced 1.66 percent on October 13th, to close back above that low.  It was the last hope and gasp of the bulls, however.

The S&P500 then rolled over hard and fell 2.95 percent, 2.34 percent, and 5.16 percent the next three days going into the eve of the crash.

The S&P500 closed down 20.47 percent on Black Monday and finally bottomed the next day.

The total loss of the 1987 bear market was 35.94 percent on S&P500 from its high to low, and lasted 39 days,  40 days and 40 nights of testing.

1962

The 1962 bear market unfolded much slower.

After the initial bounce, the S&P500 took 20 days to take out the initial low and bounced around that level for ten days then rolled over hard.

The 1962 bear market also experienced a flash crash on May 28th, falling 6.7 percent.

“The stock market careened downward yesterday,” reported The Wall Street Journal on May 29, 1962, “leaving traders shaken and exhausted.” The Dow Jones Industrial Average fell 5.7% that day, down 34.95, the second-largest point decline then on record.

“The drop took place on volume so heavy,” added the Journal, that the “ticker wasn’t able to finish reporting floor transactions until 5:59 p.m., two hours and 29 minutes after the market closed.”

…The crash of 1962 is a reminder that markets always have been messy and that investors’ morale always has been fragile. What’s more, the problems the regulators sought to solve nearly a half-century ago are still with us today. They probably will be tomorrow, too.  — Jason Zweig,  Wall St. Journal

The S&P500 took 136 days to bottom after breaking its initial low, beginning its rebound after the Soviets stood down during the Cuban Missile Crisis.

The 1962 bear market clipped 27.66 percent of the S&P500 and lasted 219 trading days.

Current S&P500 Target Levels

The table also shows the key levels for the current S&P500.

Most interesting are those levels which replicate the initial bounce of the 1987 bear, a 2,760.06 S&P500 and 1962, a level of 2,792. 67.  The message here is not to get complacent or too lathered up as the market rallies hard off the recent low.   It can go a lot further and is commonplace even in bear markets.

Noteworthy is that the S&P traded through the 38.2 fibo today but failed to close above it.

Bond Yields

We are also watching bond yields closely because their path is going to determine the direction of the stock market

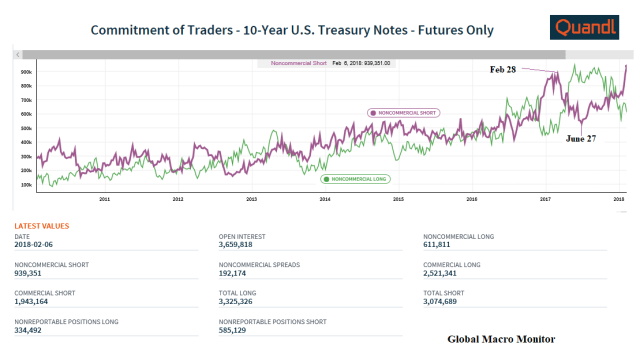
As the Quandl chart shows, the fast money crowd is significantly short 10-year note futures.

It is not always a prelude to an imminent short squeeze, however,  as the 10-year note yield chart shows the fast money had pretty good timing as yields temporarily spiked at their maximum short positions.

They then had to scramble to cover their positions generating the massive squeezes.


CFTC_Feb12

We sense the market technicals are rapidly changing, however.  The Fed is out and now running down their book.  Foreigners are tepid buyers, at best.

Moreover, the increase in supply in the form of future new issuance is not insignificant. Starting to catch a whiff of concern about the U.S financing its budget deficits.  Triple yikes!

Nevertheless, keep the CFTC data on your radar going into Wednesday’s CPI release.  If the number misses to the downside, it could get squeezy.

TNOTE_Feb12

Upshot

Is the stock market out of the woods?

Can’t say with certainty, but as the IMF representative in Uruguay used to respond when we pressed him if the government, who was facing elections in two months, could obtain a Fund program,

“It is possible, but not probable.”  –  IMF Uruguay Rep, circa…

We knew damn well there would be no deal.

Will we see a new high on the S&P500 sometime soon?   It is possible,  but not probable.

One Last Thing

Another take away from our data crunching exercise is that if the recent S&P low at 2,532.69 is taken out,  we suspect the exits will be jammed with those trying to get horizontal, and fast.   Take 1987 as your analog.

Finally,  we are the first to acknowledge that though the facts may be correct, our conclusions may be wrong.   Also keep that on your radar.

Good luck, folks

Posted in Bonds, Equities, Uncategorized | Tagged , | 57 Comments

Week In Review: JP And The JFK-Trump S&P500 Analog

Not a lot of poetry or prose again this week. We posted much material on our thoughts over the last few days. Have a look.

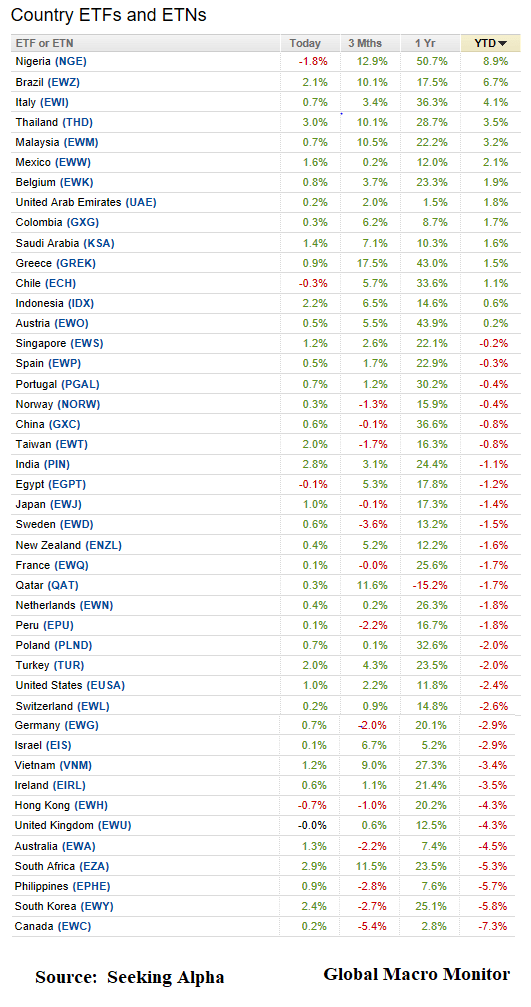
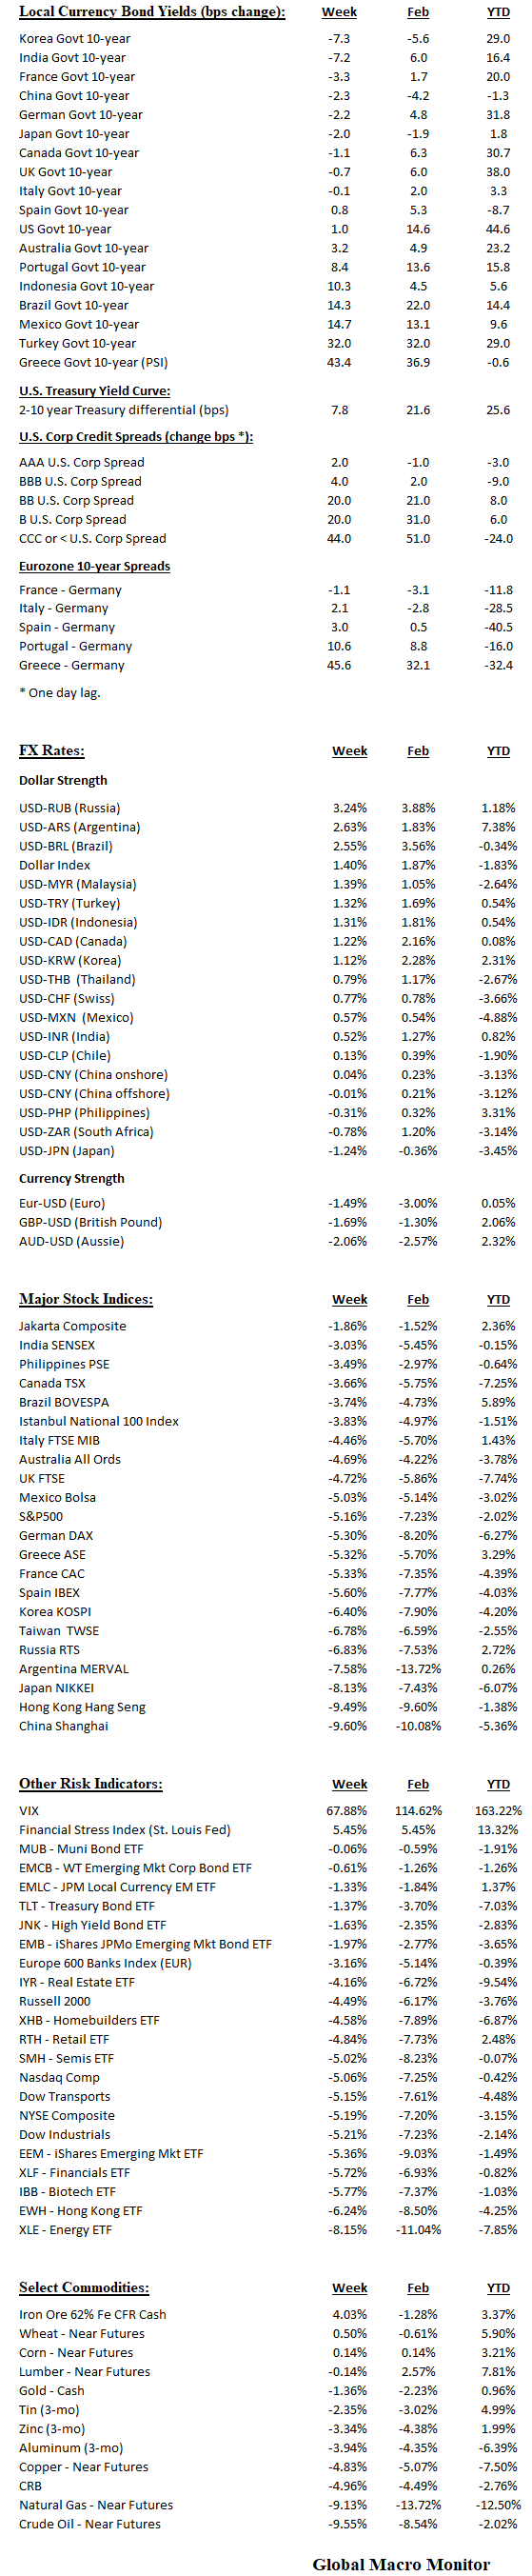
Also review the data tables below.

We do think markets are in for a bounce for a few days, but we believe we are far from out of the woods.  Credit spreads are starting to wobble.

Historic Volatility Spike

Only three times since 1950 has intraday volatility jumped so high as measured by a modified version of the Average True Range:  1) September 1955 after an extraordinarily period of calm the S&P500 tanked on September 26th when markets opened after President Eisenhower’s heart attack on the 8th hole of Cherry Hills Country Club over the weekend. The market quickly recovered; 2) January 1962 when the “Kennedy slide” began to accelerate; and 3) the October 1987 stock market crash.

Kennedy-Trump S&P500 Analog

This market is starting to look very similar to the JFK post-election rally, top, and bear market, which eventually bottomed when Khrushchev backed down during the Cuban Missile Crisis. We will post more on the JFK-Trump S&P500 analog later in the week.

We were planning on doing it later today but have to visit a dear friend in the hospital.

JP

Do us a favor.  Shoot up a prayer, send and think good thoughts, light a candle, or whatever works for you for our good friend JP.  We love him dearly.

He is a true American hero and a such a great and decent human being.   Think of it as your cost of admission to the Global Macro Monitor and duty to the international brotherhood of man.  No political correctness here.

If only the world were full of JPs, we would be in such a better place.

Please fight hard, as you always do, and get well, my brother.

This Week

The key on Sunday night is to watch how the Hang Seng trades.  It should have a big bounce, followed by rallies in Europe, signaling the U.S. market has some legs.

Most important, however, is the action in the bond markets. Higher interest rates will snuff out any bounce and continue to reprice equity values at lower levels.

Good luck this week, folks.

.

JFK_Trump S&P500_Analog

.

Week_2017_ETFs

.Weekly_Table


Posted in Uncategorized, Week in Review | Tagged , , , , , | 51 Comments

Could 2018 Be the Year of the Next Financial Crisis?

Interesting this was posted two days before market top.  One of the major concerns was a spike in volatility.  So prescient.

Davos was so lathered up with Bull.  Always so contrarian.

Is the century’s longest stock market bull run about to come to an end? Get ahead of the trends that will determine the world’s asset markets in 2018.

· Michael C. Bodson, President and CEO, Depository Trust & Clearing Corporation  (DTCC)
· Hélène Rey, Lord Bagri Professor of Economics, London Business School, UK

Moderated by Peter Wolodarski, Editor-in-Chief, Dagens Nyheter, Sweden

http://www.weforum.org/


Posted in Equities, Uncategorized | Tagged , , | Leave a comment