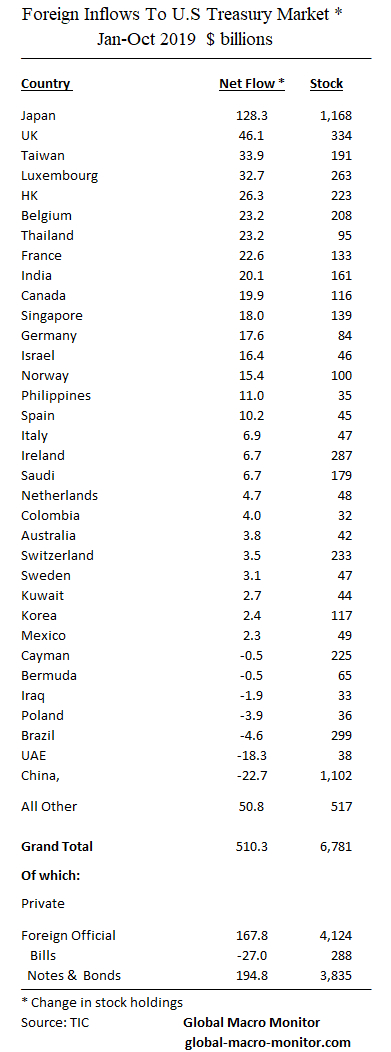The Happiest Places On Earth

Posted in Uncategorized | 2 Comments

The Black Swan Chart Of 2020

CNN_Voter Turnout Poll


The surprising outcome of the 2020 presidential election may be,

OK, Boomer.  It’s time to pass the torch of leadership to a new generation.   

The younger generations dwarf the boomers in terms of sheer numbers but they have a habit of not voting.   They may be changing, however, as it did in the 2018 midterm.

If the CNN chart holds and plays out, the 2020 presidential election is going to be nothing less than stunning.    The pollsters are going to be way off the mark once again.

The national polls were pretty much spot on in 2016 with Clinton taking around 2-3 percent of the national vote.   Their models blew it by underestimating the state-level turnout rates of certain voting groups.  They hadn’t modeled such a rush of first-time voters coming out of Appalachia, for example.

79 Percent Increase In 18-29-Year-Olds In 2018 Midterm

Look at the charts that follow, which show younger voters, such as the 18-29-year-old cohort group increasing their turnout by 79 percent in 2018 versus the 2014 midterm, which, no doubt, helped contribute to the Blue Wave and the Democrats taking back the House in a big way.

Voter_Turnout_By Age

Source:  USEP

The 2016 election was also the first election where the younger generations eclipsed the number of boomer voters.

Pew_voters

If the CNN chart is even close to reality in November, there is going to be another huge surprise on the first Tuesday night in November.

America’s Two Roads Diverged 

It doesn’t take a Ph.D. in political science to figure out which way it will break.  We believe it’s pretty safe to say the governing class in Washington will have a lot less old white males at the same time next year.

Even The Russians Are Concerned 

The last time the U.S. had a 70 percent voter turnout rate in a presidential election was in 1900 when William McKinley beat William Jennings Bryan by 51.6 to 45.5 percent in the popular vote and 292-155 in the electoral college.

The Russian military, who interfered attacked the 2016 presidential election appears concerned about a large turnout and is gearing up.

Russia

The federal government warned state election officials Thursday it suspects Russia my focus on voter suppression as a means to interfere in the 2020 presidential election. 

The joint FBI and Department of Homeland Security document, obtained by CNN and marked For Official Use Only, is titled “Russia May Try to Discourage Voter Turnout and Suppressing Votes in 2020 US Election.”

It warns of three potential ways the Russian government “might seek to covertly discourage or suppress US voters from participating in next year’s election.”

Russia may try to recruit Americans to protests and intimidate voters, sow discord online within political parties and try to hack voter registration sites or knock them offline, the report warns.  –  CNN, Oct 2019


Voter Turnout Poll_1

Voter Turnout Poll_2


Brext_3


Posted in Politics, Uncategorized | Tagged , | 3 Comments

Howard Marks, Oaktree Capital

Howard is always worth a listen.  Note the interview took place in October, so a bit dated.

We found a true gem from his latest memo, however.

This experience produced two of my most important observations:

  • Success in investing doesn’t come from buying good things, but from buying things well, and it’s essential to know the difference.
  • It’s not a matter of what you buy, but what you pay for it.  – Howard Marks

Got that, folks?   It’s not a matter of what you buy it’s where you buy it.   Just as those who paid up for the Nasdaq in 2000 and have held, are up only a CAAG of 3 percent in price terms, barely outpacing rolling 6-month CDs.

Posted in Uncategorized, Video | Tagged , | Leave a comment

The Best MLK Weekend Of All-Time

We are reposting this in honor of Dr. King, a truly great American.

Originally Posted on 

During my Lehman days as a bond strategist, the firm’s research group would do a January roadshow in many of America’s major cities to present our ideas to institutional investors.   One particular year, we were in Atlanta at the end of the week and scheduled for another “greatest show on earth” in Chicago the next Tuesday.

A Weekend In The Peachtree Hyatt

Rather than flying home to New York, I decided to stay over in Atlanta and migrate north on Monday evening.   It was MLK weekend and I wanted to attend services at the Ebenezer Baptist Church, where Martin Luther King, Jr. was baptized as a child and gave his first sermon. If my memory is correct, I believe his father also pastored the church.   His mother was shot and killed while she played the organ in that church in 1974.

Dr. King’s tomb is located just outside the side door of the church in the middle of a reflecting pool.
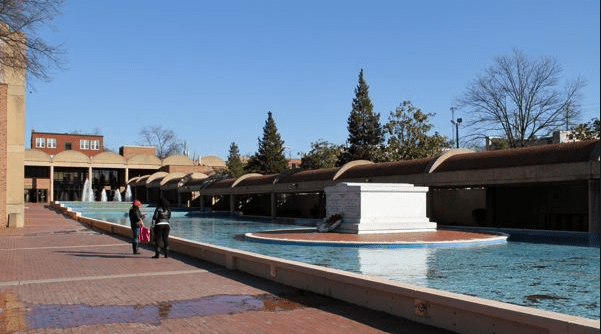
dr. king


Three Memories Of Ebenezer

I recall three of my main takeaways from that Sunday morning.

First,  I was maybe one of ten whites out of 600-700 people sitting in the pews.  Sadly, as Dr. King said almost 60 years ago.

I think it is one of the tragedies of our nation, one of the shameful tragedies, at 11 o’clock on Sunday morning is one of the most segregated hours, if not the most segregated hour in Christian America.  – MLK, Jr  Meet the Press, April 17, 1960

Nevertheless, I felt incredibly welcome and never — not for one nanosecond —  was conscious about such a silly thing as the difference of the color of my skin.  During the greeting time, the Ebenezers made me feel so welcome and a part of their family.

Second, not to contradict Dr. King, but I believe the service started at 9:30 AM and went to almost 1:00 PM!  Maybe it was a special MLK weekend service.  The pastors in the mostly white churches I have attended have trouble keeping the attention of the congregation for more than 20 minutes.

Third, the sermon was entirely different from those I had experienced in middle-class white churches.  Less doctrine, though similar theology, and more real life.  The struggles of raising children in poverty.  Grandparents raising their grandchildren. Troubles with children with drug addiction. The struggles of being black in white America.   No pretense of being sinless and perfect, no holier than thou vibe, no judgment, no condemnation, no guilt, no shaming.  All love, compassion, kindness, and forgiveness.  Just like the real Jesus.

Also, the sharing of the same joys and blessings.  New babies, college graduates, marriages, medical recoveries, and others.

“Daddy King” was referred to several times.

It truly echoed the genius and saintliness of Dr. King.

I walked away convinced the Church for the African-American community was much more — that is a considerable part of their life — than what I had experienced in white evangelical America.

Yes, maybe some of us attend more than just Sunday services, but many, such as yours truly, often do so with the dubious motive of seeking the blessings of personal peace and personal prosperity.  The community of the Church, as it for the African-Americans, though not always, is secondary.

The next day, Martin Luther King Jr Day, I spent across the street at the King Center.

More Empathy, Less “Being A Dick“

What great memories from that unforgettable MLK weekend.

I grew up lower-middle class in the white suburbs of Los Angeles, attending an all-white high school.  Fortunately, I had a father, who was politically left of the salad fork (out of a rebellion,  I became a conservative in college),  and also spent my first 25 years playing sports, fighting in the baseball trenches with, pulling for, breaking bread, and downing brewskies with my teammates of color; or as I grew to learn colorless.

I am very thankful for those experiences.  It helped me integrate into and see the real greatness of America.

I feel sad for my many brothers and sisters who have not had the same privilege and are stuck still watching black and white television:  unable or unwilling to embrace and enjoy the tremendous diversity of this great country.

Ditto for the similar ignoramuses from other races and ethnic groups.
 

tv

I can’t imagine eating steak and potatoes every day and every night.

Ignorance And Racism Know No Boundaries

Let me finish by qualifying all of the above.

Racism is such a prominent feature of so many human societies that some evolutionary psychologists have concluded it is “natural” or “innate.”  We don’t know about that but are certain it is not just a “white thing”, a “black thing, or a “brown thing,” etc.

I have shared the story of my brother who was murdered by an undocumented worker, who stated, after stabbing him, “all anglos need to be exterminated.”   This sociopathic asshole killed my brother not because he was brown, or undocumented, but because he was one sick and crazy mother f$@ker.

Now, more than ever it is time to commit to expanding our menu.  Let’s make it a point to understand and enjoy the perspectives and various cultures of all the different races and ethnic groups.

Allegorically, and literally, let’s eat more balaedas, falafel, babaghanoush, borscht, moussaka, and bouilli, among others.  The steak and potatoes will taste sooo much better.

Sorry to end on a note that violates the spirit of Dr. King but I can’t help myself.

Any white man (probably less so for a white woman) who think they know what it is like to be an African-American growing up and living in America, has their head…well…you know where.
 

head

Bring on the hate mail.
Posted in Politics, Uncategorized | Tagged , , | Leave a comment

The Secular Decline in U.S. Manufacturing Employment

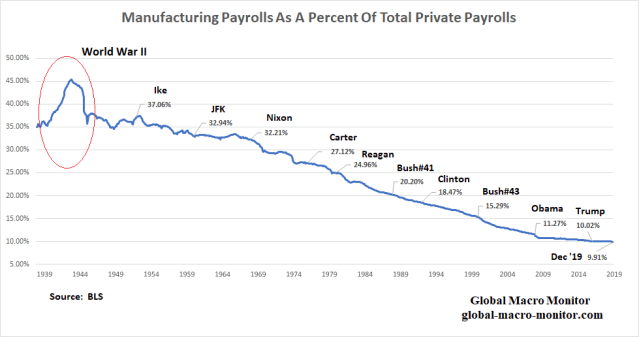
Manufacturing_Payrolls

The title of the post is a bit of a misnomer.

Though the number of manufacturing jobs in the United States is 40 plus percent higher than in 1939, the proportion of total private payrolls hit its lowest level in December at 9.91 percent.

That is there are almost 4m more manufacturing payroll jobs in December 2019 than in January 1939, which at the time — just four months before Germany invaded Poland to start WWII, BTW — made up 35 percent of American nonfarm payroll jobs.  It’s relative, however, as there are also 104m more private-sector payrolls.

Manufacturing peaked as a percentage of private payrolls in the U.S. at 45.30 percent in November 1943 at the height of World War II, when everyone and their mother not in uniform were building tanks and ships. Anybody hear of, or remember Rosie The Riveter?

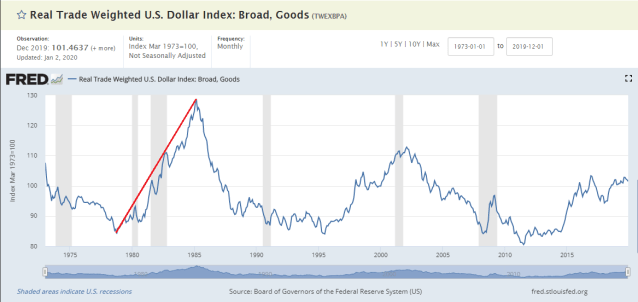
The absolute number of manufacturing jobs peaked at 19.6m in June 1979.  We do have our suspicions the 53 percent real increase in the value of the trade-weighted dollar from October 1978 to March 1985 inflicted a staggering and potentially fatal blow to the U.S. manufacturing sector.  Think hysteresis, folks.

Durable Manufacturing Employment

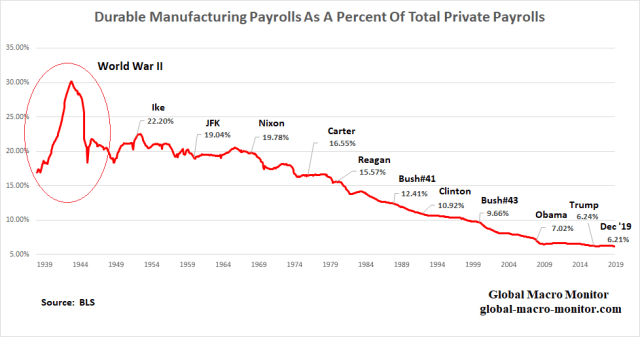
Because the above chart includes both durable and nondurable manufacturing, we have broken out durables.   Nondurables make up 37.3 percent of manufacturing payrolls, with food production about  35 percent of nondurable employment.  It’s our perception most do not think that making cupcakes and craft beer constitute a robust manufacturing sector.  Not surprisingly,  the production of craft beer has been one of the highest growth subsectors in manufacturing payrolls.

Manufacturing_Payrolls_2

The data show that only 6.21 percent of all private-sector payrolls in December 2019 is in the durable goods manufacturing sector, also a historic low.

Golden Age Of Manufacturing Employment 

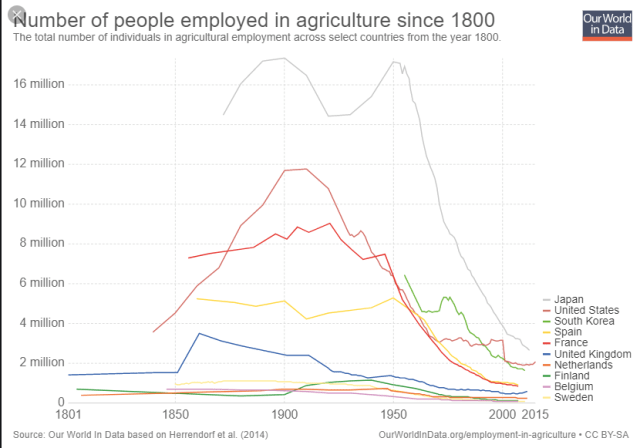
As the data show, the U.S. labor market has been in a secular relative decline moving away from manufacturing jobs.  Believing some minor tweaks to a few trade deals here and there will reverse the trend is Fantasyland and fairy tale thinking.   If anything, robotics and automation are going to take the proportion of manufacturing jobs down to similar levels as those in the agricultural sector, in our opinion.

The chart also clearly illustrates trade is not the only issue affecting the relative decline in manufacturing payrolls and the promised renaissance of manufacturing jobs just ain’t gonna happen.   Policymakers better prepare the public for a high-tech future or there will be more hell to pay, and then some.

The Greatest Economy Ever

President Trump was out again today pounding the table about the “greatest economy ever.”  Man, the B.S. is getting old.

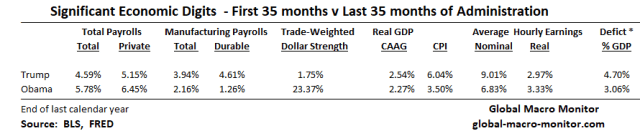
We thought we would let the data speak by juxtaposing the key economic digits in his first three years in office with President Obama’s last three years.   You decide.

Table_Jan20

Dollar

Note the huge headwind caused by the dollar strength in Obama’s last three years.  No doubt it had a major impact on manufacturing payrolls.   Recall our analysis from last July,  which included the following table of the correlation of manufacturing payrolls with the year-on-year change in the trade-weighted dollar.

For example, the correlation between the 3-month moving average of the monthly change in machinery payrolls and the year-on-year change in the value of the trade-weighted dollar index lagged six months, is -0.877 for the period.  That is a stunningly high number, folks, and makes all the economic sense in the world.

Man_4

President Trump would have dropped the hammer and sickle big-time on the Fed if the dollar increased in value just a quarter of the move under Obama.

Wait…doesn’t POTUS hammer the Fed almost on a daily basis and saves his sickle for tariffs?

That’s clearly heavy-handed socialismo, in our book, folks.

Appendix

AG_Payrolls

Dollar_Trade_weighted


Posted in Manufacturing, Uncategorized | Tagged | Leave a comment

How Is That Austrian Century Bond Doing?

I guess it depends on your entry price.   The Austrian 2117 bond chart now looks like a broken stock.

We did notice during summer feeding frenzy and August highs, our bond trading buddies in Europe were pounding the table the loudest that every bond yield in the world was going to zero and beyond.   It’s always loudest at tops.

The whole negative-yielding debt fiasco was generated by a ginormous momentum trade or a greater fool theory, coupled with momentum-driven algos with no context, a dearth of low-risk fixed income securities, and ambiguity of how a new round of QE would unfold in Europe.

We wonder out loud if the proliferation of negative-yielding debt — $16 trillion and counting — would be taking place if humans and not the bots and algos were still in control of the markets?

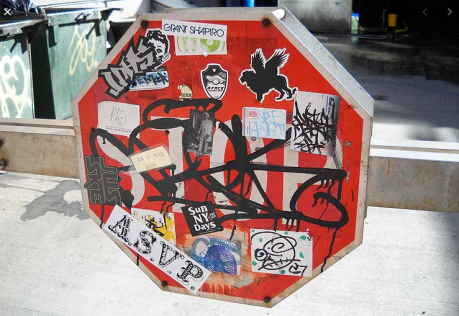
Machines can go places where humans have never dared to venture as they have no context.  Algos in self-driving cars, for example, have no context and thus no ability to recognize a graffiti-ridden stop sign as a stop sign.

For all its impressive progress in mastering human tasks, artificial intelligence has an embarrassing secret: It’s surprisingly easy to fool. This could be a big problem as it takes on greater responsibility for people’s lives and livelihoods…

Indistinguishable changes to a stop sign could make computers in a self-driving car read it as “speed limit 80.”   – Bloomberg


Treasury_Distortion_7

No problem for a human driver even if the stop sign has more tags than a 95-year-old’s armpit.  – GMM, Aug ’19

Was the ECB going to be there to take you out of 10-year bunds yielding -2.0 percent?  That was the bet.

Keep in context the stock of negative-yielding debt is so much greater than the actual number of trades, which took place with negative yields.   Furthermore, negative yields are not equivalent to negative coupons.

Institutional investors may hold a large stock of negative-yielding bonds but how many negative-yielding bonds have they actually purchased?  Some, but probably not a whole helluva lot.

Austrian_Bond

Posted in Uncategorized | Leave a comment

Stocks Get Vertical & Vertigo

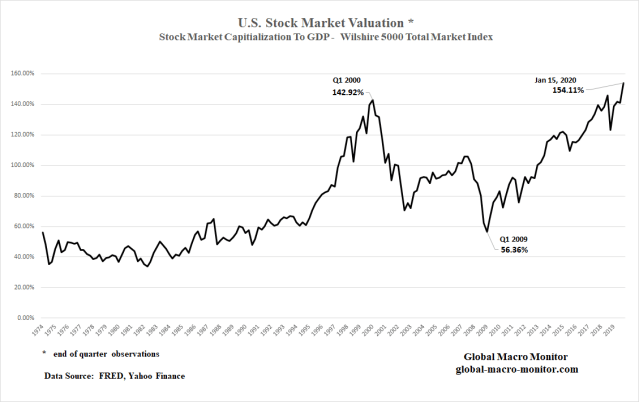
This is some chart.  Even if you assume a structural shift in valuations began when the Fed started backstopping markets after the 1987 crash, that puts the average valuation of the Wilshire Market Cap to GDP at 92.58 percent.   That’s an extremely mean regression to the mean from current levels.

Upshot? 

We are all momentum algo traders now.   When it stops, nobody knows.

Patience, grasshopper.   We wait patiently on the beach for the fever to break.

Stock prices are likely to be among the prices that are relatively vulnerable to purely social movements because there is no accepted theory by which to understand the worth of stocks….investors have no model or at best a very incomplete model of behavior of prices, dividend, or earnings, of speculative assets.  – Robert Shiller,  GMM  Dec’ 10


Stock Valuation


Posted in Equities, Uncategorized | Tagged , , , | 1 Comment

“Phase 1” Of Potemkin Trade Deal Signed, Sealed, And Yet To Deliver

PotemkinDeal

We have been busy collecting bets on the outcome of the U.S.-China Trade Deal.

We never believed for one moment that China would cave on any of the big issues, such as restructuring its economy and any deal would be just some token political salad dressing for the 2020 election.  Most importantly, it moves the needle very little in bringing jobs back to the U.S. rust belt as promised.  The global manufacturing sector is in recession — though appears to be putting in a bottom —  as a result of the administration’s trade policy and the U.S. farm belt has been devastated and may never fully recover.

But. if you know the trip to Disneyland is coming to end, its always best to stay in Fantasyland as long as possible.

So, after all the American economic carnage caused by Trump’s trade war, is the administration about to, or willing to cave on what they said were the most important issues:  1) intellectual property protection, 2) industrial policy reform?

Will Trump cut another meaningless Potemkin Trade Deal?  – GMM, Nov ’19

Socialism

Moreover, much of the deal depends on whether the Chinese will abide by Soviet-style import quotas.  Whatever happened to free markets?  Import quotas and managed trade are about as a socialist economic policy there is,  folks, except for maybe nationalizing the “commanding heights” of the economy.

We also thought “Socialism” was a big trigger word in the U.S. body politic?

But, hey, it is 1984-ish out there and even most golfers do not believe the USGA handicap system is tantamount to welfare.  In our local skins games,  the first question we ask our opponents upon moving to the next tee box is, “how many food stamps do you get on this hole.”  We do not disparage those on SNAP “as there but by the Grace of God go we.”

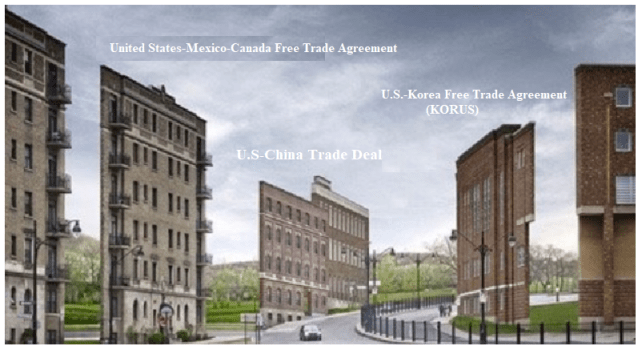
The deal has caused lots of pain with little gain, much like the USMCA — though USMCA was more diplomatic than economic pain as there is very little difference in NAFTA and NAFTA 2.0 (USMCA).

World Is Still Worse Off

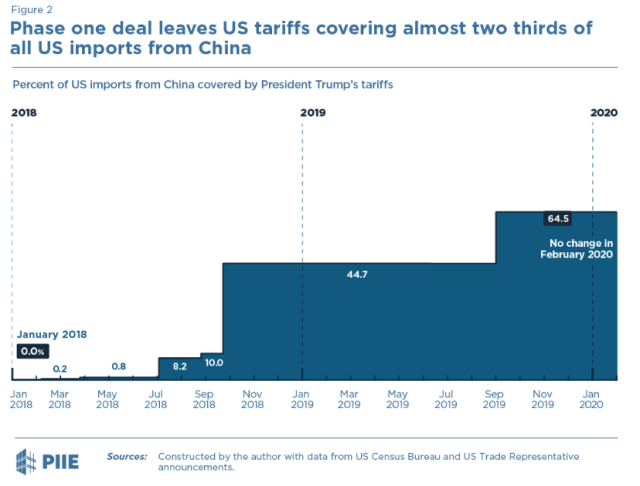
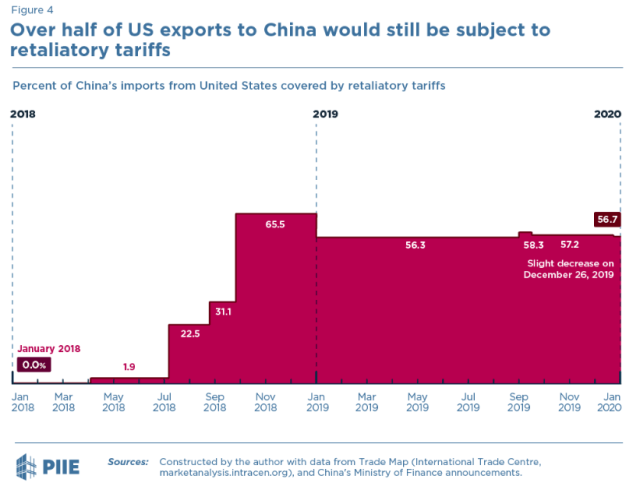
The world — not stockholders — is worse off today than when the tariff war began as illustrated by the Peterson Institute for International Economics (PIIE) charts below.   Mr. Market was surprised yesterday that the tariffs are remaining in place?  Now that’s efficient but not surprising as he is going through one of those phases experienced about every ten years.

We are thankful, however,  the economic hostilities have momentarily ratcheted down but the game is hardly over.

We hope the World Trade Organization will reinvent itself, strip China of its developing country status, which allows for special and differential treatment, and we move back from the brink to a rules-based global trading system.

Dog Food

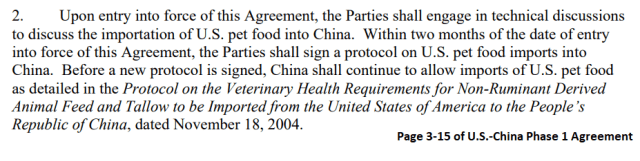
The following excerpt from the text of the deal exemplifies our perception:

Trade_Deal_7

How many S&P points is the above paragraph worth?

Both parties will begin discussions on China’s imports of, say, dog food?

Seriously, after more than two years of negotiations, they couldn’t even agree on dog and cat food imports?   

We fear tariffs are the new paranormal.

Trade_Deal_1

Source:  PIIE

Trade_Deal_2

Trade_Deal_4

Trade_Deal_5

Trade_Deal_6

Posted in Trade War, Uncategorized | Tagged , | Leave a comment

The New Quant Strategy

Posted in Uncategorized | Leave a comment

U.S. Treasury Borrowing & QE Forever

The U.S. Treasury recently released the December monthly statement, which put us to work crunching the data.  Note the Treasury is on an October-September fiscal year.  We are using calendar years in our analysis.

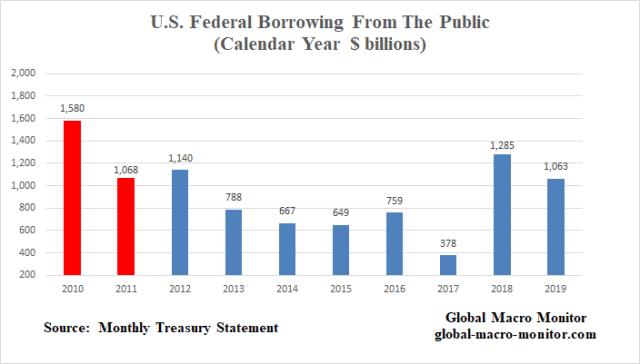
Federal Borrowing From The Public

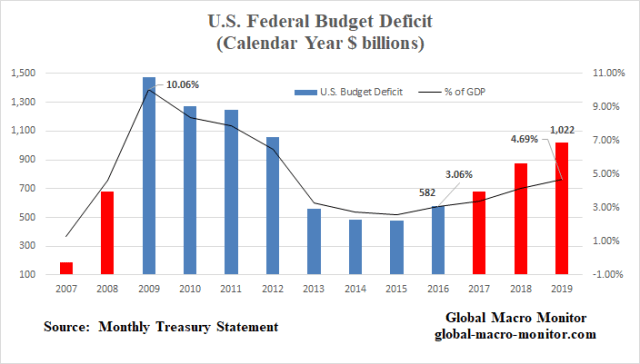
The following chart illustrates the increasing pressure on the private markets given the spike in the U.S. budget deficit, which has almost doubled since 2016 to over $1 trillion in 2019.   It is much easier for the Treasury to float a trillion of debt during recessions or risk-off markets as haven flows are starved for riskless assets.  Supply is not an issue as demand is overwhelming.

We believe the big spike in borrowing in 2018 crowded out other markets, which put upward pressure on long-term interest rates in September causing the stock market to tumble 20 percent in Q4.  The Fed had to ride to the rescue and thus abandon its balance sheet normalization program.

In 2019, the Treasury’s borrowing pressure on the markets continued and forced the Fed to introduce it’s “not QE” policies to help calm the repo and money markets.   The long-end of the Treasury market was anchored by yield-seeking record foreign private inflows.

We are not ignoring the issue of why the Fed funds market did not help alleviate the repo rate spikes but just isolating our analysis to collateral supply and will leave the banking issues and analysis up to the experts.  At the end of the day, however, nobody really knows for certain what is going on.

Budget_1

The Supply Shock Caused By the Debt Ceiling

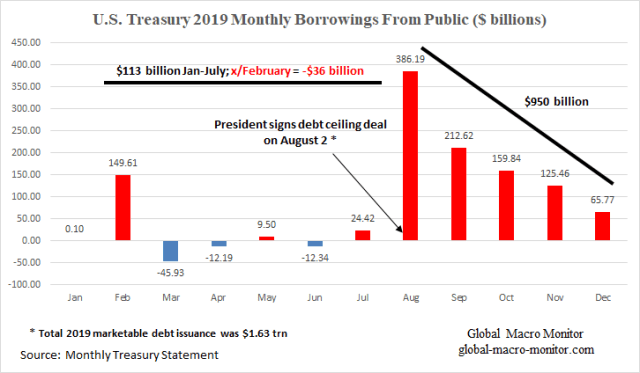
We have updated the following chart, which illustrates the “supply shock” caused by the lifting of the debt ceiling in August.  From January to July, the Treasury was forced by the debt ceiling to curb its borrowing and financed itself through running down its operating cash at the Fed and by other means, such as running arrears on federal pension funds.  Borrowing from the public only increased by a sum total of $113 billion during this seven month period and when the February borrowings are excluded, the Treasury took out a negative $36 billion from the public markets.

After the debt deal was signed in August, the Treasury borrowed almost $1 trillion from the public in the last five months of the year.   That is a huge supply shock, folks. Treasury officials are pretty good at managing disruptions to the markets and keeping guard of the yield curve but it does seem the budget beast is getting just too big to tame.

Such a public debt supply shock can partially explain, in our opinion,  the repo and money market turmoil and the coincidental timing of both do not go unnoticed.

Deficit_1


We don’t know but it is possible the money markets may calm down after the initial shock works through the system.  Then, again maybe not.  The Fed may be forced to buy a boatload of Bills as central banks used to hold almost 50 percent of all T-Bills outstanding.  They now hold only around 15 percent of the much larger stock, adding more pressure on the money markets.

Le Chatelier’s Principle

Another important point is that interest rates are not allowed to move to their market-clearing equilibrium levels, where the supply of loanable funds and capital meets demand for borrowing.

It’s a classic case of Le Chatelier’s principle (LCP) in action.  If one economic variable is repressed in a dynamic equilibrium system, such as prices or interest rates and not allowed to adjust to clear the market, another variable in the system will have to move to offset.  The great economist, Paul Samuelson, did his Ph.D. dissertation on LCP.  – GMM, Sept ’19

No wonder why the money markets are going batshit.

U.S. Budget Deficit

The U.S. budget deficit has almost doubled in the past three years, which is rare during a period of positive GDP growth.


Budget_2

Budget Expenditures

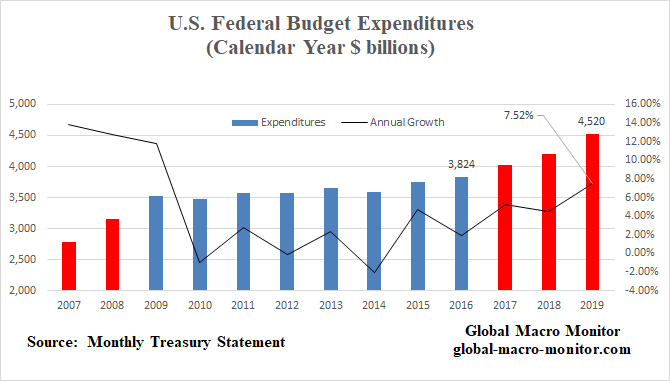
Note total Federal budget expenditures increased by over 7.5 percent in 2019 at a rate not seen since the GFC.

Budget_4

Budget Revenues

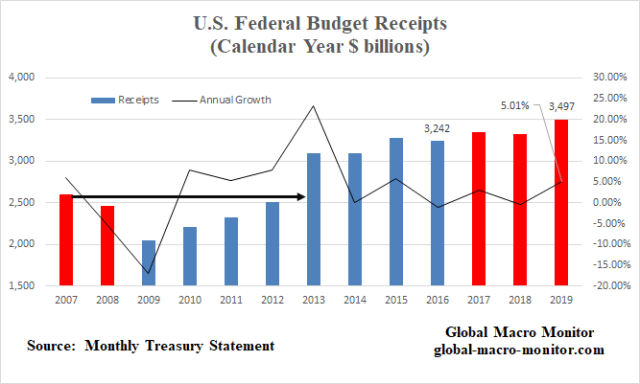
What surprised us about this chart was that the absolute level of budget receipts did not retain their 2007 pre-GFC levels until 2013, illustrating how ugly the economic downturn was and it deleterious impact on government revenues.  It also shows how recession and the subsequent collapse of budgetary receipts blows up the deficit.


Deficit_2

Upshot

Washington has thrown all semblance of budget discipline to the wind and, in our opinion, will increasingly have to depend on the Fed to help finance its spending without crowding out markets and tanking risk markets.   It is important to watch foreign private inflows into the Treasury market, which has already broken the annual record inflow even with only the latest data from  October.

The Treasury’s dependence on foreign savings to finance itself keeps a lid on long-term rates. Moreover,  private investors are much more sensitive to market pricing than foreign central banks, who make up 61 percent of foreign holders of close to $7 trillion in Treasury securities.   The Treasury is becoming more reliant on “hot money” flows.

Based on this analysis, we conclude the two big tail risks to monitor with respect to another public sector financing shock:  1) inflationary pressures, which could take the Fed out of the deficit financing game and spike interest rates, and 2) a reversal of foreign private inflows into the Treasury market, already at a record annual inflow of almost $350 billion as of October, which would put upward pressure on long-term interest rates.  The U.S. budget deficit in 2020 will be the equivalent of almost 90 percent of global foreign savings (current account surpluses).

Recession or slowdown fears, however,  will bring haven flows into Treasuries and repress interest rates even further.


TIC_Flows

Posted in Budget Deficit, Fed, Uncategorized | Tagged , , | 1 Comment